As Expected, the FOMC Raises Its Federal Funds Rate Target

Photo from federalreserve.gov

Today, the Federal Open Market Committee (FOMC) met expectation by raising its target range for the federal funds rate by 0.25 percentage points (25 basis points) from the range of 3.50 percent to 3.75 percent that had prevailed since December 10 of last year. As of yesterday, trading in the federal funds rate futures market had implied a 93.5 percent probability of a 25 basis point increase. Financial markets had been convinced that a rate increase was coming since Fed Chair Kevin Warsh’s speech at the Federal Reserve Bank of Kansas City’s economic policy symposium in Jackson Hole, Wyoming in late August. (We discussed Warsh’s speech in this blog post.) There had been some speculation in the business press that one or more committee members would dissent from a rate increase, but the vote turned out to be unanimous. Today was the first time the committee had increased the target range since July 2023.

The following figure shows for the period from 2001 through yesterday, the upper bound (the blue line) and the lower bound (the green line) for the FOMC’s target range for the federal funds rate, as well as the actual values for the federal funds rate (the red line). Before December 2008, the Fed announced a single numerical target for the federal funds rate, rather than a target range. Note that the Fed has been successful in keeping the value of the federal funds rate in its target range. (We discuss the monetary policy tools the FOMC uses to maintain the federal funds rate within its target range in Macroeconomics, Chapter 15, Section 15.2 (Economics, Chapter 25, Section 25.2).)
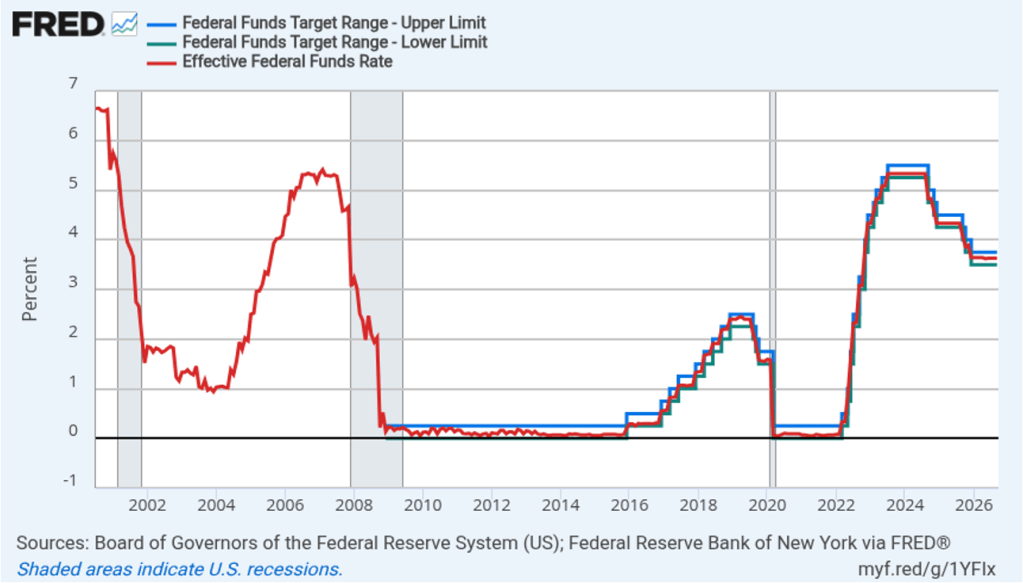
As with the policy statements issued following Warsh’s previous two FOMC meetings, today’s policy statement was short and did not include any discussion of the circumstances under which further target rate increases might occur—so-called forward guidance. We discuss forward guidance in Macroeconomics, Chapter 15 (Economics, Chapter 25).
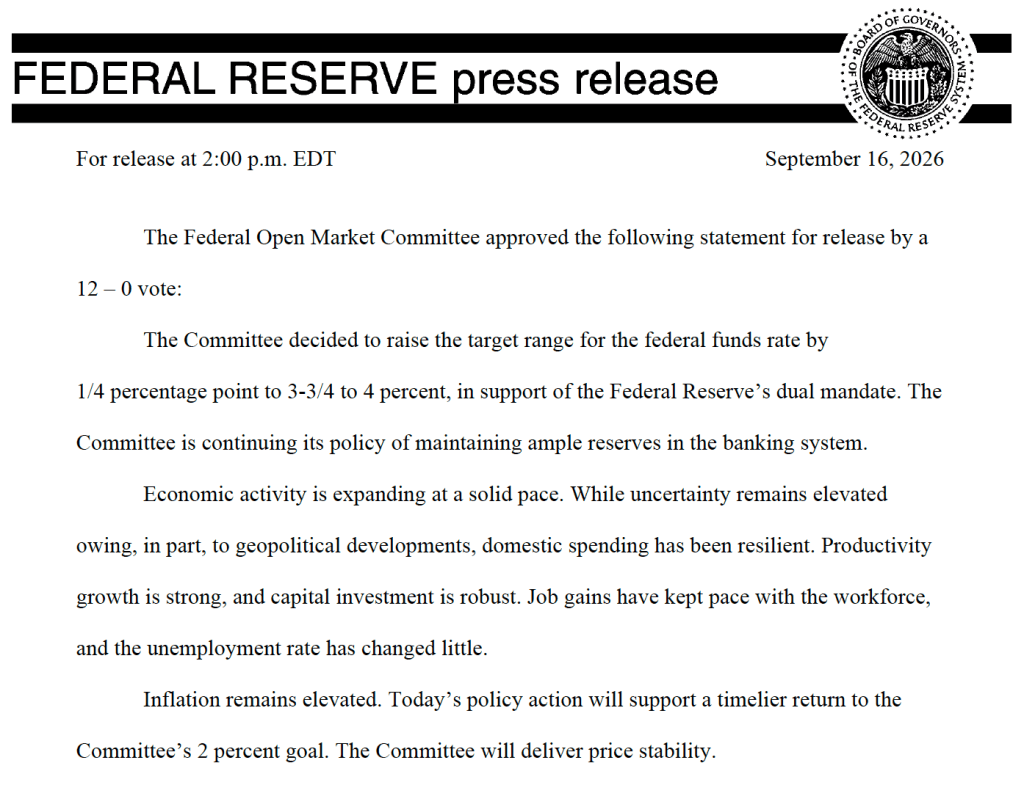
After the meeting, the committee also released a “Summary of Economic Projections” (SEP)—as it typically does at its March, June, September, and December meetings. The SEP presents median values of the, typically, 19 committee members’ forecasts of key economic variables. In a press conference following the meeting, Warsh indicated that he didn’t submit forecasts, just as he hadn’t submitted forecasts for the SEP released after the June meeting. He indicated that the future of the SEP is one of the issues to be considered by his new committee on Fed communications.

The forecasts of key economic variables from the SEP are summarized in the following table, reproduced from the release. (Note that only 5 of the district bank presidents vote at FOMC meetings, although all 12 presidents participate in the discussions and prepare forecasts for the SEP.)
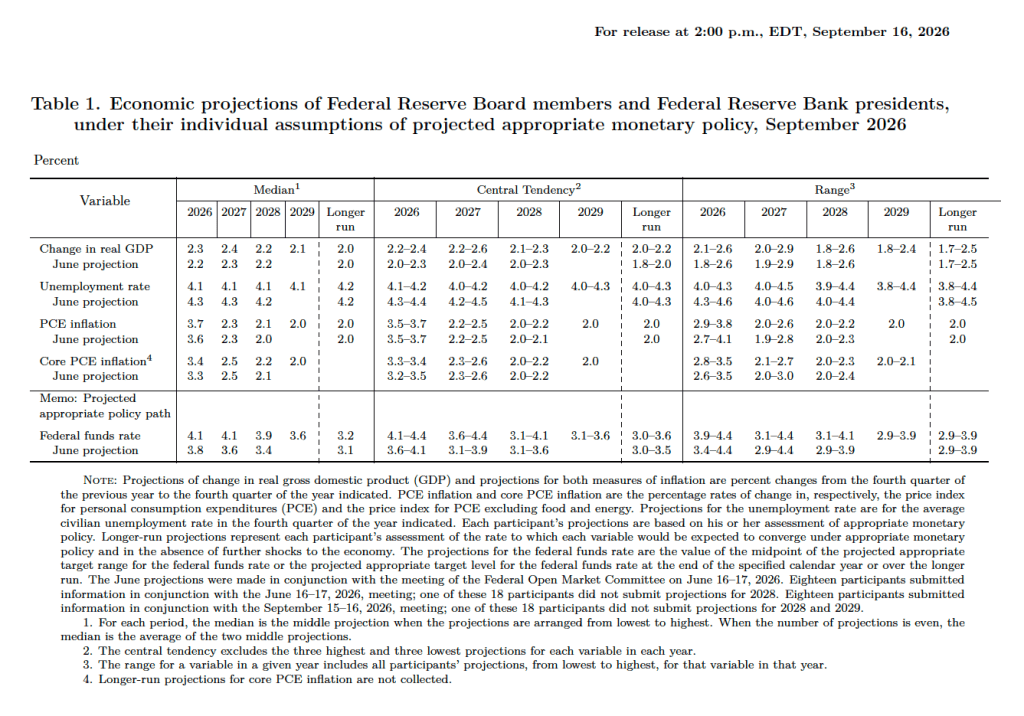
There are several aspects of these forecasts worth noting:

  1. Compared with the previous SEP in June, the committee members raised their forecast of real GDP growth in 2026 slightly from 2.2 percent to 2.3 percent. The committee members left unchanged their forecast of long-run growth in real GDP at 2.0 percent. The unchanged long-range forecast indicates that the committee members are not anticipating a large, sustained increase in economic growth caused by increased use of artificial intelligence (AI). Consistent with raising their forecast of real GDP growth in 2026, the committee lowered its forecast of the unemployment rate in the fourth quarter of 2026 from 4.3 percent to 4.1 percent. The committee members left their forecast of the long-run rate of unemployment, often called the natural rate of unemployment, unchanged at 4.2 percent. 
  2. Committee members raised their forecast of personal consumption expenditures (PCE) price inflation in 2026 to 3.7 percent from 3.6 percent in June. They left their forecast of inflation in 2027 unchanged at 2.3 percent and forecast that PCE inflation would not decline to the Fed’s 2.0 percent annual target until 2029.
  3. The committee’s forecasts of the federal funds rate at the end of each year from 2026 through 2028 were increased, indicating that the committee sees the federal funds rate as likely to be “higher for longer.” The forecast for the long-run federal funds rate was raised from 3.1 percent to 3.2 percent.

There is always much discussion in the business press and among investment analysts about the dot plot, shown below. Each dot in the plot represents the projection of an individual committee member. (The committee doesn’t disclose which member is associated with which dot.) Note that there are 18 dots, representing the 6 members of the Fed’s Board of Governors who provided forecasts and all 12 presidents of the Fed’s district banks.
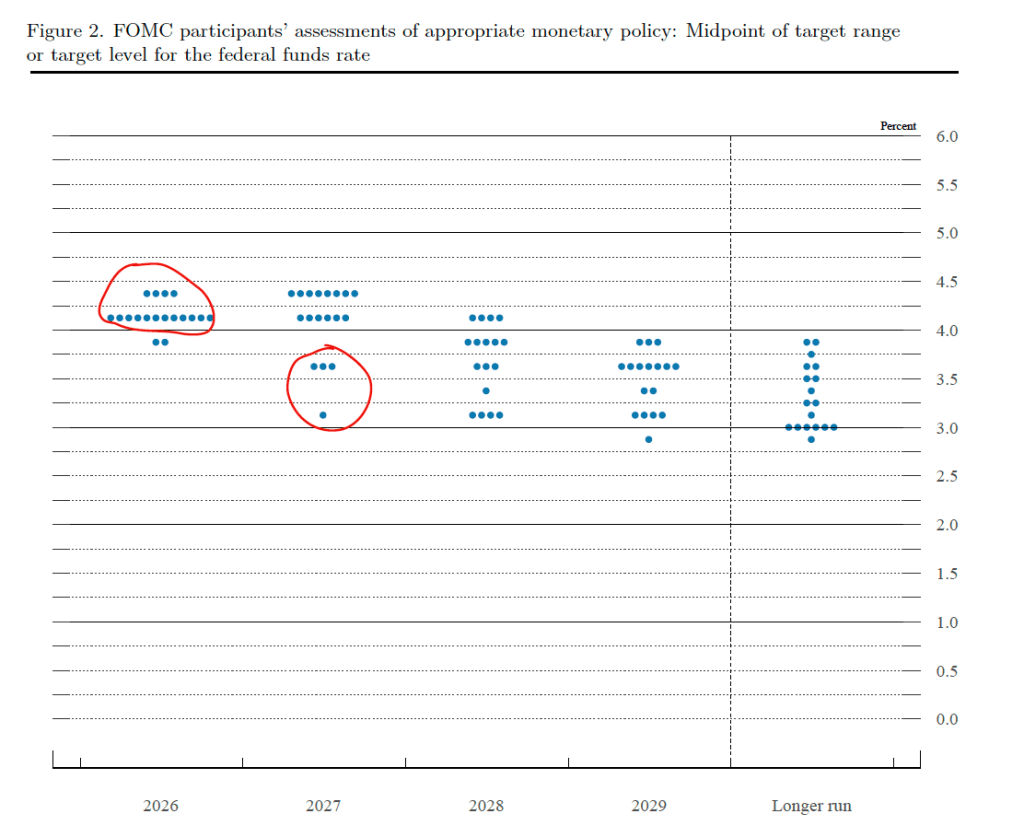
The dots plotted on the far left of the figure represent the projections by the 18 members of the value of the federal funds rate at the end of 2026. The plots indicate that, at this point, 16 members of the committee (circled in red) forecast at least one additional 25 basis point increase in the target range for the federal funds rate before the end of the year, with only 2 members expecting that there will be no further increases this year. For 2027, four members (circled in red) expect that the target range will be cut during the year, with the rest expecting either that the rate increases made this year will be maintained or that there will be one additional 25 basis point increase. The dots plotted on the far right of the figure indicate that there is substantial disagreement among committee members as to what the long-run value of the federal funds rate—the so-called neutral rate—should be. Of course, the plots only represent the forecasts of the committee members and individual committee members are likely to adjust their forecasts as additional macroeconomic data become available in the coming months.

At his press conference following the meeting, Warsh resisted attempts by reporters to get him to expand on the circumstances under which the committee might implement further increases in the target range. He characterized today’s rate increase as removing “a dose of accommodation” from the economy, which reflected the committee’s belief that the economy was experiencing full employment with persistently high inflation. The closest he came to engaging in forward guidance was the statement that “We must be confident that underlying inflation is moving towards our objective. This has not been satisfied.”

Warsh was asked what had changed since the July meeting at which the committee had kept the target range unchanged. in reply, he indicated that the committee believed that since July the economy had strengthened, inflation had continued to above target, and “geopolitical” factors had contributed to higher prices.

No Sign of Cooling Inflation in September CPI Report

Image created by ChatGPT

Today’s report from the Bureau of Labor Statistics (BLS) on the consumer price index (CPI) for August was eagerly awaited by economists and policy analysts. As we discuss in Macroeconomics, Chapter 15 (Economics, Chapter 25), monetary policy affects the economy with, in the words of Nobel Laureate Milton Friedman, “long and variable lags.” As a result, most economists agree that the Federal Reserve should not attempt to “fine tune” the economy by responding to each government release of macroeconomic data.

There are some instances, however, including the present, when the Fed’s policymaking Federal Open Market Committee (FOMC) appears to be uncertain as to whether a change in policy is needed. As a result, there was a widespread expectation that if today’s report indicated that inflation is slowing, the FOMC would likely leave its target for the federal funds rate unchanged at its meeting on Tuesday and Wednesday of next week. But if the report didn’t indicate that inflation is slowing, the committee would likely raise its target. The report gave few indications that inflation is slowing.

The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).

  • The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.4 percent in August, the same as in July. 
  • The core inflation rate, which excludes the prices of food and energy, was 2.4 percent in August, down from 2.5 in July.  

Headline inflation was slightly higher, and core inflation was equal, to the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)

In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline (the blue line) was 4.6 percent In August, up from 0.9 percent in July. Core inflation (the red line) was 3.5 percent in August, up from 2.6 percent in July.

The following figure illustrates the role played by energy prices in contributing to the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had declined at an annual rate of 16.4 percent in July, increased at an annual rate of 28.3 percent in August. The blue line shows the 1-month inflation rate in gasoline prices, which had declined at an annual rate of 29.4 percent in July, increased at an annual rate of 58.3 percent in August.

There had been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and in the category “food away from home” (the red bar)—primarily food purchased at restaurants. Grocery prices, which had declined at annual rate of 0.9 percent in July, increased at an annual rate of 0.4 percent in August. Food prices away from home increased 3.1 percent in August, down from 3.9 percent in July. To this point, increases in energy prices seem to have had some effect on grocery prices and restaurant prices, although the extent of the effect is unclear.

Fed Chair Kevin Warsh has indicated that he favors measures of the inflation rate that exclude particularly small or particularly large changes in the prices of some goods or services—so-called outliers. Median CPI, which is compiled monthly by economists at the Federal Reserve Bank of Cleveland, is calculated by ranking the price changes of every good or service in the index from the largest price change to the smallest price change, and then choosing the price change in the middle. The idea is to eliminate the effect on measured inflation of any short-lived events that cause the prices of some goods and services to be particularly high or particularly low. Economists at the Cleveland Fed have conducted research that shows that, in their words, “the median CPI provides a better signal of the underlying inflation trend than either the all-items CPI or the CPI excluding food and energy. The median CPI is even better at forecasting [personal consumption expenditures] PCE inflation in the near and longer term than the core PCE price index.”

Trimmed-mean inflation, also compiled by economists at the Cleveland Fed, excludes the highest 8 percent of price changes and the lowest 8 percent. The following figure shows 1-month trimmed mean (the blue line) and median (the red line) CPI inflation. Trimmed-mean inflation was 2.7 percent in August, unchanged from July. Median inflation was 2.1 percent in August, down from 3.1 percent in July. So these measures of inflation are both lower than the conventional headline and core CPI inflation measures, although as the figure shows, both measures are volatile.

Note that the Fed uses the 12-month change in the personal consumption expenditures (PCE) price index, not the change in the CPI, when gauging whether it is hitting its 2 percent annual inflation target. Historically, PCE inflation has been about 0.4 percentage points to 0.5 percentage points lower than CPI inflation. The Bureau of Economic Analysis (BEA) won’t release its estimate of August PCE inflation until September 30, after the next FOMC meeting.

Today’s report showing that inflation remains persistently above the Fed’s 2 percent annual target, following last week’s jobs report showing an unexpectedly large increase in employment, has likely raised the chance that Federal Reserve policymakers will increase their target range for the federal funds rate from the current 3.50 percent to 3.75 percent by o.25 percentage points (or 25 basis points) at the next meeting of the FOMC on September 15–16. Trading in the federal funds futures market this afternoon indicates that investors assign a 86.5 percent probability to the FOMC raising its target range at that meeting, which is up from a 72.4 probability yesterday. Trading indicated that investors assign a 74.5 percent probability to the committee increasing its target range by at least 50 basis points by the end of the year, up from 64.6 percent yesterday and from 44.7 percent one week ago.

Fed Chair Warsh Takes a More Hawkish Stand in Address at Jackson Hole

Federal Reserve Chair Kevin Warsh (Photo from federalreserve.com)

Each year since 1982, the Federal Reserve Bank of Kansas City has sponsored an economic policy symposium in Jackson Hole, Wyoming. (The site was supposedly first chosen in the hopes that Fed Chair Paul Volcker would attend because of the opportunities for fly fishing in the local area.)

In most years since 1989, the Fed chair has given the keynote address at the symposium. The address gives the Fed chair a chance to provide his or her assessment of the state of the U.S. economy and the outlook for inflation and employment—the two parts of the dual mandate Congress has given to the Fed.

Image created by ChatGPT

This year’s address by Fed Chair Kevin Warsh was highly anticipated. In his press conference following the last meeting of the Fed’s policymaking Federal Open Market Committee (FOMC), Warsh reiterated his determination to bring inflation back to the Fed’s 2 percent annual target. But he faced a number of questions from reporters as to why, with inflation running well above 2 percent, he wasn’t advocating an increase in the FOMC’s target for the federal funds rate. Warsh has stated that he wantesto steer the committee from using forward guidance to affect interest rates. Accordingly he was reluctant to state explicitly what direction Fed policy might take.

Investors in the bond market appear to have interpreted Warsh’s statements as “dovish”; that is, they believed that his reluctance to support rate increases indicated that inflation might remain above the Fed’s target for longer. As we discussed in earlier blog posts, when investors believe that inflation will be higher they require that bond yields rise enough to compensate them for the additional purchasing power. (As we discuss in Money, Banking, and the Financial System, Chapter 4, economists refer to the increase in nominal interest rates following an increase in the expected inflation rate as the Fisher effect.) The rise in the yield on the 30-year Treasury bond in the days following Warsh’s press conference likely reflected bond investors expecting somewhat higher inflation than they had previously.

In today’s address, Warsh attempted to counter the conclusion that he is reluctant to increase interest rates to slow the rate of inflation. First, though, he repeated his opposition to Fed chairs routinely engaging in forward guidance: “Oversharing policy deliberations and overcommitting to future decisions can lead markets, businesses, and households astray. And I believe when policymakers make quasi-commitments on interest rates through the cycle, we inhibit our own freedom to make the right calls when it’s time to decide.”

He again stated forcefully his commitment to the Fed’s inflation target: “The Fed’s price-stability objective of 2 percent, as measured by the personal consumption expenditures (PCE) price index, is a firm, fixed target. … It is the Fed’s job to deliver stable prices.” He noted that all measures of inflation “tell a similar story: Inflation is running above our 2 percent target. So the Fed’s predominant focus right now should be on prices.”

Warsh also observed that “progress over the past two years [toward the 2 percent target] has been modest.” He concluded that: “There is one signal nobody can miss: The responsibility for 65 months of sustained, elevated inflation sits squarely with the central bank. And that is where it belongs.”

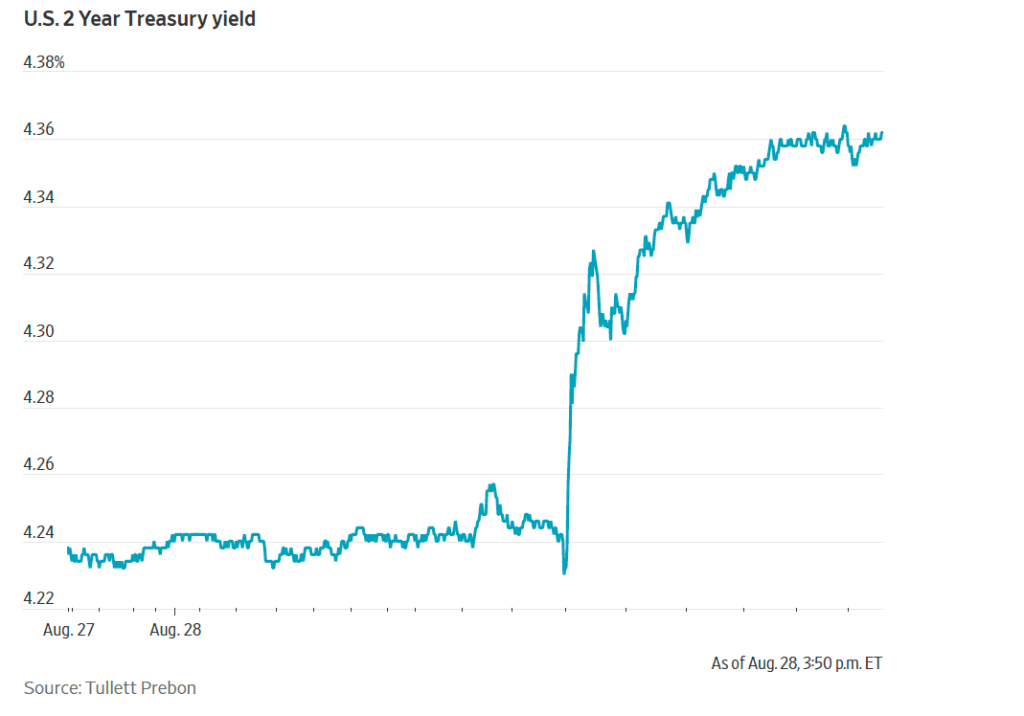
The following figure from the Wall Street Journal reflects the bond market’s immediate reaction when the text of Warsh’s address was released.

The two-year Treasury note is directly affected by investors’ expectations of the future path of the federal funds rate. (We discuss this link in Money, Banking, and the Financial System, Chapter 5.) Investors interpreted Warsh’s address as indicating he would take a more “hawkish” view of the need to raise the FOMC’s target for the federal funds rate than he had appeared to take in his earlier press conference.

Investors in the federal funds future market also quickly revised their expectations of the likelihood of the FOMC raising its target for the federal funds rate. Trading in the futures marker resulted in the probability increasing from 35.4 percent yesterday to 57.5 percent this afternoon of the committee raising its target range for the federal funds by 0.25 percentage points (25 basis points) at its next meeting on September 15–16. The probability that after the meeting on October 27–28, the committee will have raised its target range by at least 25 basis points increased from 52.6 percent yesterday to 70.7 percent this afternoon.