Fed Chair Warsh Takes a More Hawkish Stand in Address at Jackson Hole

Federal Reserve Chair Kevin Warsh (Photo from federalreserve.com)

Each year since 1982, the Federal Reserve Bank of Kansas City has sponsored an economic policy symposium in Jackson Hole, Wyoming. (The site was supposedly first chosen in the hopes that Fed Chair Paul Volcker would attend because of the opportunities for fly fishing in the local area.)

In most years since 1989, the Fed chair has given the keynote address at the symposium. The address gives the Fed chair a chance to provide his or her assessment of the state of the U.S. economy and the outlook for inflation and employment—the two parts of the dual mandate Congress has given to the Fed.
Image created by ChatGPT

This year’s address by Fed Chair Kevin Warsh was highly anticipated. In his press conference following the last meeting of the Fed’s policymaking Federal Open Market Committee (FOMC), Warsh reiterated his determination to bring inflation back to the Fed’s 2 percent annual target. But he faced a number of questions from reporters as to why, with inflation running well above 2 percent, he wasn’t advocating an increase in the FOMC’s target for the federal funds rate. Warsh has stated that he wantesto steer the committee from using forward guidance to affect interest rates. Accordingly he was reluctant to state explicitly what direction Fed policy might take.

Investors in the bond market appear to have interpreted Warsh’s statements as “dovish”; that is, they believed that his reluctance to support rate increases indicated that inflation might remain above the Fed’s target for longer. As we discussed in earlier blog posts, when investors believe that inflation will be higher they require that bond yields rise enough to compensate them for the additional purchasing power. (As we discuss in Money, Banking, and the Financial System, Chapter 4, economists refer to the increase in nominal interest rates following an increase in the expected inflation rate as the Fisher effect.) The rise in the yield on the 30-year Treasury bond in the days following Warsh’s press conference likely reflected bond investors expecting somewhat higher inflation than they had previously.

In today’s address, Warsh attempted to counter the conclusion that he is reluctant to increase interest rates to slow the rate of inflation. First, though, he repeated his opposition to Fed chairs routinely engaging in forward guidance: “Oversharing policy deliberations and overcommitting to future decisions can lead markets, businesses, and households astray. And I believe when policymakers make quasi-commitments on interest rates through the cycle, we inhibit our own freedom to make the right calls when it’s time to decide.”

He again stated forcefully his commitment to the Fed’s inflation target: “The Fed’s price-stability objective of 2 percent, as measured by the personal consumption expenditures (PCE) price index, is a firm, fixed target. … It is the Fed’s job to deliver stable prices.” He noted that all measures of inflation “tell a similar story: Inflation is running above our 2 percent target. So the Fed’s predominant focus right now should be on prices.”

Warsh also observed that “progress over the past two years [toward the 2 percent target] has been modest.” He concluded that: “There is one signal nobody can miss: The responsibility for 65 months of sustained, elevated inflation sits squarely with the central bank. And that is where it belongs.”

The following figure from the Wall Street Journal reflects the bond market’s immediate reaction when the text of Warsh’s address was released.
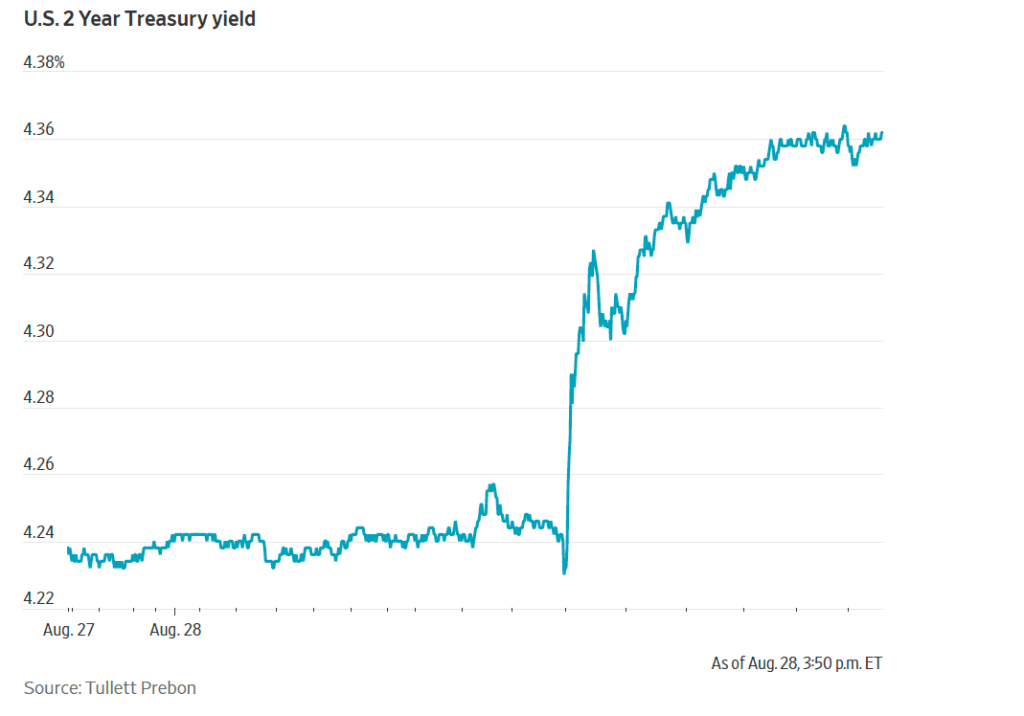
The two-year Treasury note is directly affected by investors’ expectations of the future path of the federal funds rate. (We discuss this link in Money, Banking, and the Financial System, Chapter 5.) Investors interpreted Warsh’s address as indicating he would take a more “hawkish” view of the need to raise the FOMC’s target for the federal funds rate than he had appeared to take in his earlier press conference.

Investors in the federal funds future market also quickly revised their expectations of the likelihood of the FOMC raising its target for the federal funds rate. Trading in the futures marker resulted in the probability increasing from 35.4 percent yesterday to 57.5 percent this afternoon of the committee raising its target range for the federal funds by 0.25 percentage points (25 basis points) at its next meeting on September 15–16. The probability that after the meeting on October 27–28, the committee will have raised its target range by at least 25 basis points increased from 52.6 percent yesterday to 70.7 percent this afternoon.
Inflation, Interest Rates, and Stock Prices

Caution: Long post!

An article in the Wall Street Journal quoted an economist at a financial services firm as noting that strong growth in wages could lead to sustained inflation. The article stated that as a result “the yield on the 10-year U.S. Treasury note [rose to] within reach of 2%” and that: “Rising [bond] yields this year have rattled markets and hurt tech stocks in particular ….”

What are the links between wage inflation and price inflation, inflation and bond yields, and bond yields and stock prices—particularly the prices of tech stocks?

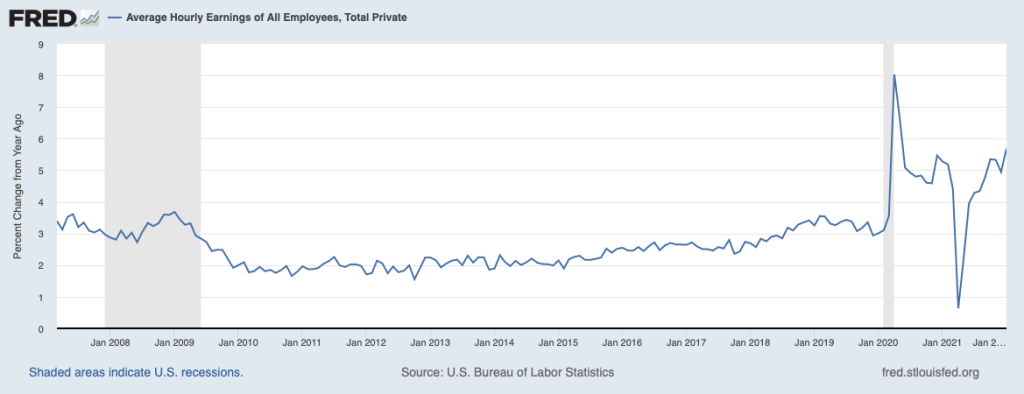
The link between wage inflation and price inflation. The monthly “Employment Situation” reports from the Bureau of Labor Statistics (BLS), in addition to providing data on payroll employment and the unemployment rate, also provide data on average hourly earnings (AHE). AHE are the wages and salaries per hour worked that private, nonfarm business pay workers. AHE don’t include the value of benefits that firms provide workers, such as contributions to 401(k) retirement accounts or health insurance. The following figure shows changes in AHE from the same month in the previous year. The figure shows that since the Covid-19 pandemic first began to affect the U.S. economy in March 2020, AHE have moved erratically. But since the fall of 2021, growth in AHE has been consistently above the 2 percent to 4 percent range that prevailed in the years after the end of the Great Recession of 2007–2009.

Employee compensation is the largest cost for most firms.  For the economy as whole, employee compensation is about 80 percent of total costs. When firms pay higher wages per hour, their costs per unit of output don’t rise unless the wage increases are greater than the rate of growth of labor productivity, or output per hour worked. Increases in wages in the range of 5 percent to 6 percent are well above the rate of growth of labor productivity and, so, firms are likely to pass through the wage increases by raising prices. Note that the higher prices may prompt workers to push for higher wage increases to offset the decline in the real purchasing power of their wages, potentially setting off a wage-price spiral. (We discussed the possibility of a wage-price spiral in a recent post here.)

The link between inflation and bond yields.  When investors lend money by, for instance, buying a bond, they are concerned with the interest rate they will receive after correcting for the effects of inflation. In other words, they focus on the real interest rate, which is equal to the nominal interest rate, or the stated interest rate on the loan or bond, minus the expected inflation rate:

            Real interest rate = Nominal interest rate – Expected inflation rate.

We can rewrite this relationship as:

            Nominal interest rate = Real interest rate + Expected inflation rate.

The second equation indicates that if investors expect the inflation rate to increase, then, unless the real interest rate changes, the nominal interest rate will increase.  The Fisher effect is the idea associated with Yale economist Irving Fisher that the nominal interest rate rises or falls by the same number of percentage points as the expected inflation rate. So, for instance, if investors expect that the inflation rate will increase from 3 percent to 5 percent, then the nominal interest rate will also increase by two percentage points.

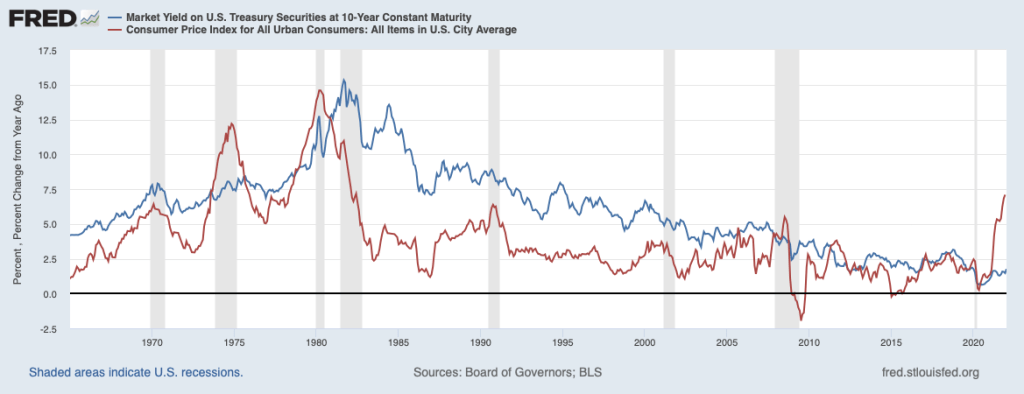
Because of real-world frictions, such as the broker fees that investors pay when buying and selling bonds and the taxes investors pay when they sell a bond that has increased in price, the Fisher effect doesn’t hold exactly. Still, most economists agree that an increase in the expected inflation rate will cause an increase in nominal interest rates. The following figure shows movements in the interest rate on 10-year Treasury notes (blue line) and in inflation (red line). Note that, roughly speaking, the interest rate on the 10-year Treasury note is higher when inflation is higher and lower when inflation is lower.  (We discuss real and nominal interest rates in Macroeconomics, Chapter 9, Section 9.6 and in Economics, Chapter 19, Section 19.6. We discuss the Fisher effect in Money, Banking, and the Financial System, Chapter 4, Section 4.3.)

The link between bond yields and stock prices. As wage inflation leads to price inflation and price inflation leads to higher interest rates on bonds—particularly U.S. Treasury bonds—why might stock prices be affected? First, investors consider U.S. Treasury bonds to be default risk free, which means that investors are certain that the Treasury will make the interest and principal payments on the bonds. Stock investments are much riskier because they depend on the future profits of the firms issuing the stocks and those profits may fluctuate in ways that are difficult for investors to anticipate. So as interest rates on Treasury bonds increase, some investors will decide to sell stocks and buy bonds, which will cause a decline in stock prices. 

Second, most people value funds they will receive now or soon more highly than funds they will receive in the more distant future. For instance, if someone offered to pay you $1,000 today or $1,000 one year from now, you will prefer to receive the money today.  In other words, the present value, or value today, of a payment you won’t receive until the future is worth less than the face value of the payment. For instance, the present value of $1,000 you won’t receive for a year is worth less than $1,000 in present value. The higher the interest rate is, the lower the present value of payments, such as dividends, that you will receive in the future. 

Economists believe that price of a financial investment, like a bond or a stock, is equal to the present value of the payments you will receive from owning the asset. If you own a bond, you will receive interest payments and payment of the bond’s principal when the bond matures. If you own a stock, you will receive dividends, which are the payments that firms make to shareholders from the firms’ profits. Therefore stock prices should reflect the present value of the dividends that investors expect to receive from owning the stock. (We discuss present value and the relationship between interest rates and stock and bond prices in Macroeconomics, Chapter 6, Appendix, in Economics, Chapter 8, Appendix, and, more completely, in Money, Banking, and the Financial System, Chapter 3, Section 3.2 and Chapter 6, Section 6.2.)

The Wall Street Journal article we quoted above notes that the rising interest rate on the 10-year Treasury note was causing price declines in tech stocks in particular. The explanation is that tech firms often go through an initial period in which they may make very low profits or even suffer losses. Investors may still be willing to buy stock in tech firms because they expect the firms eventually to increase their profits and the dividends they pay. But because those profits will be earned in the future—often after a period of losses that may stretch for years—the present value of the profits and, therefore, the price of the stock depends more on the interest rate than would be true of a firm making breakfast cereal or frozen pizza that will be steadily earning profits through the years. Therefore, we would expect, as the article indicates, that the prices of tech firms are more likely to decline—or to decline more—when interest rates rise than is true of other firms. 

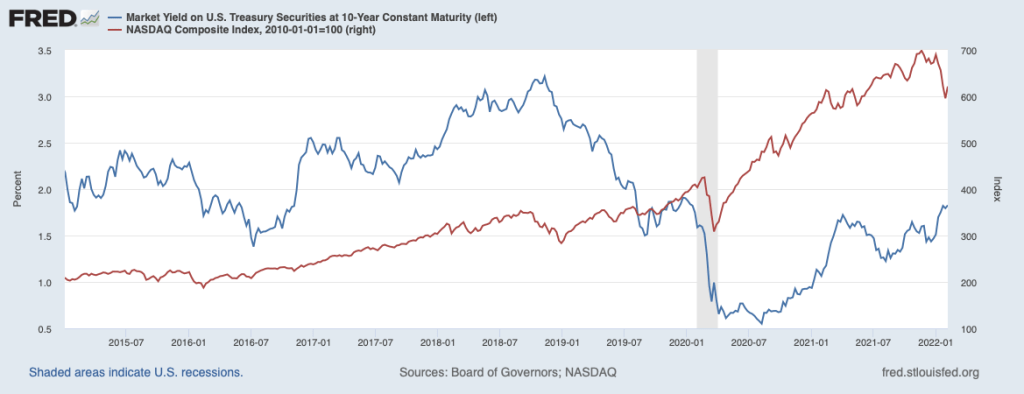
The following figure shows the interest rate on the 10-year Treasury note (blue line with scale given on the left) and the values of the Nasdaq composite stock index (red line with the value for January 1, 2010 set equal to 100 and the scale given on the right). The Nasdaq includes the stocks of more tech firms than is true of the other widely followed stock market indexes—the S&P 500 and the Dow Jones Industrial Average. The figure shows that the declining interest rate on 10-year Treasury notes that began in late 2018 and continued through mid-2020 coincided with increases in the prices of the stocks in the Nasdaq index—apart from the spring of 2020 during the beginning of the Covid-19 pandemic.  The most recent period shows that increases in the interest rate on the 10-year Treasury note have corresponded with a decline in the Nasdaq, as noted in the article.

Source: Sam Goldfarb, “Elevated Bond Yields Approach Key Milestone,” Wall Street Journal, February 7, 2022; U.S. Bureau of Economic Analysis, “Prices, Costs, and Profit per Unit of Real Gross Value Added of Nonfinancial Domestic Corporate Business,” January 27, 2022; and Federal Reserve Bank of St. Louis.