
Image created by ChatGPT
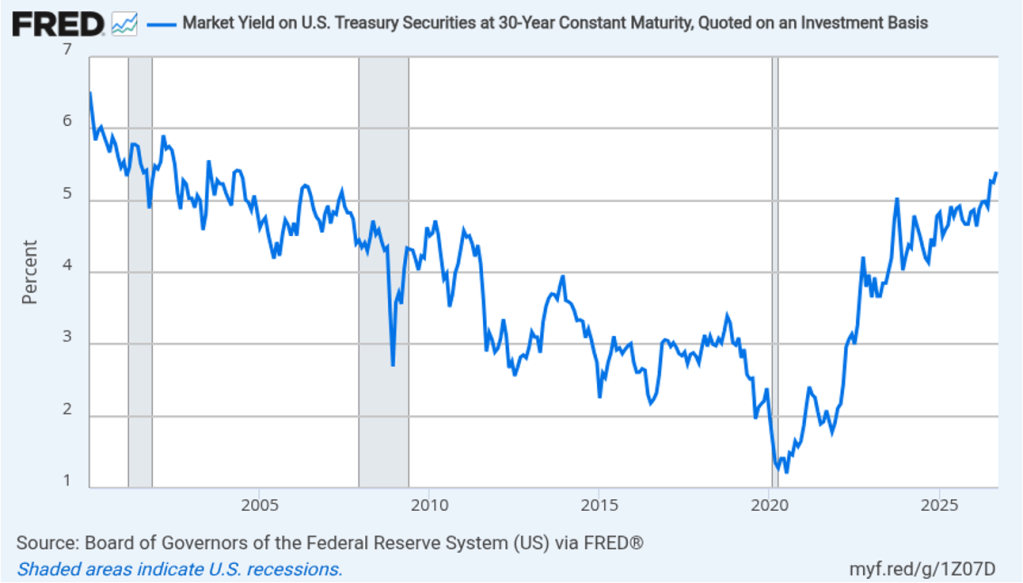
As the following figure show, as of yesterday, the yield on the 30-year U.S. Treasury bond is the highest it’s been since 2004, before the Global Financial Crisis.
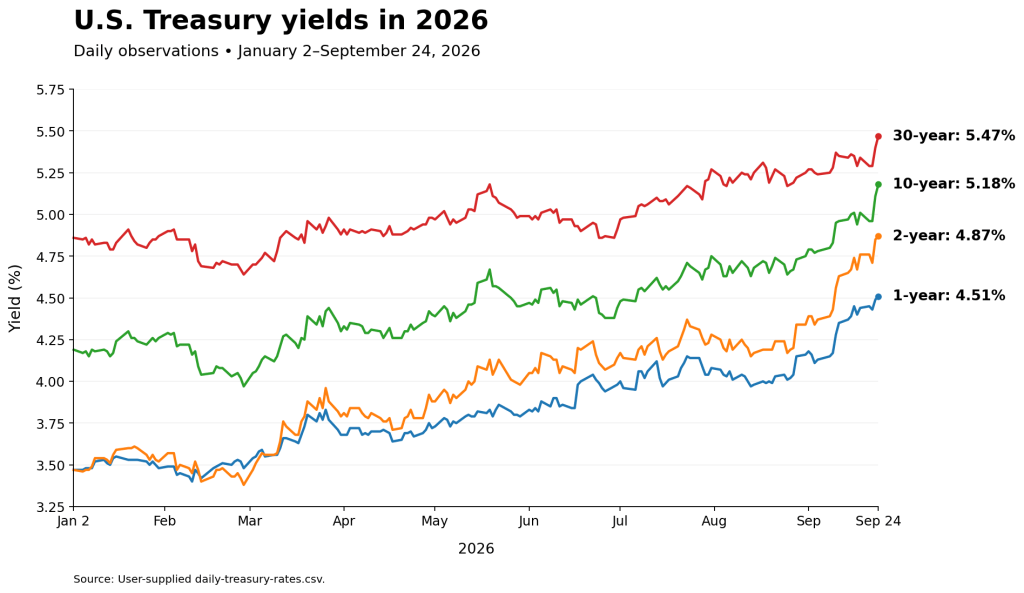
The following figure (created by ChatGPT using data from this Treasury website) shows that Treasury bonds at all maturities have risen this year. Recall that the maturity of a bond is the amount of time until the seller of the bond repays the principal to the buyer of the bond. Formally, a Treasury security with a maturity of 1 year or less is a Treasury bill, a Treasury security with with a maturity of 2 years to 10 years is a Treasury note, and a Treasury security with of more than 10 years is a Treasury bond. For simplicity, in this post we’ll usually refer to all Treasury securities as bonds. We’ll refer interchangeably to the interest rate on a bond and the yield on the bond. Formally, the relevant interest rate in this post is the yield to maturity. (We discuss the bond market in Money, Banking, and the Financial System, Chapters 3-5. A new edition is available now.)
Rising yields on Treasury securities have a substantial effect on the economy. On most days, nearly all of the buying and selling in the Treasury bond market is of existing bonds that the U.S. Treasury may have issued decades earlier. Because the federal government has been running large budget deficits, the Treasury has to issue billions of new Treasury bonds each year. Investors will only buy newly issued Treasury bonds if their yields are competitive with the yields on existing bonds. As a result, interest payments have been a rising fraction of total federal spending, which contributes to the federal budget deficit.
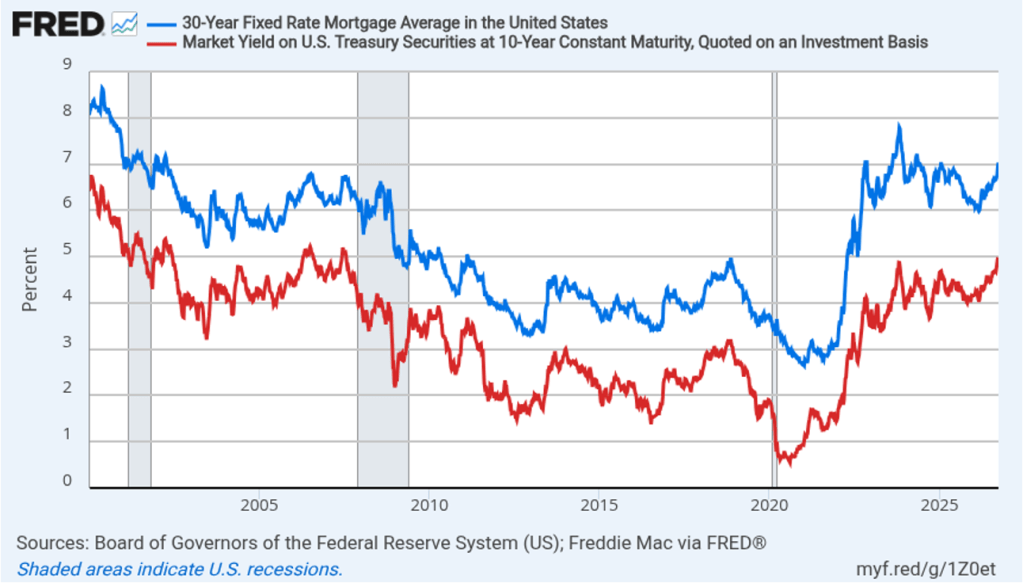
Firms that grant mortgage loans typically adjust the interest rates they charge as the yield on the 10-year Treasury changes. The difference between the interest rate on mortgages and the interest rate on the 10-year Treasury is called the mortgage spread. The following figure shows the close relationship between movements in the mortgage interest rate (the blue line) and movements in the interest rate on 10-year Treasurys (the red line). The recent increase in the yields on 10-year Treasurys has caused an increase in the mortgage interest rate.
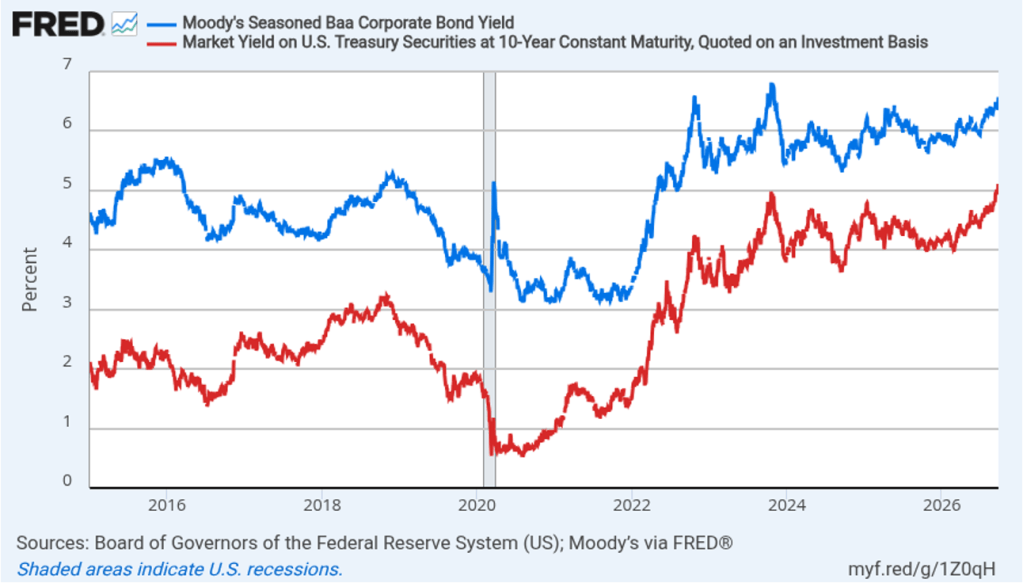
Many investors hold both Treasury bonds and bonds issued by corporations. If the yields on Treasury bonds rise, to attract investors the yields on corporate bonds also have to rise. The following figure shows that there is a close relationship between the yield on 10-year Treasurys and the yield on corporate bonds. The interest rate on corporate bonds is higher than the interest rate on Treasurys for two key reasons: First, corporate bonds have a higher default risk, which is the risk that a bond issuer will fail to make payments of interest or principal. Second., corporate bonds are less liquid than Treasurys, which means that because the market for Treasurys is much larger than the market for any corporate bond, an investor can more easily sell a Treasury bond. Investors need to be compensated with a higher interest rate on corporate bonds for the greater default risk and lower liquidity of these bonds.
What’s caused the increases in interest rates? Several factors are involved. First, in part because of rising oil prices resulting from conflict in the Middle East, since the middle of 2026 there has been an increase in the inflation rate that investors in bond markets expect to prevail over the next few years. Inflation reduces the purchasing power of the payments investors receive from owning a bond. The Fisher effect refers to the argument by Irving Fisher, who was an economist at Yale University, that the nominal interest rate on a bond will rise point-for-point with changes in the expected inflation rate. (Recall from Macroeconomics, Chapter 9 (Economics, Chapter 19) that the nominal interest rate is the stated interest rate on a bond. We can approximate the real interest rate by subtracting the expected inflation rate from the nominal interest rate.) The following figure from Chapter 4 of Money, Banking, and the Financial System, illustrates the Fisher effect.
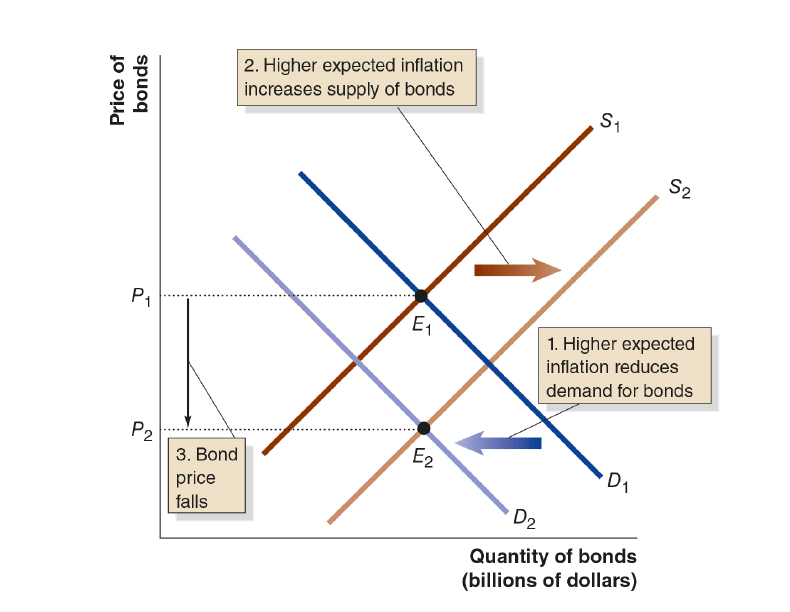
A higher expected inflation rate increases the quantity of bonds supplied at any given bond price because inflation reduces the real value of the payments that bond issuers have to make. In the figure, the supply curve for bonds shifts to the right from S1 to S2. A higher expected inflation rate decreases the quantity of bonds demand at any given bond price because inflation reduces the real value of the payments that bond buyers receive. The demand curve for bonds shift to the left from D1 to D2. Note that because the equilibrium price of bonds declines from P1 to P2, the interest rate—which moves inversely with the price—increases. In practice, economists have found that various real-world frictions result in nominal interest rates not always increasing or decreasing by exactly the amount of a change in expected inflation. But the basic point holds that changes in the expected inflation rate lead to changes in the interest rates on bonds.
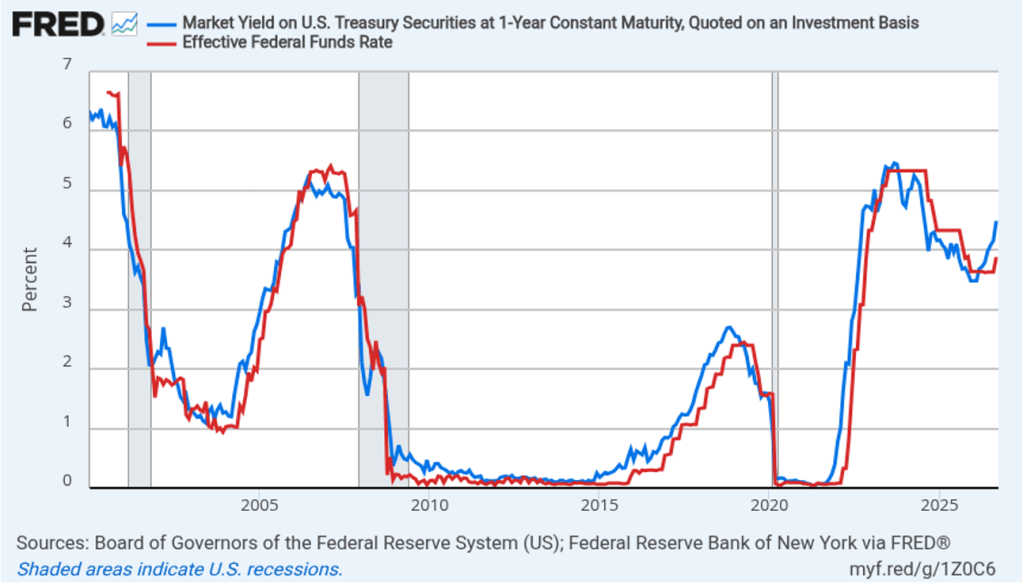
The second reason that interest rates have been rising is related to the first reason. As we discuss in this blog post, because the inflation rate has been running persistently higher than the Federal Reserve’s 2 percent annual target, at its September meeting the Fed’s Federal Open Market Committee (FOMC) raised its target for the federal funds rate. Investors in the federal funds futures market expect that the committee will raise its federal funds rate target further in coming meetings. The following figure shows that the interest rate on 1-year Treasury bills tracks closely movements in the federal funds rate.
Changes in expected future short-term interest rates, such as the expected interest rate on the 1-year Treasury bill one year from now, can affect longer-term interest rates. For example, someone who wants to invest in Treasurys for two years could either buy a 2-year Treasury or buy a 1-year Treasury today and another 1-year Treasury in a year. We would expect that buying and selling in the bond market would make the return from these two ways of investing equal—a process called arbitrage. If investors expect that the FOMC will raise its target for the federal funds rate in the future, the expected interest on the 1-year Treasury bill a year from now will increase, which will also increase the interest rate today on a 2-year Treasury. The same process will also cause interest rates on longer-maturity bonds to increase.
Third, the supply of bonds has been increasing rapidly. As we’ve seen, high federal government budget deficits will cause the Treasury to issue close to $2 trillion in bonds this year. In addition, technology firms, such as as Meta, Alphabet (the parent company of Google), Amazon, and Oracle, have been increasing their bond sales to obtain the funds to build out the infrastructure, such as data centers, necessary to power the AI build out. According to data from the Securities Industry and Financial Markets Association, through August of 2026, corporate bond issuance was nearly 30 percent greater than in 2025.
(Note that most other high income countries, including Japan, Canada, and the countries of Western Europe, have also been running large government budget deficits and issuing large quantities of bonds. Because investors can buy and sell bonds across countries, higher interest rates in one country can put upward pressure on interest rates in other countries.)
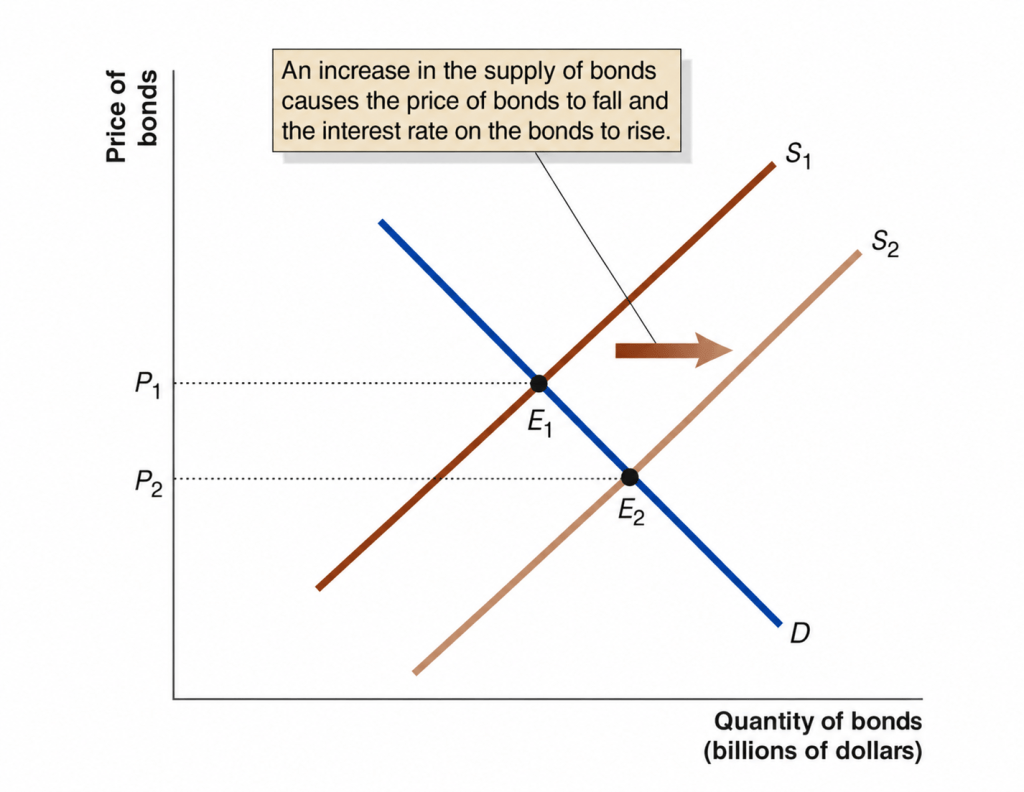
As the following figure shows, an increase in the supply of bonds, holding other factors that can affect the demand or supply of bonds constant, causes the price of bonds to fall and, therefore, the interest rate on bonds to rise.
Following the Global Financial Crisis of 2007–2009, low inflation rates and a federal funds rate close to zero resulted in low interest rates on most bonds. For example, the 10-year Treasury note was below 4 percent—and typically below 3 percent—from late 2008 to late 2022. Some economists believed that interest rates would remain low for the foreseeable future. But the sharp increase in inflation rates that began in the spring of 2021, following the Covid pandemic, continuing high federal budget deficits, and tech firms demand for funds to build data centers and other AI infrastructure has led to the highest interest rates in more than 20 years. Whether these high interest rates will persist depends primarily on future inflation rates and future federal budget deficits.

