New BEA Data Releases Show Higher Growth and Lower Inflation than Expected

Image created by ChatGPT

The Bureau of Economic Analysis (BEA) released two reports this morning (September 30). One report indicated that economic growth was higher in the second quarter of 2026 than the BEA had previously estimated. The other report indicated that inflation as measured by the percentage increase in personal consumption expenditures (PCE) price index was lower than expected.

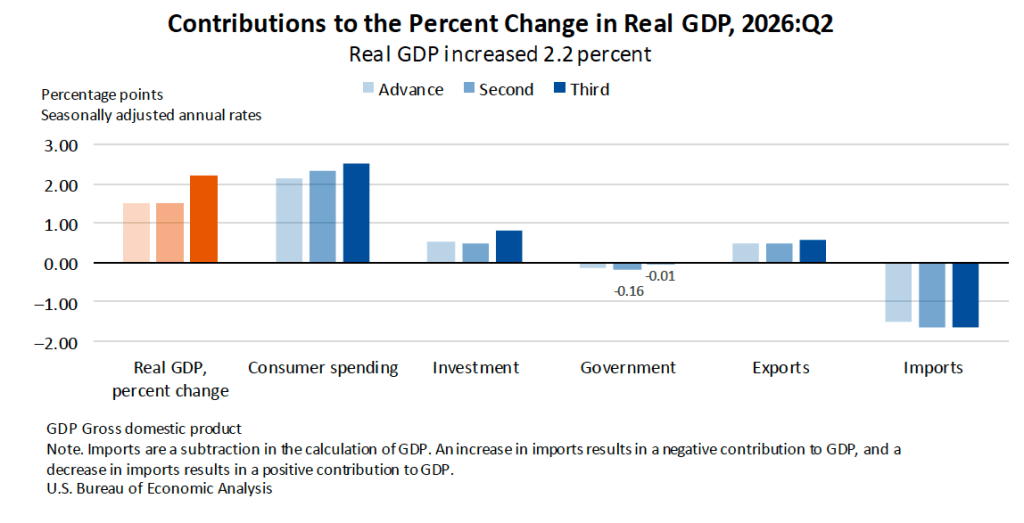
The BEA’s latest estimate is that real GDP increased at an annual rate of 2.2 percent in the second quarter (May, June, and July) of 2026. That is a sharp upward revision of the BEA’s previous estimate that real GDP had increased at an annual rate of 1.5 percent in the second quarter. The following figure from the report shows that upward revisions of investment, consumer spending, and government spending account for the upward revision of real GDP growth. The figure shows the BEA’s advance (original estimate) and two subsequent revised estimates. The BEA revises its estimates of real GDP growth as over time as it collects more complete and accurate data on growth in the components of GDP.
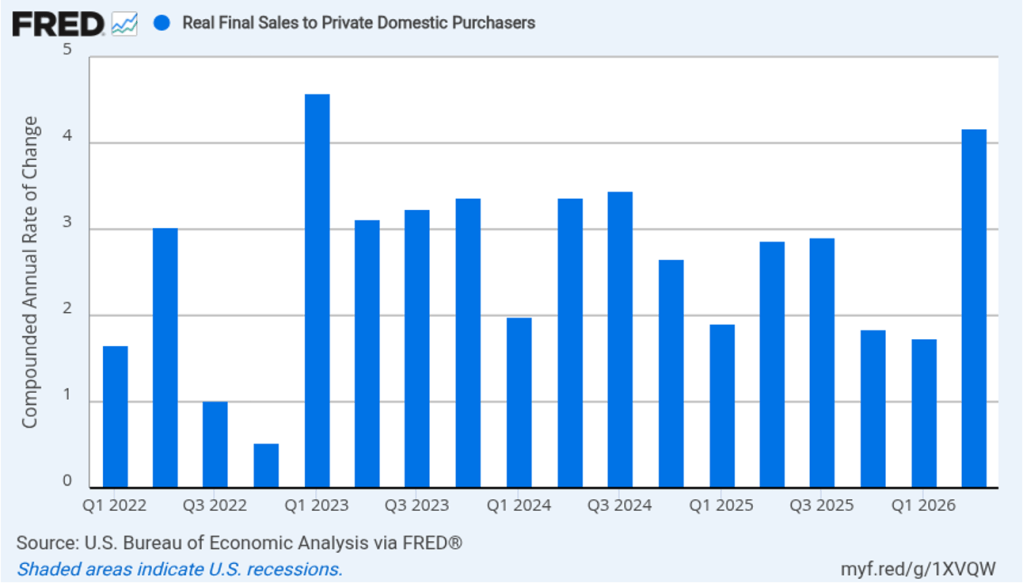
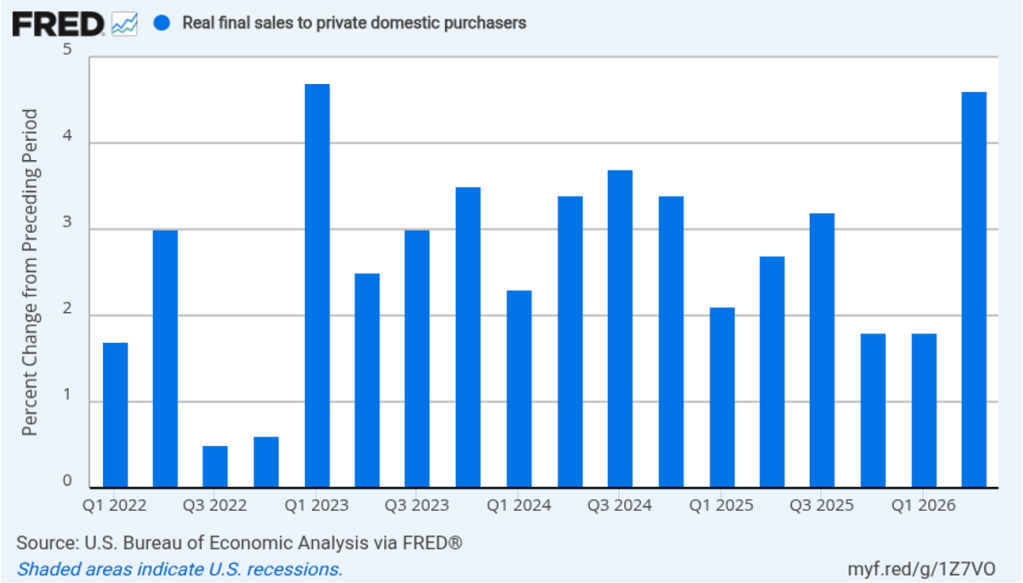
As we’ve discussed in previous blog posts, to better gauge the state of the economy, Federal Reserve policymakers often prefer to strip out the effects of imports, inventory investment, and government expenditures—which can be volatile—by looking at real final sales to private domestic purchasers, which includes only spending by U.S. households and firms on domestic production. As the following figure shows, real final sales to domestic purchasers increased at an annual rate of 4.6 percent in the second quarter, revised upward from 4.4 percent. The growth rate in real final sales to domestic purchasers was more than twice the growth rate of real GDP, as well as much higher than the U.S. economy’s expected long-run annual real growth rate of 1.8 percent. So estimated growth in real final sales to domestic purchasers indicates that the U.S. economy is expanding more rapidly than is indicated by estimated growth in real GDP. Typically, growth in real final sales to domestic purchasers is steadier than growth in real GDP and is likely a better indicator of the underlying growth rate in the economy.
The BEA’s “Personal Income and Outlays” report this morning included monthly data on the personal consumption expenditures (PCE) price index. The Fed relies on annual changes in the PCE price index to evaluate whether it’s meeting its 2 percent annual inflation target. As we noted in an earlier blog post, Fed Chair Kevin Warsh indicated in his press conference following the July meeting of the Federal Open Market Committee (FOMC) that the committee intended to continue using the PCE price index as its gauge of inflation, although that decision would be revisited early next year. Some analysts have interpreted Warsh’s statement that the decision would be revisited next year as an indication that he favored moving to a measure that would show lower rates of inflation than those shown by the PCE.

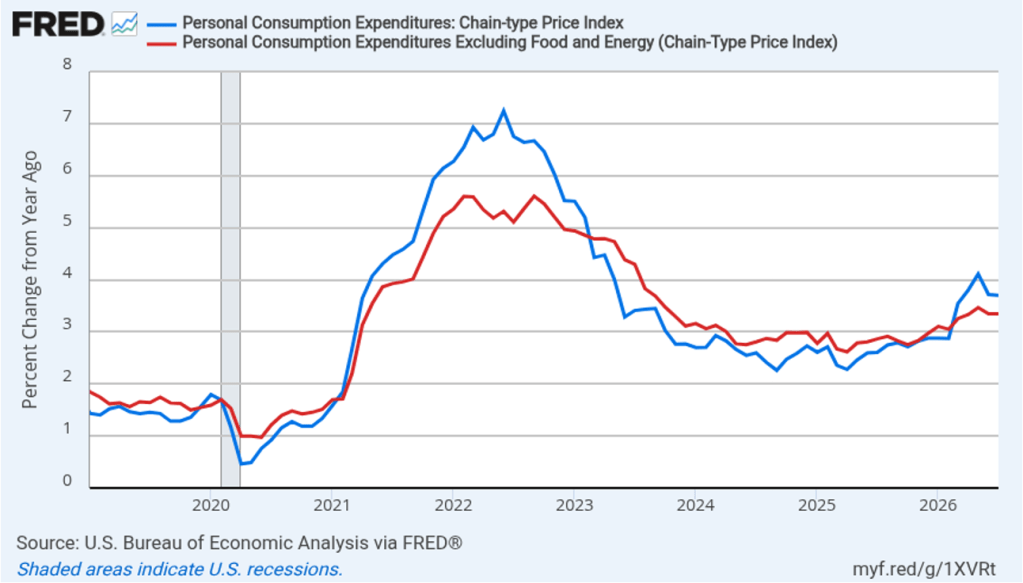
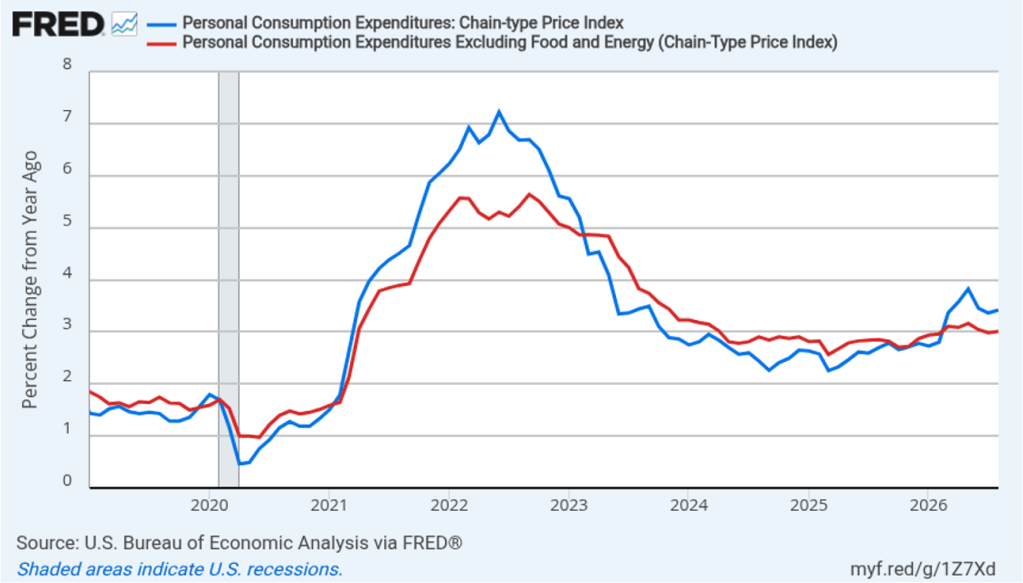
The following figure shows headline PCE inflation (the blue line) and core PCE inflation (the red line)—which excludes energy and food prices—for the period since January 2019, with inflation measured as the percentage change in the PCE from the same month in the previous year. In August, headline PCE inflation was 3.4 percent, unchanged from July. Core PCE inflation in August was 3.0 percent, also unchanged from July. Headline and core PCE inflation were both lower than forecast by economists surveyed by FactSet. Both headline PCE inflation and core PCE inflation remain well above the Fed’s 2 percent annual inflation target.
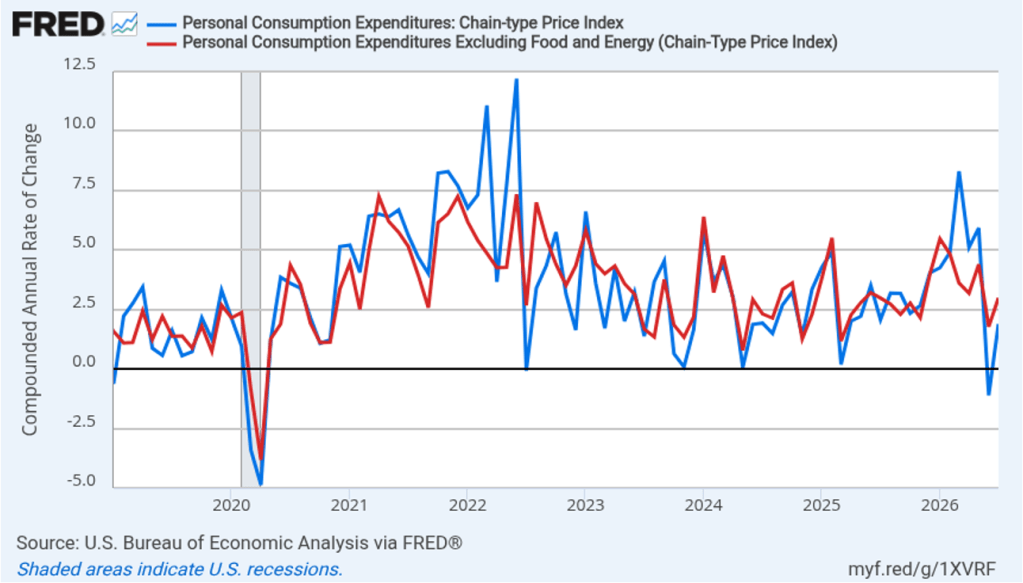
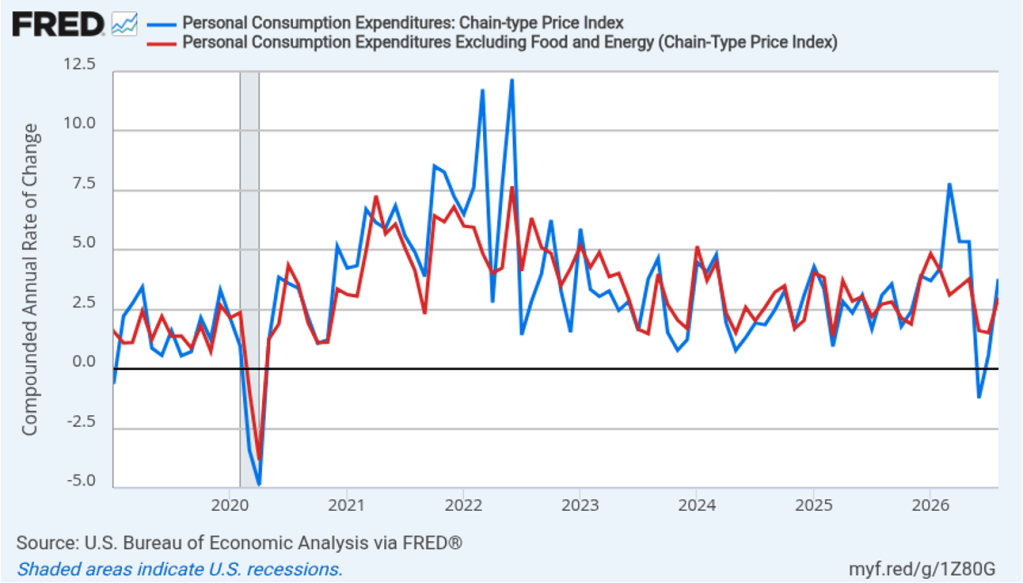
The following figure shows headline PCE inflation and core PCE inflation calculated by compounding the current month’s rate over an entire year. (Often referred to as 1-month inflation.) Measured this way, headline PCE inflation increased from 0.6 in July to 3.8 percent in August. Core PCE inflation increased from 1.5 percent in July to 3.0 percent in August. In contrast with the 12-month inflation rates, the 1-month inflation rates show noticeable acceleration in inflation during August. Of course, it’s important not to overinterpret the data from a single month.
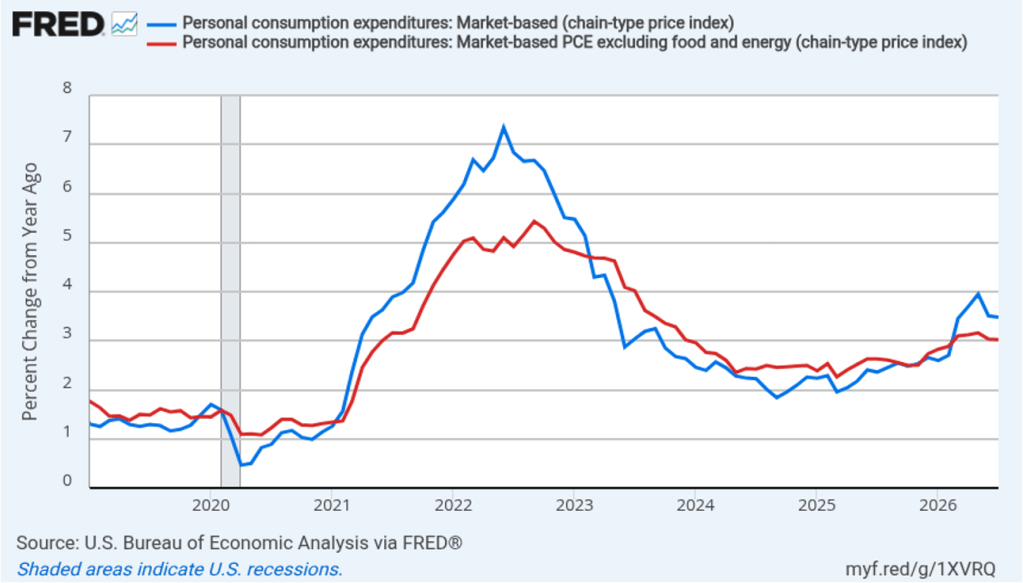
Fed policymakers believe that inflation in non-market services can skew PCE inflation. Non-market services are services whose prices the BEA imputes rather than measures directly. For instance, the BEA assumes that prices of financial services—such as brokerage fees—vary with the prices of financial assets. So that if stock prices rise, the prices of financial services included in the PCE price index also rise. Former Fed Chair Jerome Powell has argued that these imputed prices “don’t really tell us much about … tightness in the economy. They don’t really reflect that.” The following figure shows 12-month headline inflation (the blue line) and 12-month core inflation (the red line) for market-based PCE. (The BEA explains the market-based PCE measure here.)
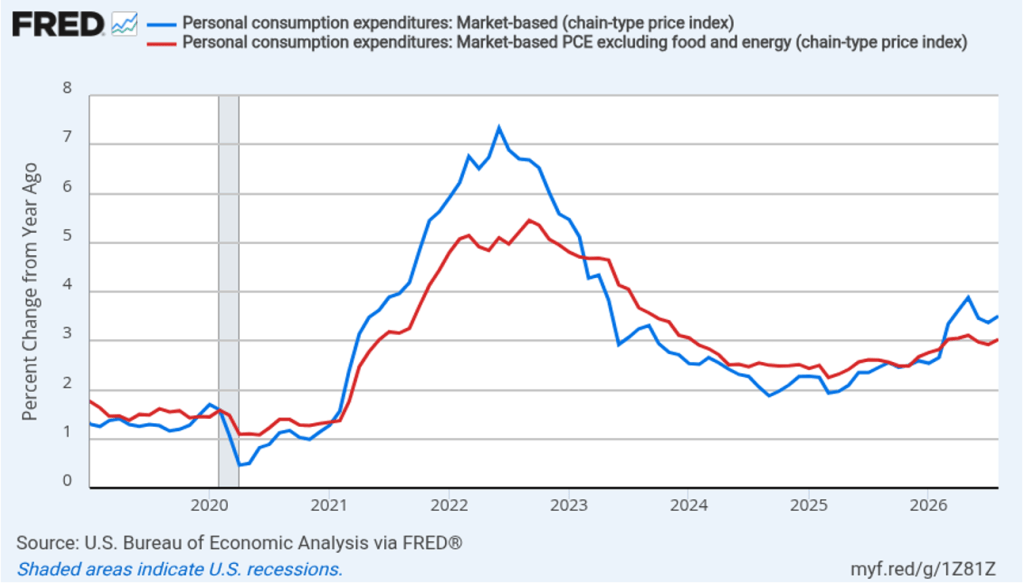
Headline market-based PCE inflation was 3.5 percent in August, up slightly from 3.4 percent July. Core market-based PCE inflation was 3.0 percent in August, up from 2.9 percent in July. So, both market-based measures show inflation in August remaining well above the Fed’s 2 percent target.

Fed Chair Kevin Warsh argued in testimony at his confirmation hearing before the Senate that the Fed should stop relying on headline PCE inflation: “The measures [of inflation] I prefer are looking at things that are called trimmed averages. We take out all of the tail-risks, all of the one-off items, and we ask ourselves whether the generalized change in prices is having second-order effects on the economy.” 

Trimmed-mean PCE inflation drops the 31 percent of goods and services with the highest inflation rates and the 24 percent of goods and services with the lowest inflation rates. A closely related measure, median PCE inflation, is calculated by listing the inflation rate in each individual good or service included in the PCE and identifying the inflation rate of the good or service that is in the middle of the list—that is, the inflation rate in the price of the good or service that has an equal number of higher and lower inflation rates. 

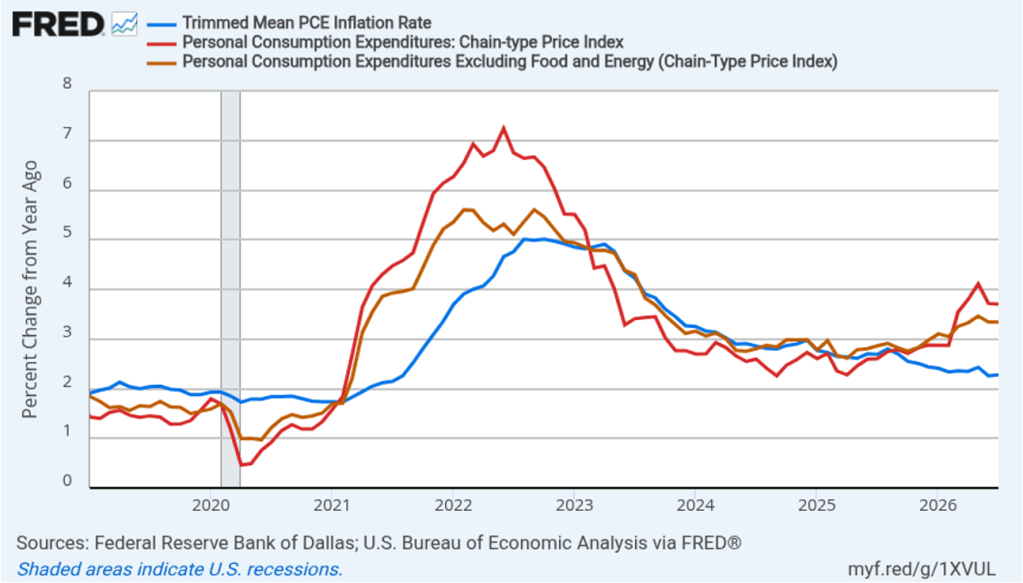
The following figure shows 12-month headline PCE inflation the (blue line), core PCE inflation (the red line) and trimmed-mean PCE inflation (the green line). Trimmed-mean PCE inflation in August was 2.2 percent, well below both headline and core PCE inflation.

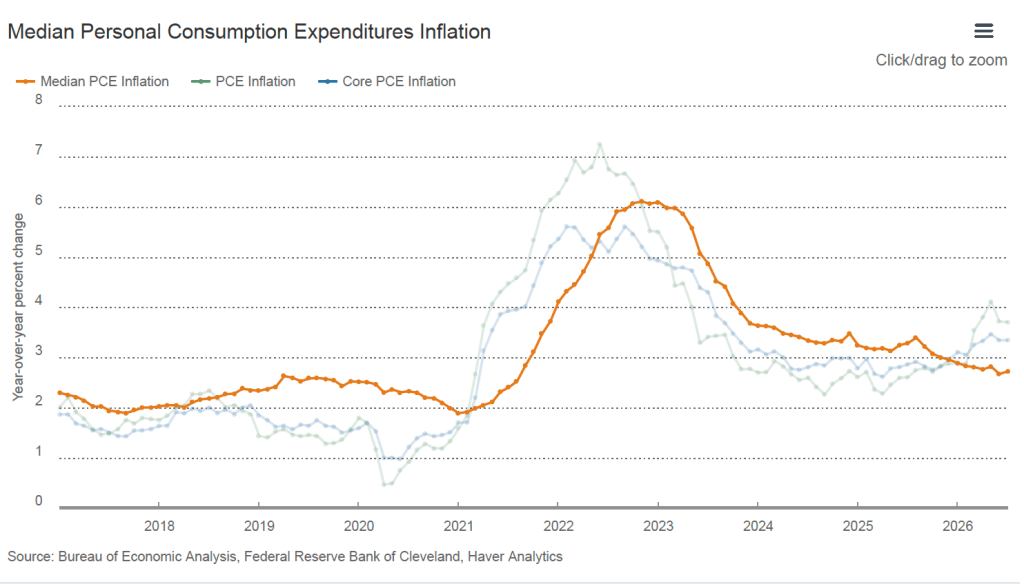
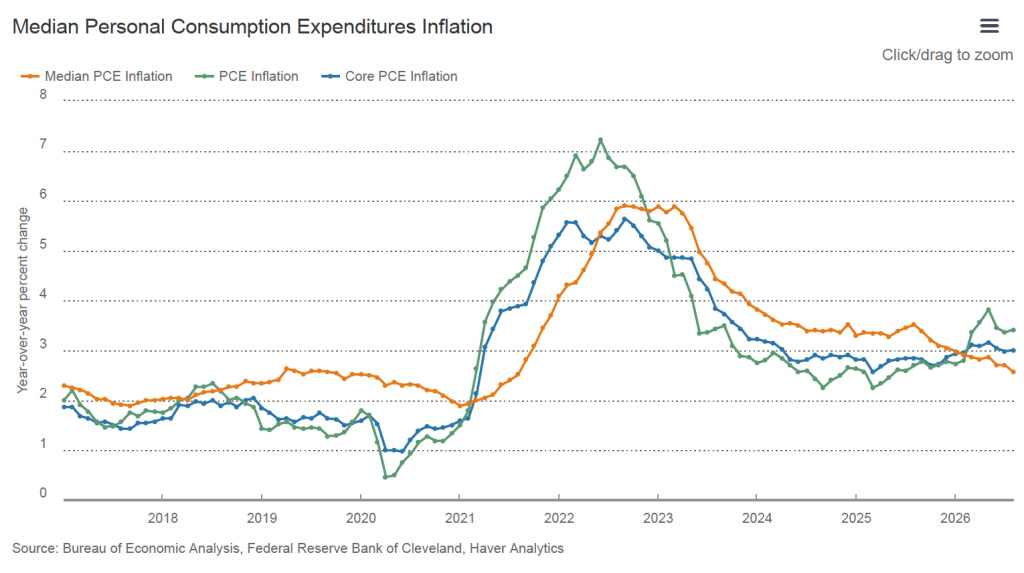
The following figure from the website of the Federal Reserve Bank of Cleveland shows headline PCE inflation (the green line), core PCE inflation (the blue line), and median PCE inflation (the brown line). In August, median PCE inflation was 2.6 percent, which was down from 2.7 percent in July. So Warsh has a point that these two measures of inflation, which are less affected by particularly high or low rates of inflation in some goods and services, indicate that inflation has been running below the Fed’s currently preferred measure. But these measures also show inflation still running well above the Fed’s 2 percent annual inflation target.
Today’s macro data releases appear to have caused of investors who buy and sell federal funds futures contracts to believe that the Federal Open Market Committee (FOMC) is now less likely to raise its target for the federal funds rate at the committee’s next meeting on October 27–28. Trading on the federal funds futures market this afternoon implies that the probability of a target rate increase at that meeting is 39.3 percent, down from a probability of 50.9 percent yesterday.
What’s Going on in the Bond Market?

Image created by ChatGPT

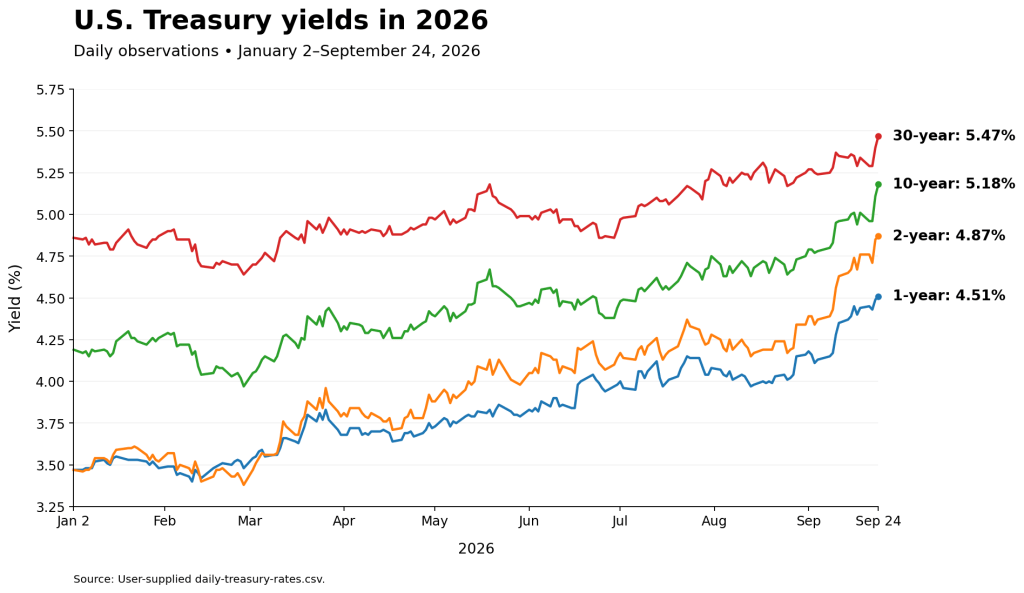
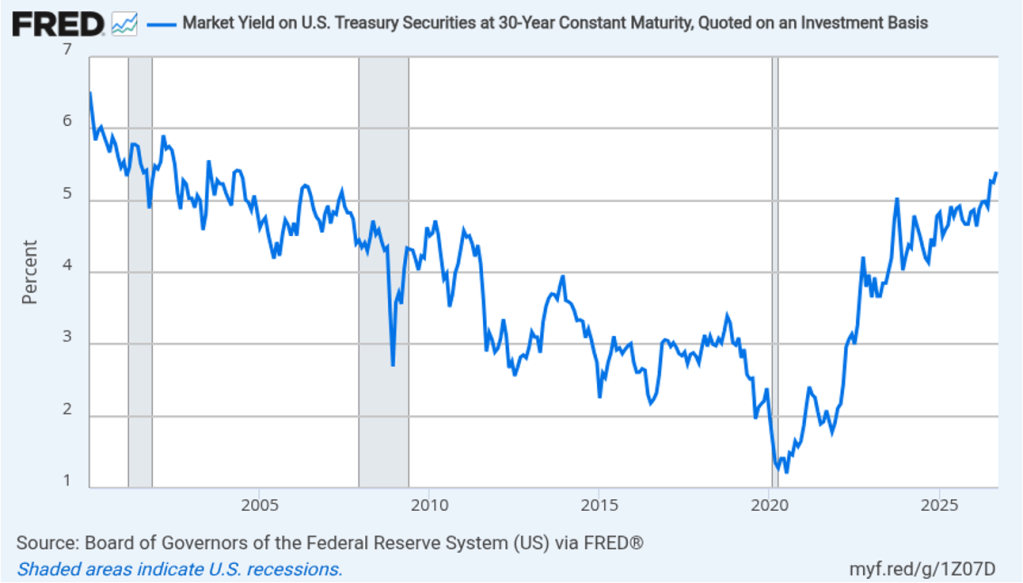
As the following figure show, as of yesterday, the yield on the 30-year U.S. Treasury bond is the highest it’s been since 2004, before the Global Financial Crisis.

The following figure (created by ChatGPT using data from this Treasury website) shows that Treasury bonds at all maturities have risen this year. Recall that the maturity of a bond is the amount of time until the seller of the bond repays the principal to the buyer of the bond. Formally, a Treasury security with a maturity of 1 year or less is a Treasury bill, a Treasury security with with a maturity of 2 years to 10 years is a Treasury note, and a Treasury security with of more than 10 years is a Treasury bond. For simplicity, in this post we’ll usually refer to all Treasury securities as bonds. We’ll refer interchangeably to the interest rate on a bond and the yield on the bond. Formally, the relevant interest rate in this post is the yield to maturity. (We discuss the bond market in Money, Banking, and the Financial System, Chapters 3-5. A new edition is available now.)

Rising yields on Treasury securities have a substantial effect on the economy. On most days, nearly all of the buying and selling in the Treasury bond market is of existing bonds that the U.S. Treasury may have issued decades earlier. Because the federal government has been running large budget deficits, the Treasury has to issue billions of new Treasury bonds each year. Investors will only buy newly issued Treasury bonds if their yields are competitive with the yields on existing bonds. As a result, interest payments have been a rising fraction of total federal spending, which contributes to the federal budget deficit.

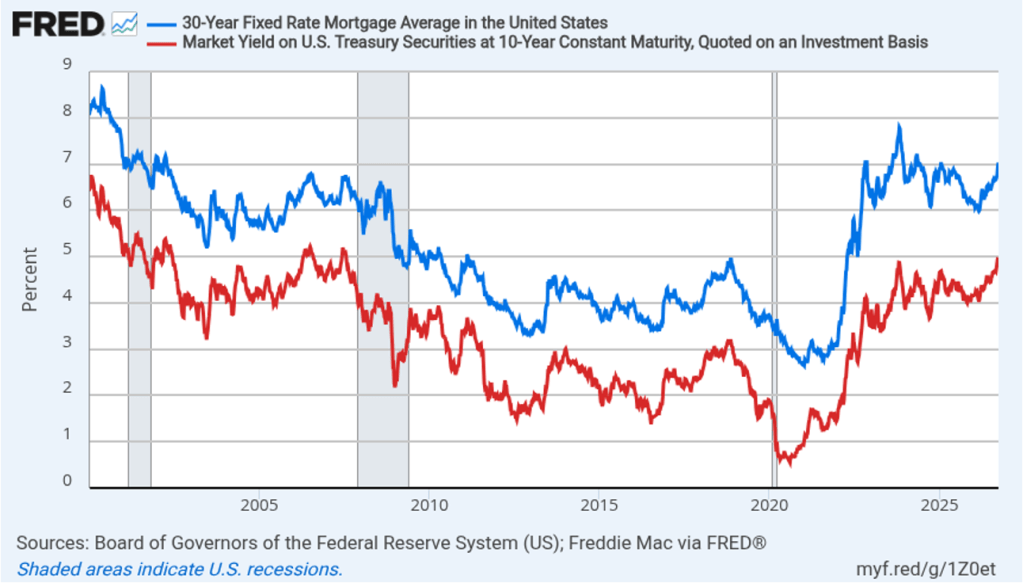
Firms that grant mortgage loans typically adjust the interest rates they charge as the yield on the 10-year Treasury changes. The difference between the interest rate on mortgages and the interest rate on the 10-year Treasury is called the mortgage spread. The following figure shows the close relationship between movements in the mortgage interest rate (the blue line) and movements in the interest rate on 10-year Treasurys (the red line). The recent increase in the yields on 10-year Treasurys has caused an increase in the mortgage interest rate.

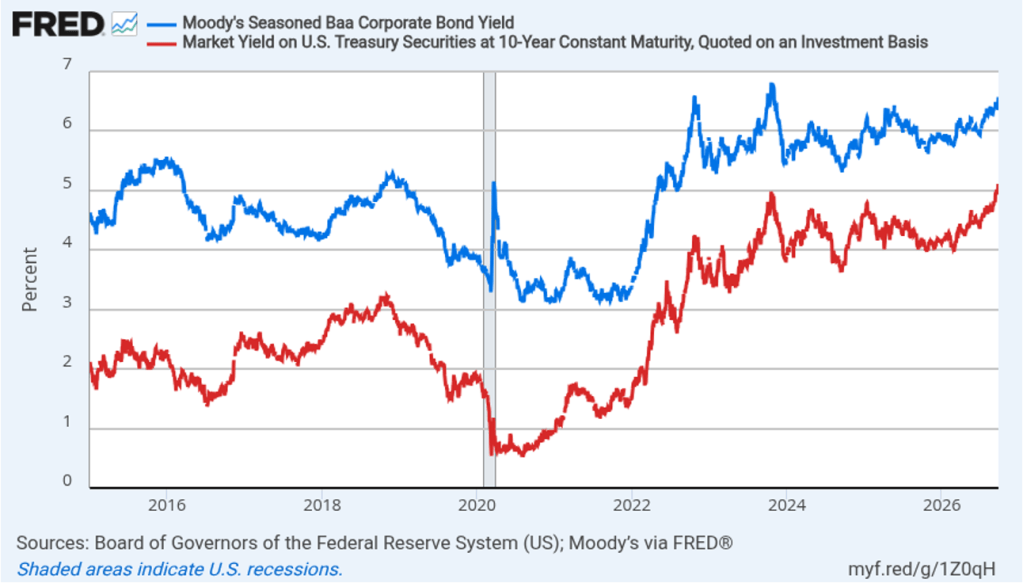
Many investors hold both Treasury bonds and bonds issued by corporations. If the yields on Treasury bonds rise, to attract investors the yields on corporate bonds also have to rise. The following figure shows that there is a close relationship between the yield on 10-year Treasurys and the yield on corporate bonds. The interest rate on corporate bonds is higher than the interest rate on Treasurys for two key reasons: First, corporate bonds have a higher default risk, which is the risk that a bond issuer will fail to make payments of interest or principal. Second., corporate bonds are less liquid than Treasurys, which means that because the market for Treasurys is much larger than the market for any corporate bond, an investor can more easily sell a Treasury bond. Investors need to be compensated with a higher interest rate on corporate bonds for the greater default risk and lower liquidity of these bonds.

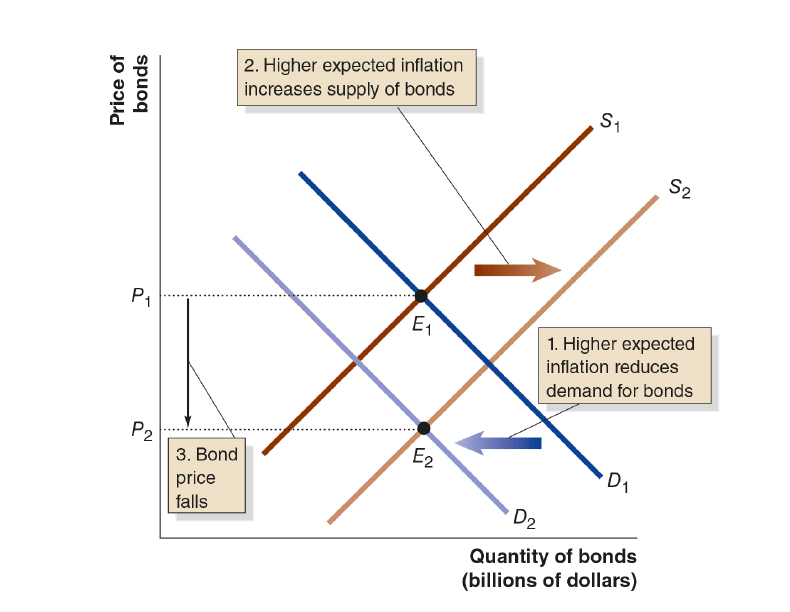
What’s caused the increases in interest rates? Several factors are involved. First, in part because of rising oil prices resulting from conflict in the Middle East, since the middle of 2026 there has been an increase in the inflation rate that investors in bond markets expect to prevail over the next few years. Inflation reduces the purchasing power of the payments investors receive from owning a bond. The Fisher effect refers to the argument by Irving Fisher, who was an economist at Yale University, that the nominal interest rate on a bond will rise point-for-point with changes in the expected inflation rate. (Recall from Macroeconomics, Chapter 9 (Economics, Chapter 19) that the nominal interest rate is the stated interest rate on a bond. We can approximate the real interest rate by subtracting the expected inflation rate from the nominal interest rate.) The following figure from Chapter 4 of Money, Banking, and the Financial System, illustrates the Fisher effect.

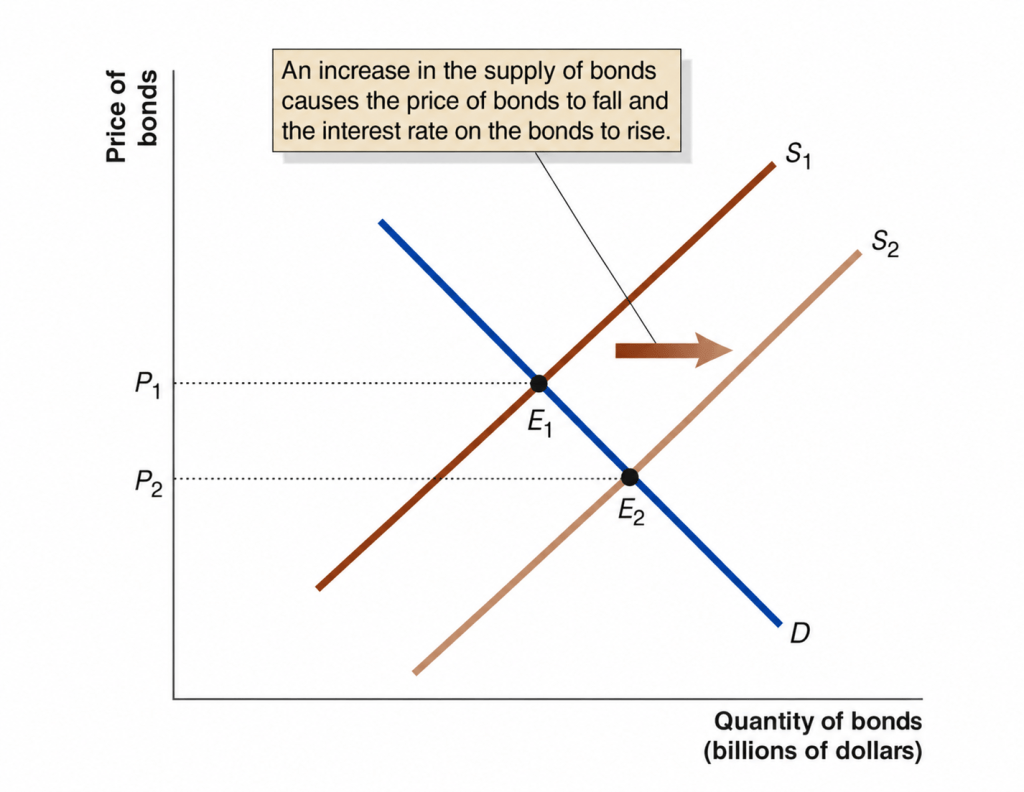
A higher expected inflation rate increases the quantity of bonds supplied at any given bond price because inflation reduces the real value of the payments that bond issuers have to make. In the figure, the supply curve for bonds shifts to the right from S1 to S2. A higher expected inflation rate decreases the quantity of bonds demand at any given bond price because inflation reduces the real value of the payments that bond buyers receive. The demand curve for bonds shift to the left from D1 to D2. Note that because the equilibrium price of bonds declines from P1 to P2, the interest rate—which moves inversely with the price—increases. In practice, economists have found that various real-world frictions result in nominal interest rates not always increasing or decreasing by exactly the amount of a change in expected inflation. But the basic point holds that changes in the expected inflation rate lead to changes in the interest rates on bonds.

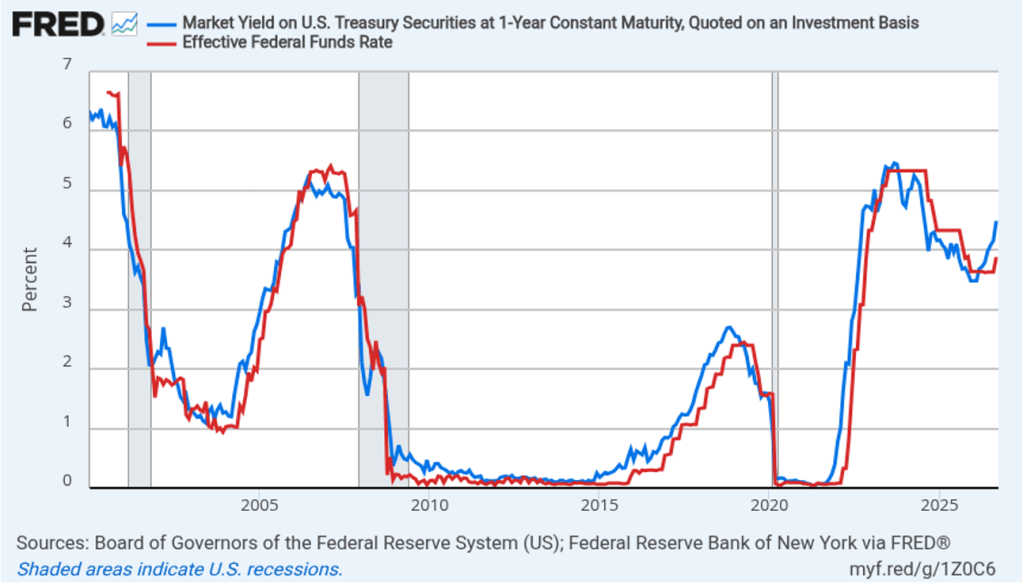
The second reason that interest rates have been rising is related to the first reason. As we discuss in this blog post, because the inflation rate has been running persistently higher than the Federal Reserve’s 2 percent annual target, at its September meeting the Fed’s Federal Open Market Committee (FOMC) raised its target for the federal funds rate. Investors in the federal funds futures market expect that the committee will raise its federal funds rate target further in coming meetings. The following figure shows that the interest rate on 1-year Treasury bills tracks closely movements in the federal funds rate.

Changes in expected future short-term interest rates, such as the expected interest rate on the 1-year Treasury bill one year from now, can affect longer-term interest rates. For example, someone who wants to invest in Treasurys for two years could either buy a 2-year Treasury or buy a 1-year Treasury today and another 1-year Treasury in a year. We would expect that buying and selling in the bond market would make the return from these two ways of investing equal—a process called arbitrage. If investors expect that the FOMC will raise its target for the federal funds rate in the future, the expected interest on the 1-year Treasury bill a year from now will increase, which will also increase the interest rate today on a 2-year Treasury. The same process will also cause interest rates on longer-maturity bonds to increase.

Third, the supply of bonds has been increasing rapidly. As we’ve seen, high federal government budget deficits will cause the Treasury to issue close to $2 trillion in bonds this year. In addition, technology firms, such as as Meta, Alphabet (the parent company of Google), Amazon, and Oracle, have been increasing their bond sales to obtain the funds to build out the infrastructure, such as data centers, necessary to power the AI build out. According to data from the Securities Industry and Financial Markets Association, through August of 2026, corporate bond issuance was nearly 30 percent greater than in 2025.

(Note that most other high income countries, including Japan, Canada, and the countries of Western Europe, have also been running large government budget deficits and issuing large quantities of bonds. Because investors can buy and sell bonds across countries, higher interest rates in one country can put upward pressure on interest rates in other countries.)

As the following figure shows, an increase in the supply of bonds, holding other factors that can affect the demand or supply of bonds constant, causes the price of bonds to fall and, therefore, the interest rate on bonds to rise.

Following the Global Financial Crisis of 2007–2009, low inflation rates and a federal funds rate close to zero resulted in low interest rates on most bonds. For example, the 10-year Treasury note was below 4 percent—and typically below 3 percent—from late 2008 to late 2022. Some economists believed that interest rates would remain low for the foreseeable future. But the sharp increase in inflation rates that began in the spring of 2021, following the Covid pandemic, continuing high federal budget deficits, and tech firms demand for funds to build data centers and other AI infrastructure has led to the highest interest rates in more than 20 years. Whether these high interest rates will persist depends primarily on future inflation rates and future federal budget deficits.

As Expected, the FOMC Raises Its Federal Funds Rate Target

Photo from federalreserve.gov

Today, the Federal Open Market Committee (FOMC) met expectation by raising its target range for the federal funds rate by 0.25 percentage points (25 basis points) from the range of 3.50 percent to 3.75 percent that had prevailed since December 10 of last year. As of yesterday, trading in the federal funds rate futures market had implied a 93.5 percent probability of a 25 basis point increase. Financial markets had been convinced that a rate increase was coming since Fed Chair Kevin Warsh’s speech at the Federal Reserve Bank of Kansas City’s economic policy symposium in Jackson Hole, Wyoming in late August. (We discussed Warsh’s speech in this blog post.) There had been some speculation in the business press that one or more committee members would dissent from a rate increase, but the vote turned out to be unanimous. Today was the first time the committee had increased the target range since July 2023.

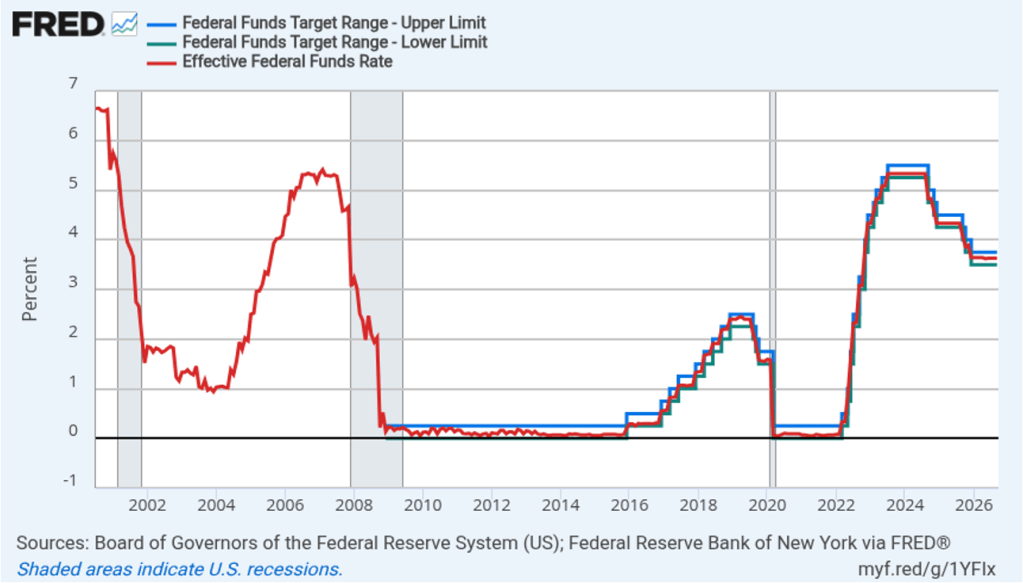
The following figure shows for the period from 2001 through yesterday, the upper bound (the blue line) and the lower bound (the green line) for the FOMC’s target range for the federal funds rate, as well as the actual values for the federal funds rate (the red line). Before December 2008, the Fed announced a single numerical target for the federal funds rate, rather than a target range. Note that the Fed has been successful in keeping the value of the federal funds rate in its target range. (We discuss the monetary policy tools the FOMC uses to maintain the federal funds rate within its target range in Macroeconomics, Chapter 15, Section 15.2 (Economics, Chapter 25, Section 25.2).)

As with the policy statements issued following Warsh’s previous two FOMC meetings, today’s policy statement was short and did not include any discussion of the circumstances under which further target rate increases might occur—so-called forward guidance. We discuss forward guidance in Macroeconomics, Chapter 15 (Economics, Chapter 25).

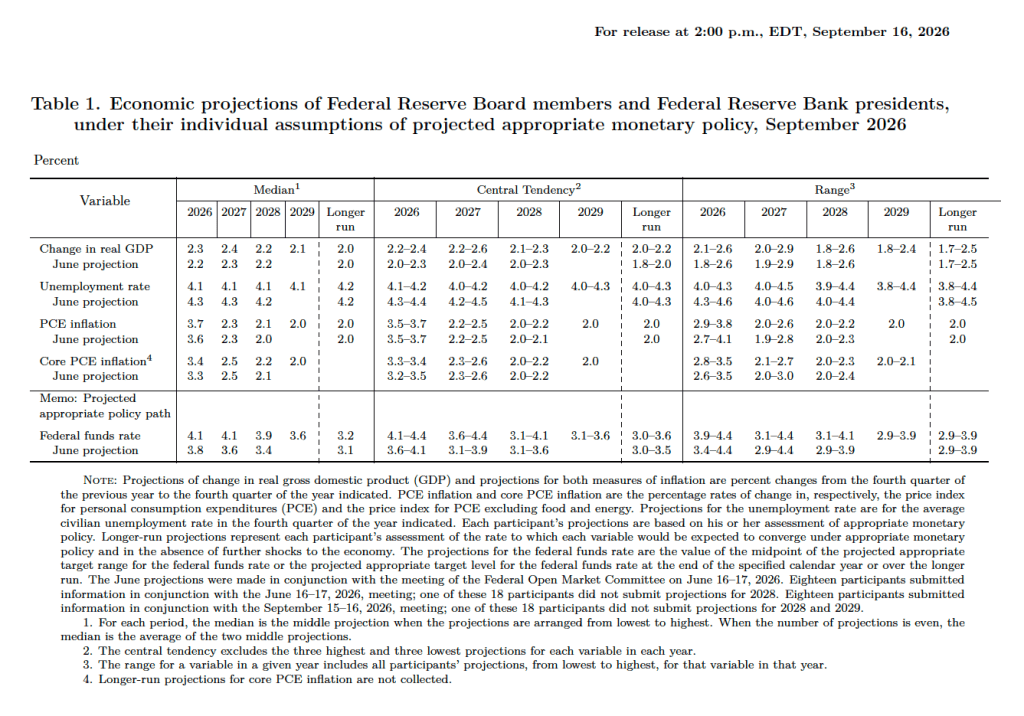
After the meeting, the committee also released a “Summary of Economic Projections” (SEP)—as it typically does at its March, June, September, and December meetings. The SEP presents median values of the, typically, 19 committee members’ forecasts of key economic variables. In a press conference following the meeting, Warsh indicated that he didn’t submit forecasts, just as he hadn’t submitted forecasts for the SEP released after the June meeting. He indicated that the future of the SEP is one of the issues to be considered by his new committee on Fed communications.

The forecasts of key economic variables from the SEP are summarized in the following table, reproduced from the release. (Note that only 5 of the district bank presidents vote at FOMC meetings, although all 12 presidents participate in the discussions and prepare forecasts for the SEP.)

There are several aspects of these forecasts worth noting:

  1. Compared with the previous SEP in June, the committee members raised their forecast of real GDP growth in 2026 slightly from 2.2 percent to 2.3 percent. The committee members left unchanged their forecast of long-run growth in real GDP at 2.0 percent. The unchanged long-range forecast indicates that the committee members are not anticipating a large, sustained increase in economic growth caused by increased use of artificial intelligence (AI). Consistent with raising their forecast of real GDP growth in 2026, the committee lowered its forecast of the unemployment rate in the fourth quarter of 2026 from 4.3 percent to 4.1 percent. The committee members left their forecast of the long-run rate of unemployment, often called the natural rate of unemployment, unchanged at 4.2 percent. 
  2. Committee members raised their forecast of personal consumption expenditures (PCE) price inflation in 2026 to 3.7 percent from 3.6 percent in June. They left their forecast of inflation in 2027 unchanged at 2.3 percent and forecast that PCE inflation would not decline to the Fed’s 2.0 percent annual target until 2029.
  3. The committee’s forecasts of the federal funds rate at the end of each year from 2026 through 2028 were increased, indicating that the committee sees the federal funds rate as likely to be “higher for longer.” The forecast for the long-run federal funds rate was raised from 3.1 percent to 3.2 percent.

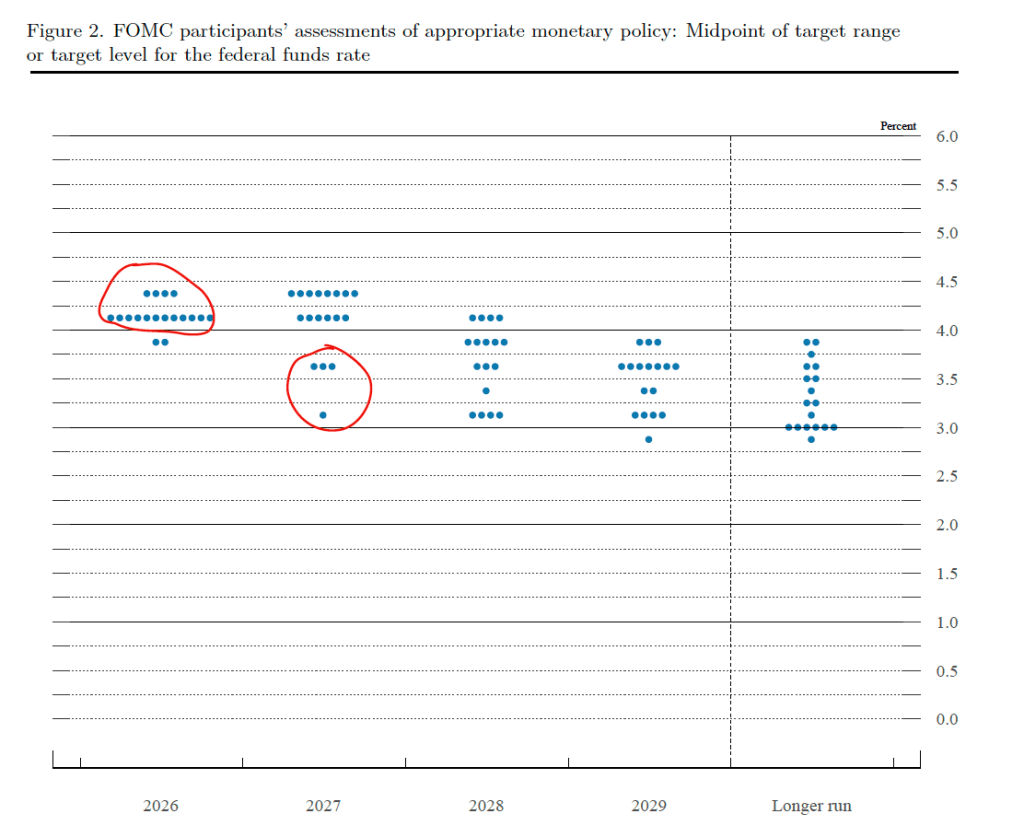
There is always much discussion in the business press and among investment analysts about the dot plot, shown below. Each dot in the plot represents the projection of an individual committee member. (The committee doesn’t disclose which member is associated with which dot.) Note that there are 18 dots, representing the 6 members of the Fed’s Board of Governors who provided forecasts and all 12 presidents of the Fed’s district banks.

The dots plotted on the far left of the figure represent the projections by the 18 members of the value of the federal funds rate at the end of 2026. The plots indicate that, at this point, 16 members of the committee (circled in red) forecast at least one additional 25 basis point increase in the target range for the federal funds rate before the end of the year, with only 2 members expecting that there will be no further increases this year. For 2027, four members (circled in red) expect that the target range will be cut during the year, with the rest expecting either that the rate increases made this year will be maintained or that there will be one additional 25 basis point increase. The dots plotted on the far right of the figure indicate that there is substantial disagreement among committee members as to what the long-run value of the federal funds rate—the so-called neutral rate—should be. Of course, the plots only represent the forecasts of the committee members and individual committee members are likely to adjust their forecasts as additional macroeconomic data become available in the coming months.

At his press conference following the meeting, Warsh resisted attempts by reporters to get him to expand on the circumstances under which the committee might implement further increases in the target range. He characterized today’s rate increase as removing “a dose of accommodation” from the economy, which reflected the committee’s belief that the economy was experiencing full employment with persistently high inflation. The closest he came to engaging in forward guidance was the statement that “We must be confident that underlying inflation is moving towards our objective. This has not been satisfied.”

Warsh was asked what had changed since the July meeting at which the committee had kept the target range unchanged. in reply, he indicated that the committee believed that since July the economy had strengthened, inflation had continued to above target, and “geopolitical” factors had contributed to higher prices.

No Sign of Cooling Inflation in September CPI Report

Image created by ChatGPT

Today’s report from the Bureau of Labor Statistics (BLS) on the consumer price index (CPI) for August was eagerly awaited by economists and policy analysts. As we discuss in Macroeconomics, Chapter 15 (Economics, Chapter 25), monetary policy affects the economy with, in the words of Nobel Laureate Milton Friedman, “long and variable lags.” As a result, most economists agree that the Federal Reserve should not attempt to “fine tune” the economy by responding to each government release of macroeconomic data.

There are some instances, however, including the present, when the Fed’s policymaking Federal Open Market Committee (FOMC) appears to be uncertain as to whether a change in policy is needed. As a result, there was a widespread expectation that if today’s report indicated that inflation is slowing, the FOMC would likely leave its target for the federal funds rate unchanged at its meeting on Tuesday and Wednesday of next week. But if the report didn’t indicate that inflation is slowing, the committee would likely raise its target. The report gave few indications that inflation is slowing.

The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).

  • The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.4 percent in August, the same as in July. 
  • The core inflation rate, which excludes the prices of food and energy, was 2.4 percent in August, down from 2.5 in July.  

Headline inflation was slightly higher, and core inflation was equal, to the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)

In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline (the blue line) was 4.6 percent In August, up from 0.9 percent in July. Core inflation (the red line) was 3.5 percent in August, up from 2.6 percent in July.

The following figure illustrates the role played by energy prices in contributing to the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had declined at an annual rate of 16.4 percent in July, increased at an annual rate of 28.3 percent in August. The blue line shows the 1-month inflation rate in gasoline prices, which had declined at an annual rate of 29.4 percent in July, increased at an annual rate of 58.3 percent in August.

There had been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and in the category “food away from home” (the red bar)—primarily food purchased at restaurants. Grocery prices, which had declined at annual rate of 0.9 percent in July, increased at an annual rate of 0.4 percent in August. Food prices away from home increased 3.1 percent in August, down from 3.9 percent in July. To this point, increases in energy prices seem to have had some effect on grocery prices and restaurant prices, although the extent of the effect is unclear.

Fed Chair Kevin Warsh has indicated that he favors measures of the inflation rate that exclude particularly small or particularly large changes in the prices of some goods or services—so-called outliers. Median CPI, which is compiled monthly by economists at the Federal Reserve Bank of Cleveland, is calculated by ranking the price changes of every good or service in the index from the largest price change to the smallest price change, and then choosing the price change in the middle. The idea is to eliminate the effect on measured inflation of any short-lived events that cause the prices of some goods and services to be particularly high or particularly low. Economists at the Cleveland Fed have conducted research that shows that, in their words, “the median CPI provides a better signal of the underlying inflation trend than either the all-items CPI or the CPI excluding food and energy. The median CPI is even better at forecasting [personal consumption expenditures] PCE inflation in the near and longer term than the core PCE price index.”

Trimmed-mean inflation, also compiled by economists at the Cleveland Fed, excludes the highest 8 percent of price changes and the lowest 8 percent. The following figure shows 1-month trimmed mean (the blue line) and median (the red line) CPI inflation. Trimmed-mean inflation was 2.7 percent in August, unchanged from July. Median inflation was 2.1 percent in August, down from 3.1 percent in July. So these measures of inflation are both lower than the conventional headline and core CPI inflation measures, although as the figure shows, both measures are volatile.

Note that the Fed uses the 12-month change in the personal consumption expenditures (PCE) price index, not the change in the CPI, when gauging whether it is hitting its 2 percent annual inflation target. Historically, PCE inflation has been about 0.4 percentage points to 0.5 percentage points lower than CPI inflation. The Bureau of Economic Analysis (BEA) won’t release its estimate of August PCE inflation until September 30, after the next FOMC meeting.

Today’s report showing that inflation remains persistently above the Fed’s 2 percent annual target, following last week’s jobs report showing an unexpectedly large increase in employment, has likely raised the chance that Federal Reserve policymakers will increase their target range for the federal funds rate from the current 3.50 percent to 3.75 percent by o.25 percentage points (or 25 basis points) at the next meeting of the FOMC on September 15–16. Trading in the federal funds futures market this afternoon indicates that investors assign a 86.5 percent probability to the FOMC raising its target range at that meeting, which is up from a 72.4 probability yesterday. Trading indicated that investors assign a 74.5 percent probability to the committee increasing its target range by at least 50 basis points by the end of the year, up from 64.6 percent yesterday and from 44.7 percent one week ago.

Unexpectedly Strong August Jobs Report

Image created by ChatGPT

This morning (September 4), the Bureau of Labor Statistics (BLS) released its “Employment Situation” report (often called the “jobs report”) for August. The report showed an unexpectedly large increase in employment.

The jobs report has two estimates of the change in employment during the month: one estimate from the establishment survey, often referred to as the payroll survey, and one from the household survey. As we discuss in Macroeconomics, Chapter 9, Section 9.1 (Economics, Chapter 19, Section 19.1), many economists and Federal Reserve policymakers believe that employment data from the establishment survey provide a more accurate indicator of the state of the labor market than do the household survey’s employment and unemployment data. (The groups included in the employment estimates from the two surveys are somewhat different, as we discuss in this post.) 

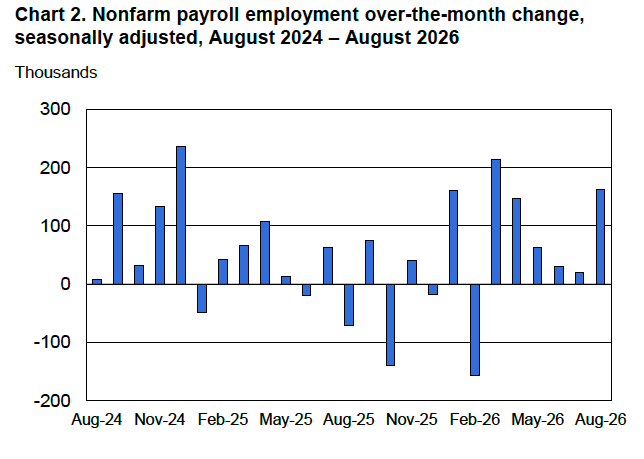
According to the establishment survey, there was a net increase of 162,000 nonfarm jobs during August.  Economists surveyed by the Wall Street Journal had forecast an increase of only 55,000 jobs.  Economists surveyed by FactSet had forecast a net increase of 65,000 jobs. The BLS revised upward its previous estimates of employment in June and July by a combined 55,000 jobs. The estimate of the net employment change in July was revised from a decrease of 23,000 to an increase of 21,000. (The BLS notes that: “Monthly revisions result from additional reports received from businesses and government agencies since the last published estimates and from the recalculation of seasonal factors.”)

The following figure from the jobs report shows the net change in nonfarm payroll employment for each month in the last two years. The figure shows that since peaking in March with a net increase of 214,000 jobs, job growth slowed markedly over the following four months until strongly rebounding in August. In 2026, monthly net employment growth has averaged 80,375. That is much higher than the 2025 average monthly employment growth of only 9,667, but well below the 2024 average monthly employment growth of 121,583.

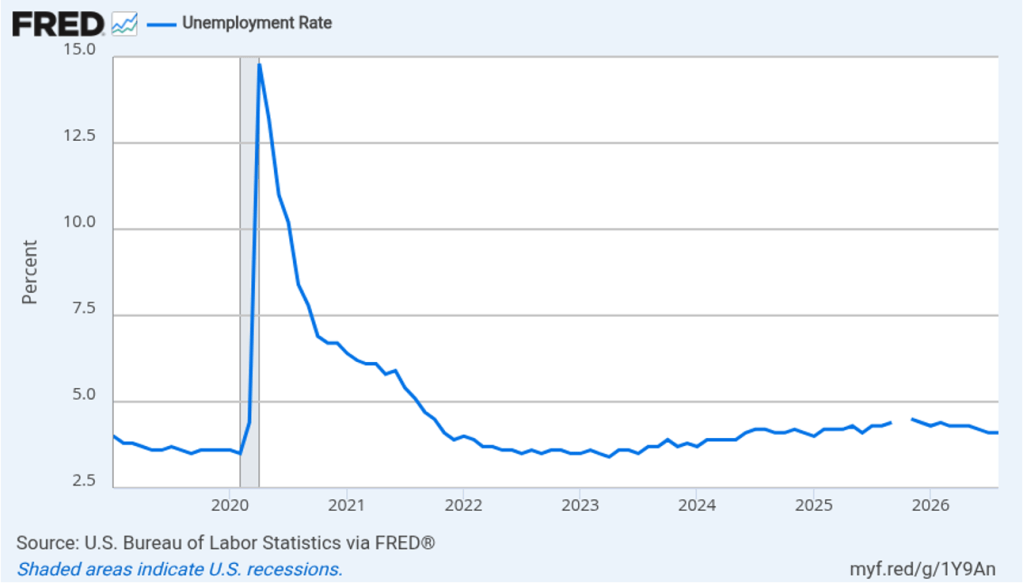
The unemployment rate, which is calculated from data in the household survey, was 4.1 percent, unchanged from July. The estimated size of the labor force, the number of workers employed, and the number of workers unemployed all increased in August. The following figure shows that the unemployment rate has been remarkably stable over the past year and a half, staying between 4.0 percent and 4.4 percent in each month since June 2024. The Federal Open Market Committee’s most recent estimate of the natural rate of unemployment—the normal rate of unemployment over the long run—is 4.2 percent. So, currently the unemployment rate is slightly below that estimate of the natural rate. (We discuss the natural rate of unemployment in Macroeconomics, Chapter 9 and Economics, Chapter 19.)

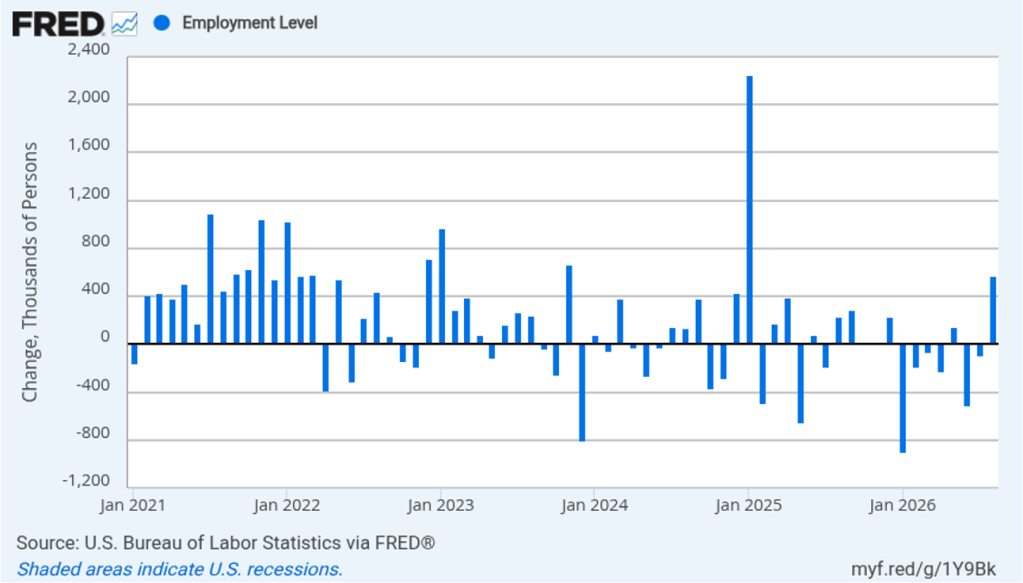
As the following figure shows, the monthly net change in jobs from the household survey moves much more erratically than does the net change in jobs from the establishment survey. As measured by the household survey, there was a net increase of 569,000 jobs in August, far larger than the net increase in employment shown in the establishment survey. Since January, the household survey has shown a net increase in jobs in only two months, with a total net decrease of 326,000 jobs over the period. In contrast, the establishment survey has shown a net increase of 643,000 jobs over the same period. (Note that because of last year’s shutdown of the federal government, there are no data for October or November.)

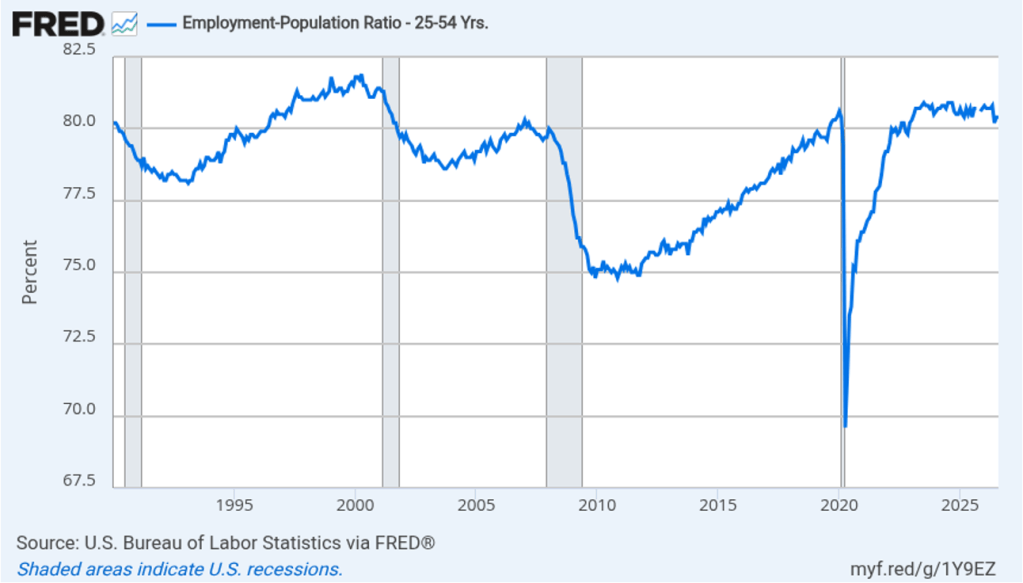
The household survey has another important labor market indicator: the employment-population ratio for prime age workers—those workers aged 25 to 54. In August, the ratio was 80.4 percent, unchanged from July. The prime-age population ratio can show volatility from month to month but has remained above 80 percent every month since December 2022.

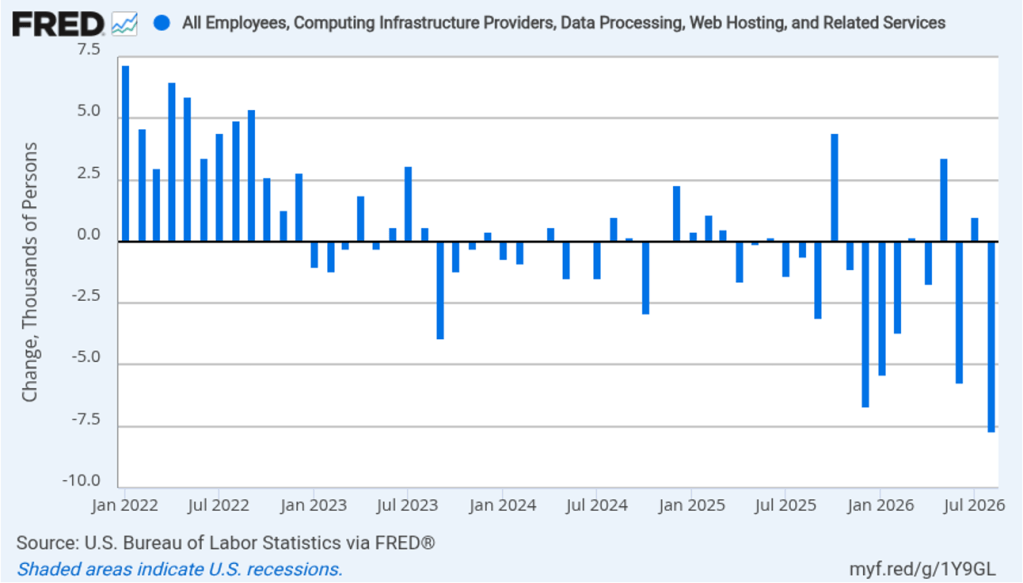
The rapid adoption of artificial intelligence (AI) by many firms has led to forecasts of substantial layoffs of workers in information systems. The following figure shows net employment changes in the BLS employment category of “computing infrastructure providers, data processing, web hosting, and related services.” Employment in this sector has been declining during most months since the beginning of 2023. In August, there was a net decrease of 7,700 jobs.

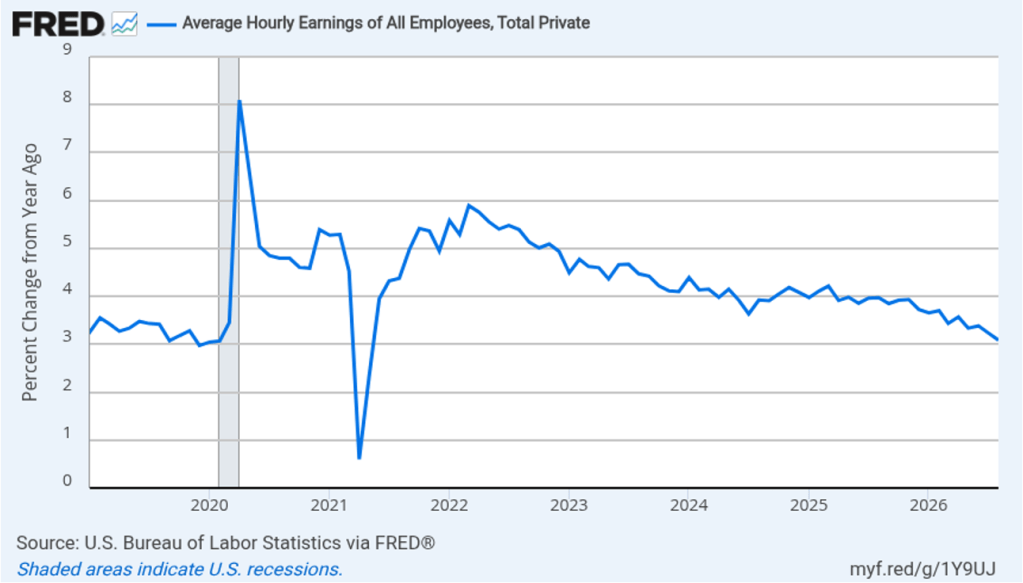
The establishment survey also includes data on average hourly earnings (AHE). As we noted in earlier posts, many economists and policymakers believe the employment cost index (ECI) is a better measure of wage pressures in the economy than is AHE. AHE does have the important advantage of being available monthly, whereas the ECI is only available quarterly. The following figure shows the percentage change in AHE from the same month in the previous year. AHE increased 3.1 percent in August, down from 3.2 percent in July. That was the smallest increase since May 2021. The rate of increase in AHE has been below 4.0 percent each month since August 2025, indicating that cost pressure from wage increases has not been a significant source of price inflation during the past year.

With inflation having been above the Federal Reserve’s 2 percent annual target every month since March 2021, there has been an expectation that the Fed’s policymaking Federal Open Market Committee (FOMC) would increase its target for the federal funds rate at least once before the end of 2026. At the FOMC’s last meeting in late July, three members of the committee voted to increase the target, an unusual amount of dissent from a committee decision. 

Do today’s surprisingly strong employment data increase the chance that the FOMC will raise its target range for the federal funds rate at its next meeting on September 15–16? Investors in the federal funds futures market believe that the answer is “yes.” Yesterday, trading in the federal funds futures market indicated that investors assigned a 49.4 percent probability to the committee increasing its target range by 0.25 percentage points (25 basis points) at that meeting. This afternoon, that probability had increased to 58.4 percent. The probability that the committee will have increased its target range by at least 25 basis points from its current range of 3.50 percent to 3.75 percent after its meeting on October 27–28 increased from 62.8 percent yesterday to 69.4 percent this afternoon.

The BLS will release its estimate of inflation as measured by the consumer price index next Friday. That report will provide further evidence on the current state of inflation and may have a significant effect on the decision the FOMC makes at its meeting the following week.

Fed Chair Warsh Takes a More Hawkish Stand in Address at Jackson Hole

Federal Reserve Chair Kevin Warsh (Photo from federalreserve.com)

Each year since 1982, the Federal Reserve Bank of Kansas City has sponsored an economic policy symposium in Jackson Hole, Wyoming. (The site was supposedly first chosen in the hopes that Fed Chair Paul Volcker would attend because of the opportunities for fly fishing in the local area.)

In most years since 1989, the Fed chair has given the keynote address at the symposium. The address gives the Fed chair a chance to provide his or her assessment of the state of the U.S. economy and the outlook for inflation and employment—the two parts of the dual mandate Congress has given to the Fed.

Image created by ChatGPT

This year’s address by Fed Chair Kevin Warsh was highly anticipated. In his press conference following the last meeting of the Fed’s policymaking Federal Open Market Committee (FOMC), Warsh reiterated his determination to bring inflation back to the Fed’s 2 percent annual target. But he faced a number of questions from reporters as to why, with inflation running well above 2 percent, he wasn’t advocating an increase in the FOMC’s target for the federal funds rate. Warsh has stated that he wantesto steer the committee from using forward guidance to affect interest rates. Accordingly he was reluctant to state explicitly what direction Fed policy might take.

Investors in the bond market appear to have interpreted Warsh’s statements as “dovish”; that is, they believed that his reluctance to support rate increases indicated that inflation might remain above the Fed’s target for longer. As we discussed in earlier blog posts, when investors believe that inflation will be higher they require that bond yields rise enough to compensate them for the additional purchasing power. (As we discuss in Money, Banking, and the Financial System, Chapter 4, economists refer to the increase in nominal interest rates following an increase in the expected inflation rate as the Fisher effect.) The rise in the yield on the 30-year Treasury bond in the days following Warsh’s press conference likely reflected bond investors expecting somewhat higher inflation than they had previously.

In today’s address, Warsh attempted to counter the conclusion that he is reluctant to increase interest rates to slow the rate of inflation. First, though, he repeated his opposition to Fed chairs routinely engaging in forward guidance: “Oversharing policy deliberations and overcommitting to future decisions can lead markets, businesses, and households astray. And I believe when policymakers make quasi-commitments on interest rates through the cycle, we inhibit our own freedom to make the right calls when it’s time to decide.”

He again stated forcefully his commitment to the Fed’s inflation target: “The Fed’s price-stability objective of 2 percent, as measured by the personal consumption expenditures (PCE) price index, is a firm, fixed target. … It is the Fed’s job to deliver stable prices.” He noted that all measures of inflation “tell a similar story: Inflation is running above our 2 percent target. So the Fed’s predominant focus right now should be on prices.”

Warsh also observed that “progress over the past two years [toward the 2 percent target] has been modest.” He concluded that: “There is one signal nobody can miss: The responsibility for 65 months of sustained, elevated inflation sits squarely with the central bank. And that is where it belongs.”

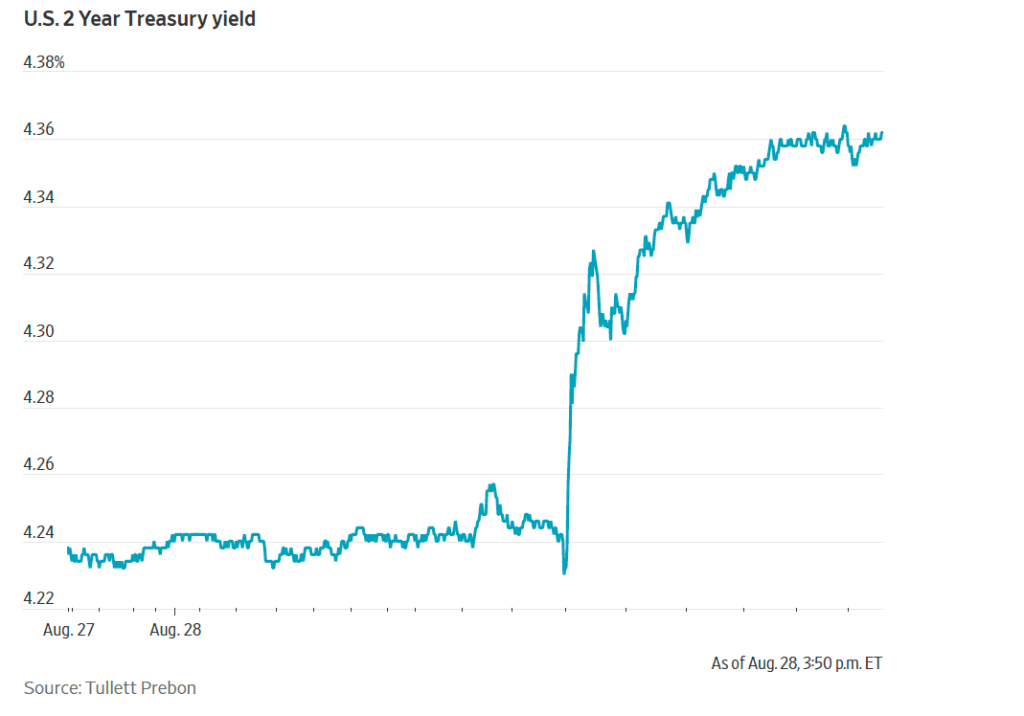
The following figure from the Wall Street Journal reflects the bond market’s immediate reaction when the text of Warsh’s address was released.

The two-year Treasury note is directly affected by investors’ expectations of the future path of the federal funds rate. (We discuss this link in Money, Banking, and the Financial System, Chapter 5.) Investors interpreted Warsh’s address as indicating he would take a more “hawkish” view of the need to raise the FOMC’s target for the federal funds rate than he had appeared to take in his earlier press conference.

Investors in the federal funds future market also quickly revised their expectations of the likelihood of the FOMC raising its target for the federal funds rate. Trading in the futures marker resulted in the probability increasing from 35.4 percent yesterday to 57.5 percent this afternoon of the committee raising its target range for the federal funds by 0.25 percentage points (25 basis points) at its next meeting on September 15–16. The probability that after the meeting on October 27–28, the committee will have raised its target range by at least 25 basis points increased from 52.6 percent yesterday to 70.7 percent this afternoon.

New BEA Releases Show Steady Inflation and Higher Output Growth

Image created by ChatGPT

The Bureau of Economic Analysis (BEA) released two reports this morning (August 26): “GDP (Second Estimate) and Corporate Profits, 2nd Quarter 2026” and “Personal Income and Outlays, July 2026.” The BEA’s second estimate is that real GDP grew at annual rate of 1.5 percent in second quarter of 2026, which is unchanged from the BEA’s initial estimate released last month and is equal to the forecast of economists surveyed by the Wall Street Journal. 

As we’ve discussed in previous blog posts, to better gauge the state of the economy, Federal Reserve policymakers often prefer to strip out the effects of imports, inventory investment, and government expenditures—which can be volatile—by looking at real final sales to private domestic purchasers, which includes only spending by U.S. households and firms on domestic production. As the following figure shows, real final sales to domestic purchasers increased at an annual rate of 4.2 percent in the second quarter, up from 3.9 percent in last month’s initial estimate. The growth rate in real final sales to domestic purchasers was more than twice the rate of growth of real GDP, as well as far above the U.S. economy’s expected long-run annual real growth rate of 1.8 percent. So growth in real final sales to domestic purchasers indicates that the U.S. economy is expanding rapidly, as opposed to the much weaker growth shown by real GDP data. Typically, growth in real final sales to domestic purchasers is steadier than growth in real GDP and is likely a better indicator of the underlying growth rate in the economy.

The BEA’s “Personal Income and Outlays” report this morning included monthly data on the personal consumption expenditures (PCE) price index. The Fed relies on annual changes in the PCE price index to evaluate whether it’s meeting its 2 percent annual inflation target. As we noted in a recent blog post, Fed Chair Kevin Warsh indicated in his press conference following the July meeting of the Federal Open Market Committee (FOMC) that the committee intended to continue using the PCE price index as its gauge of inflation, although that decision would be revisited early next year. Warsh may have intended this statement to reassure financial markets that there would be continuity in the Fed’s measure of inflation. However, some investors appear to have interpreted Warsh’s statement that the decision would be revisited next year as an indication that he favored moving to a measure that would show lower rates of inflation than those shown by the PCE.

In other words, some investors believe that in the future the FOMC might be willing to accept higher levels of PCE inflation. Perhaps in response to this interpretation, the yield on the 30-year U.S. Treasury bond increased in the days following Warsh’s press conference. Higher expected inflation can lead to lower bond prices and higher bond yields. (We discuss this point in Money, Banking, and the Financial System, Chapter 5, which is now available in a new edition.) Warsh is scheduled to speak on Friday at the Kansas City Fed’s annual Jackson Hole Economic Policy Symposium. His speech will cover his views on the current state of the economy and may give clues as to the future monetary policy actions he may support.

Image created by ChatGPT

The following figure shows headline PCE inflation (the blue line) and core PCE inflation (the red line)—which excludes energy and food prices—for the period since January 2019, with inflation measured as the percentage change in the PCE from the same month in the previous year. In July, headline PCE inflation was 3.7 percent, unchanged from June. Core PCE inflation in July was 3.3 percent, also unchanged from June. Headline PCE inflation was slightly higher than forecast by economists surveyed by the Wall Street Journal, while core PCE was equal to the forecast. Both headline PCE inflation and core PCE inflation remain well above the Fed’s 2 percent annual inflation target.

The following figure shows headline PCE inflation and core PCE inflation calculated by compounding the current month’s rate over an entire year. (Often referred to as 1-month inflation.) Measured this way, headline PCE inflation increased from –1.3 in June to 1.9 percent in July. Core PCE inflation increased from 1.8 percent in June to 3.0 percent in July. Headline inflation was very low in June—prices actually fell during the month—largely because of falling gasoline prices. Today’s data show here was a noticeable acceleration in inflation during July. Of course, it’s important not to overinterpret the data from a single month.

Fed policymakers believe that inflation in non-market services can skew PCE inflation. Non-market services are services whose prices the BEA imputes rather than measures directly. For instance, the BEA assumes that prices of financial services—such as brokerage fees—vary with the prices of financial assets. So that if stock prices rise, the prices of financial services included in the PCE price index also rise. Former Fed Chair Jerome Powell has argued that these imputed prices “don’t really tell us much about … tightness in the economy. They don’t really reflect that.” The following figure shows 12-month headline inflation (the blue line) and 12-month core inflation (the red line) for market-based PCE. (The BEA explains the market-based PCE measure here.)

Headline market-based PCE inflation was 3.5 percent in July, unchanged from June. Core market-based PCE inflation was 3.0 percent in July, also unchanged from June. So, both market-based measures show inflation in July remaining well above the Fed’s 2 percent target.

Fed Chair Kevin Warsh argued in testimony at his confirmation hearing before the Senate that the Fed should stop relying on headline PCE inflation: “The measures [of inflation] I prefer are looking at things that are called trimmed averages. We take out all of the tail-risks, all of the one-off items, and we ask ourselves whether the generalized change in prices is having second-order effects on the economy.” 

Trimmed-mean PCE inflation drops the 31 percent of goods and services with the highest inflation rates and the 24 percent of goods and services with the lowest inflation rates. A closely related measure, median PCE inflation, is calculated by listing the inflation rate in each individual good or service included in the PCE and identifying the inflation rate of the good or service that is in the middle of the list—that is, the inflation rate in the price of the good or service that has an equal number of higher and lower inflation rates. 

The following figure shows headline PCE inflation the (red line), core PCE inflation (the brown line) and trimmed-mean PCE inflation (the blue line). Trimmed-mean PCE inflation in July was 2.3 percent, well below both headline and core PCE inflation.

The following figure from the web site of the Federal Reserve Bank of Cleveland shows headline PCE inflation (the green line), core PCE inflation (the blue line), and median PCE inflation (the brown line). In July, median PCE inflation was 2.7 percent, which was unchanged from June. So Warsh has a point that these two measures of inflation, which are less affected by particularly high or low rates of inflation in some goods and services, indicate that inflation has been running below the Fed’s currently preferred measure. But these measures also show inflation still running well above the Fed’s 2 percent annual inflation target.

Today’s macro data releases appear to have had little effect on the views of investors who buy and sell federal funds futures contracts. These investors believe that the FOMC will likely not raise its target for the federal funds rate at its meeting on September 15–16 as some analysts have speculated. The probability that the committee will leave its target range unchanged at 3.50 percent to 3.75 percent declined only slightly from 60.4 percent yesterday to 59.9 percent this afternoon. Investors assign a probability of 54.7 percent to the FOMC raising its target range by o.25 percentage points (25 basis points) at its meeting on October 27–28.

As Expected, CPI Inflation Falls Slightly in July

Image created by ChatGPT

Today (August 12), the Bureau of Labor Statistics (BLS) released its report on the consumer price index (CPI) for July. Lower energy and grocery prices contributed to a slight decline in the inflation rate in July compared with June.

The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).

  • The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.4 percent in July, down from 3.5 percent in June. 
  • The core inflation rate, which excludes the prices of food and energy, was 2.5 percent in July, down from 2.6 in June.  

Headline inflation and core inflation were both equal to the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)

In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, both headline (the blue line) and core inflation (the red line) increased in July from the negative values in June. That is, the U.S. economy experienced deflation in June because the price level, measured by the CPI and by the CPI less food and energy prices, fell in that month.

In July, 1-month headline CPI inflation was 0.9 percent and 1-month core CPI inflation was 2.6 percent.

The following figure illustrates the role played by energy prices in contributing to the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had increased at annual rate of 245 percent in March, declined at an annual rate of 16.4 percent in July. The blue line shows the 1-month inflation rate in gasoline prices, which in March had spiked to more than 900 percent measured at an annual rate, declined at an annual rate of 29.4 percent in July. A return to full-scale hostilities in the Middle East would increase oil prices, which would likely lead to an increase in the U.S. inflation rate.

There had been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and the category “food away from home” (the red bar)—primarily food purchased at restaurants. Inflation in grocery prices, which increased 2.3 percent in June, declined 0.9 percent in July. Inflation in food prices away from home increased from 2.8 percent in June to 3.8 percent in July. To this point, increases in energy priced do not seem to have caused a significant increase in either grocery prices or restaurant prices.

Today’s relatively good inflation report, following last week’s report showing an unexpected decline in employment, has likely reduced the chance that Federal Reserve policymakers will increase their target for the federal funds rate at the next meeting of the Federal Open Market Committee (FOMC) on September 15–16. In trading in the federal funds futures market this afternoon, investors assigned a 62.1 percent probability to the FOMC keeping its target unchanged at that meeting, which was up from a 51.6 probability yesterday. Traders assign a 53.2 percent probability to the committee increasing its target at its October 27–28 meeting, down from 62.2 percent yesterday.
It’s worth noting, however, that inflation is still running above the Federal Reserve’s 2 percent annual inflation target. In testimony before Congress in a hearing on his nomination as Fed Chair, Kevin Warsh cautioned that good news in a single month’s inflation report should be treated with caution. Warsh has intentionally moved away from discussing the circumstances under which monetary policy might change in the future—so-called forward guidance. (We discuss forward guidance in Macroeconomics, Chapter 15 (Economics, Chapter 25)). Uncertainty about actions the FOMC may take during its three remaining meeting this year remains high.

Employment in July Unexpectedly Declined

This morning (August 7), the Bureau of Labor Statistics (BLS) released its “Employment Situation” report (often called the “jobs report”) for July. The report showed a decline in employment. 

The jobs report has two estimates of the change in employment during the month: one estimate from the establishment survey, often referred to as the payroll survey, and one from the household survey. As we discuss in Macroeconomics, Chapter 9, Section 9.1 (Economics, Chapter 19, Section 19.1), many economists and Federal Reserve policymakers believe that employment data from the establishment survey provide a more accurate indicator of the state of the labor market than do the household survey’s employment and unemployment data. (The groups included in the employment estimates from the two surveys are somewhat different, as we discuss in this post.) 

According to the establishment survey, there was a net decrease of 23,000 nonfarm jobs during July.  Economists surveyed by the Wall Street Journal had forecast an increase of 83,000 jobs.  Economists surveyed by FactSet had forecast a higher net increase of 100,000 jobs. The BLS revised downward its previous estimates of employment in May and June by a combined 103,000 jobs. (The BLS notes that: “Monthly revisions result from additional reports received from businesses and government agencies since the last published estimates and from the recalculation of seasonal factors.”)

The following figure from the jobs report shows the net change in nonfarm payroll employment for each month in the last two years. The figure shows that since peaking in March with a net increase of 214,000 jobs, job growth has slowed markedly over the last four months. Over the last three months, we’ve seen only an average of 20,000 net new jobs created.

The slow pace of recent job growth is consistent with the view among some economists that slowing labor force growth has driven the break-even rate of employment growth—the rate required to keep the unemployment rate constant—down to nearly zero

Despite the decrease in employment in July, the unemployment rate, which is calculated from data in the household survey, declined to 4.1 percent from 4.2 percent in June. The decline in the unemployment rate was due to a decline in the estimated size of the labor force. Although the estimated size of the labor force can fluctuate significantly from month to month, July was the fifth month in a row during which the labor force is estimated to have declined. Despite that fact, as the following figure shows, the unemployment rate has been remarkably stable over the past year and a half, staying between 4.0 percent and 4.4 percent in each month since June 2024. The Federal Open Market Committee’s current  estimate of the natural rate of unemployment—the normal rate of unemployment over the long run—is 4.2 percent. So, currently the unemployment rate is slightly below that estimate of the natural rate. (We discuss the natural rate of unemployment in Macroeconomics, Chapter 9 and Economics, Chapter 19.)

As the following figure shows, the monthly net change in jobs from the household survey moves much more erratically than does the net change in jobs from the establishment survey. As measured by the household survey, there was a net decrease of 87,000 jobs in July, roughly similar to the net decrease in employment shown in the establishment survey. Since January, the household survey has sown a net increase in jobs in only one month, with a total net decrease of 1.8 million jobs. In contrast, the establishment survey has shown a net increase of 426,000 jobs over the same period. (Note that because of last year’s shutdown of the federal government, there are no data for October or November.)

The household survey has another important labor market indicator: the employment-population ratio for prime age workers—those workers aged 25 to 54. In July, the ratio increased to 80.4 percent, partially reversing the sharp decline in June. The prime-age population ratio can show volatility from month to month but has remained above 80 percent every month since December 2022.

There have been media reports of firms, including Salesforce, Cloudflare, Coinbase, Cisco Systems, and Meta Platforms, laying off workers in information systems. The following figure shows net employment changes in the BLS employment category of “computing infrastructure providers, data processing, web hosting, and related services.” Employment in this sector has been declining during most months since the beginning of 2023. July was an exception with a net increase of 2,400 jobs.

The establishment survey also includes data on average hourly earnings (AHE). As we noted in earlier posts, many economists and policymakers believe the employment cost index (ECI) is a better measure of wage pressures in the economy than is AHE. AHE does have the important advantage of being available monthly, whereas the ECI is only available quarterly. The following figure shows the percentage change in AHE from the same month in the previous year. AHE increased 3.2 percent in July, down from 3.4 percent in June. The rate of increase in AHE has been below 4.0 percent each month since August 2025, indicating that cost pressure from wage increases has not been a significant source of price inflation during the past year.

With inflation having been above the Federal Reserve’s 2 percent annual target every month since March 2021, there has been increasing speculation that the Fed’s policymaking Federal Open Market Committee (FOMC) would increase its target for the federal funds rate at least once before the end of 2026. At the FOMC’s last meeting in late July, three members of the committee voted to increase the target, an unusual amount of dissent from a committee decision.

Does the slowdown in employment growth in recent months reduce the chance that the FOMC will increase its target range for the federal funds rate at its next meeting on September 15–16? Investors in the federal funds futures market believe that the answer is “yes.” Yesterday, investors assigned only a 45.0 percent probability to the committee keeping its target rate unchanged. This afternoon, that probability had increased to 55.9 percent. The BLS will release its estimate of inflation as measured by the consumer price index next Wednesday. That report will provide further evidence about the current state of inflation.