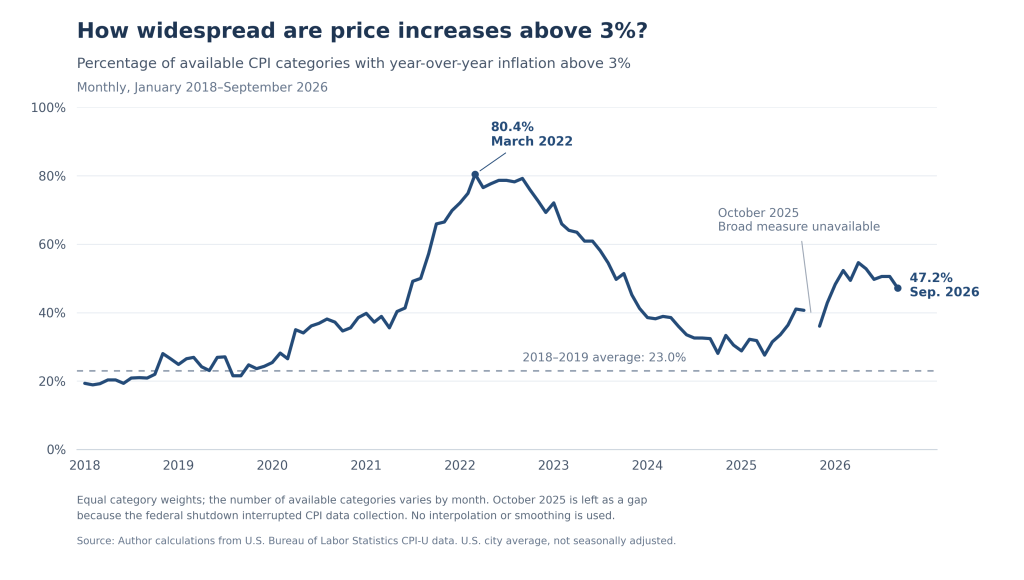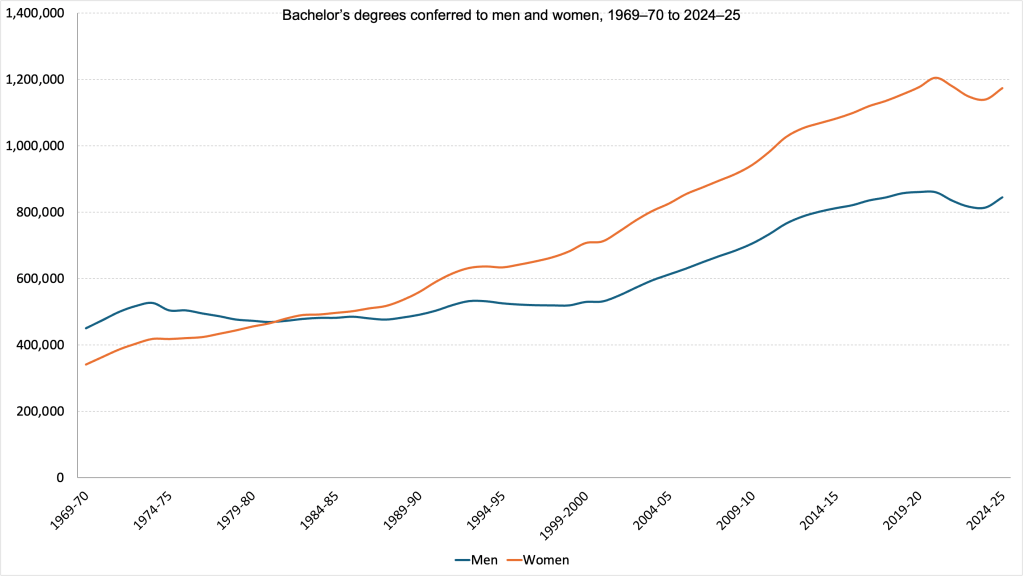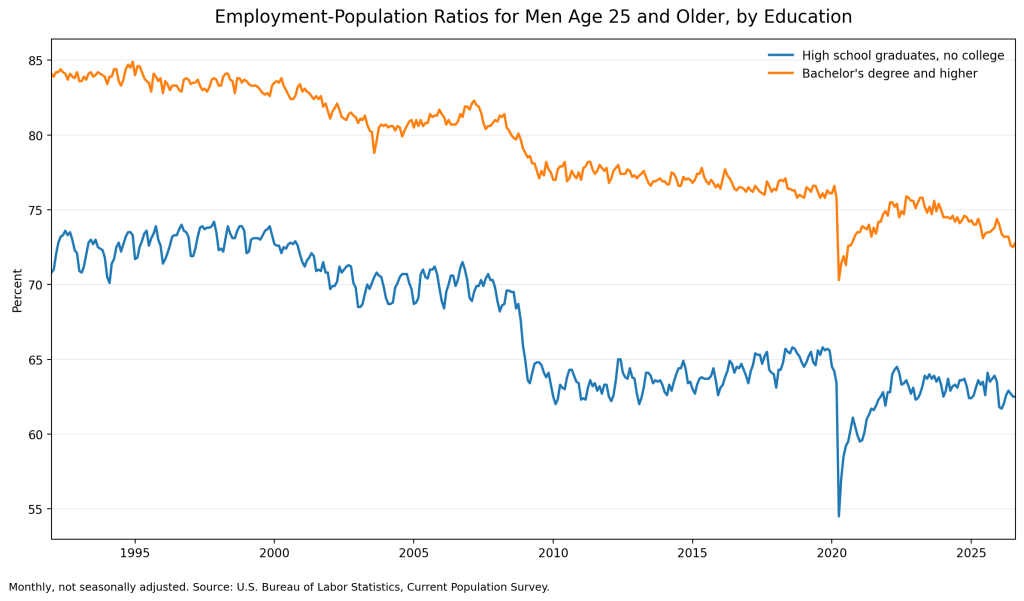Today’s report on the consumer price index (CPI) from the Bureau of Labor Statistics (BLS) provided mixed news about inflation. The rate of inflation slowed in October as energy inflation eased, but food inflation accelerated and inflation in other goods and services remained high. The report makes it likely that members of the Federal Reserve’s policymaking Federal Open Market Committee (FOMC) will raise the committee’s target for the federal funds rate at its next meeting on December 8–9.
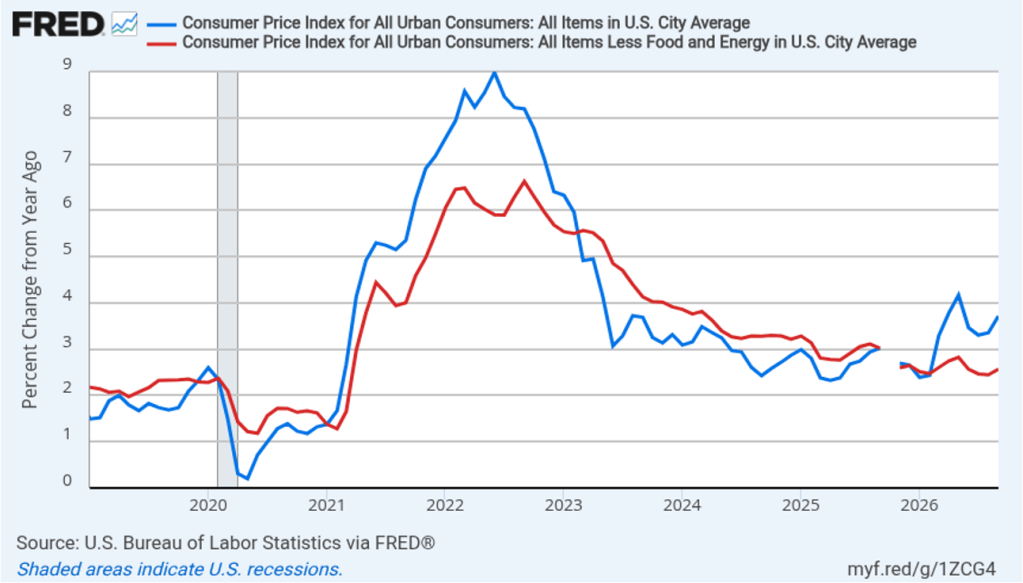
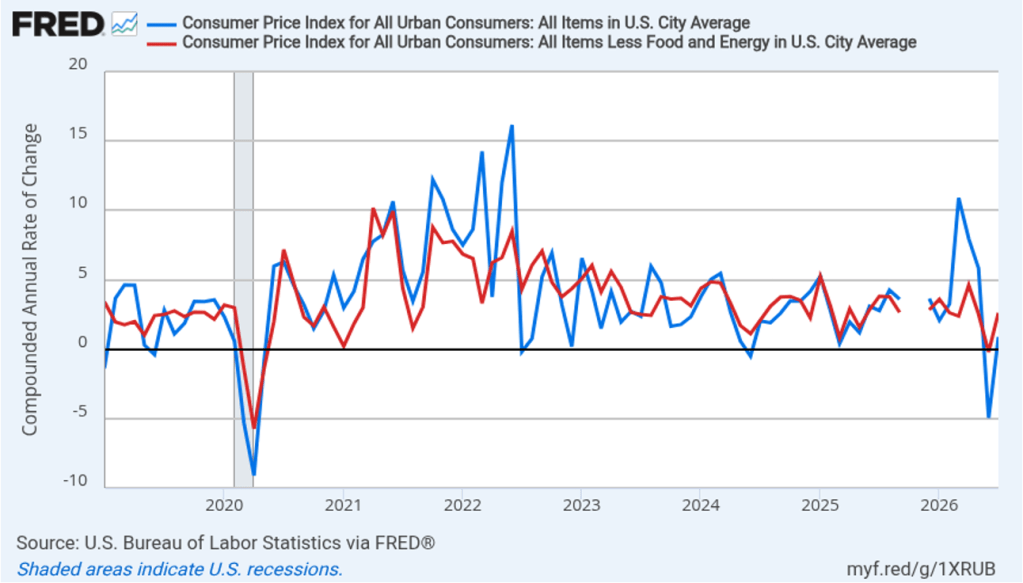
The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).
Normally, we measure the headline inflation rate by the percentage change in the CPI from the same month in the previous. But, because of a federal government shutdown, there is no CPI data for October 2025. Instead, the figure shows the percentage change in the CPI from the previous month. The CPI increased by 0.35 percent in October, which was down from 0.65 percent in September.
The core inflation rate, which excludes the prices of food and energy, was 0.30 percent in October, down from 0.33 percent in September.
Headline inflation and core inflation were both higher than the forecasts of economists surveyed by FactSet.
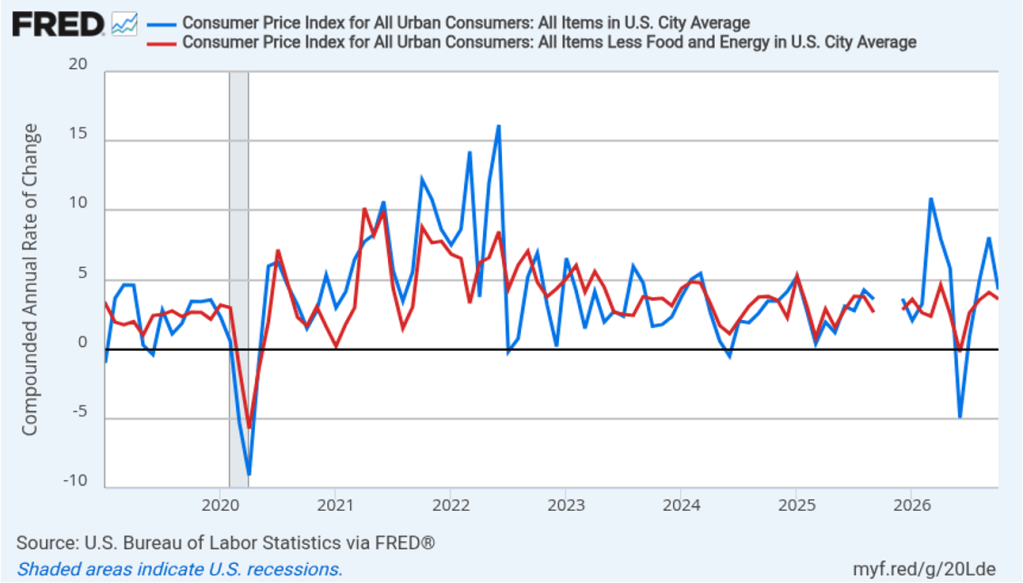
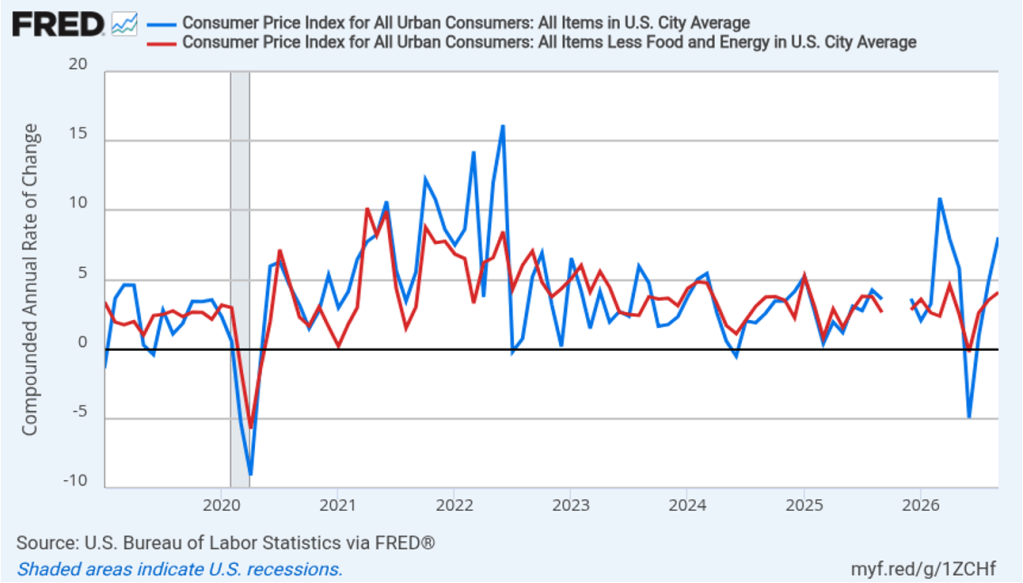
In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline inflation (the blue line) declined from a very high 8.1 percent in September to a still high 4.3 percent in October. Core inflation (the red line) declined from 4.1 percent in September to 3.6 percent in October.
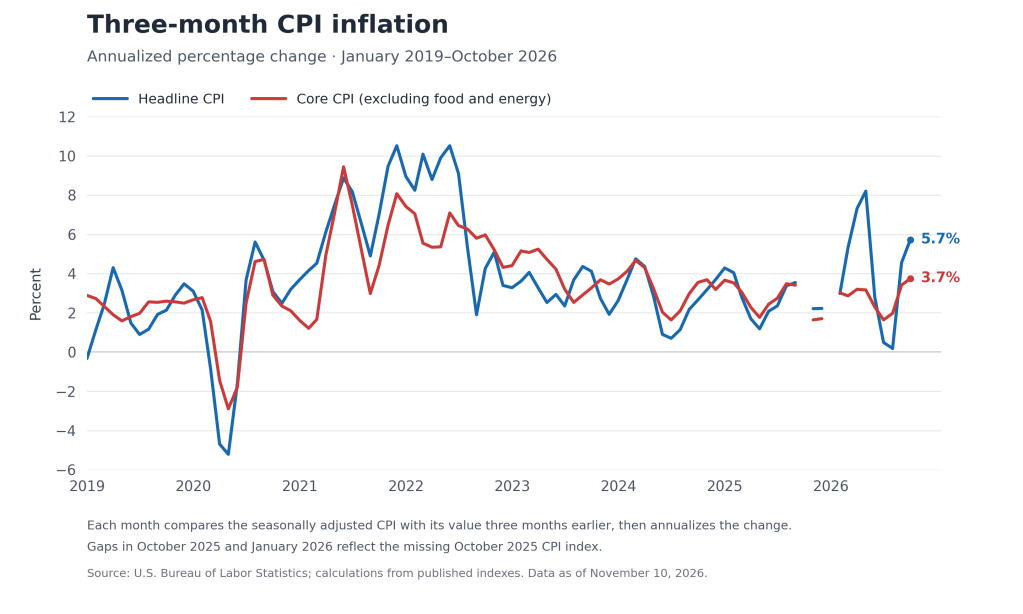
We can also look at 3-month Inflation—that is the inflation rate over the three months prior to the current month, expressed as an annual rate. The following figure shows the 3-month inflation rate for each month since January 2019. The 3-month headline inflation rate in October was 5.7 percent, up from 4.6 percent in September. The 3-month core inflation in October was 3.7 percent, up from 3.4 percent in September. So inflation over the last three months has been well above the Fed’s 2 percent annual inflation target.
Note, though, that the Fed uses the 12-month change in the personal consumption expenditures (PCE) price index, not the change in the CPI, when gauging whether it is meeting its 2 percent annual inflation target. Historically, PCE inflation has been about 0.4 percentage points to 0.5 percentage points lower than CPI inflation. The Bureau of Economic Analysis (BEA) won’t release its estimate of October PCE inflation until November 25.
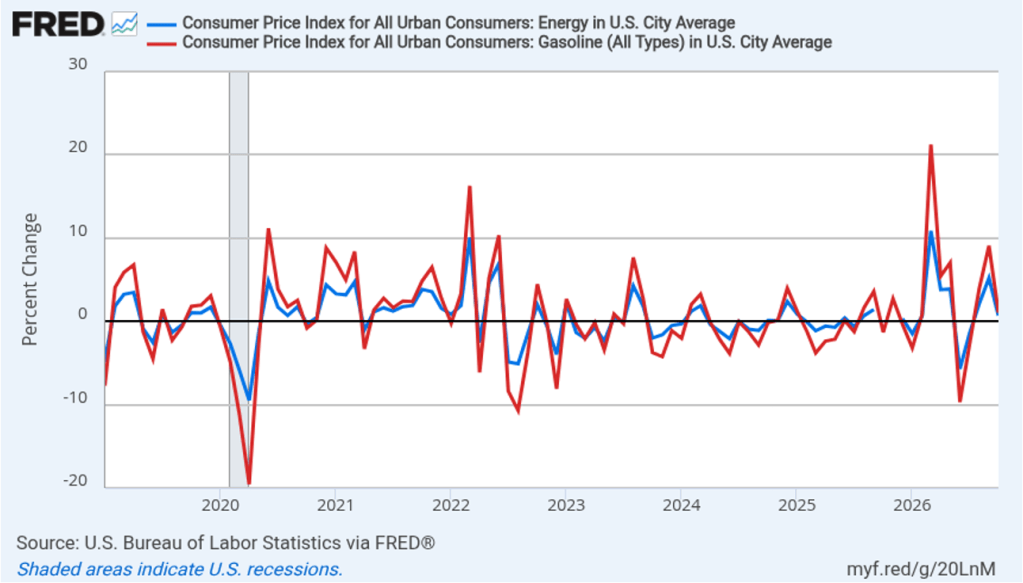
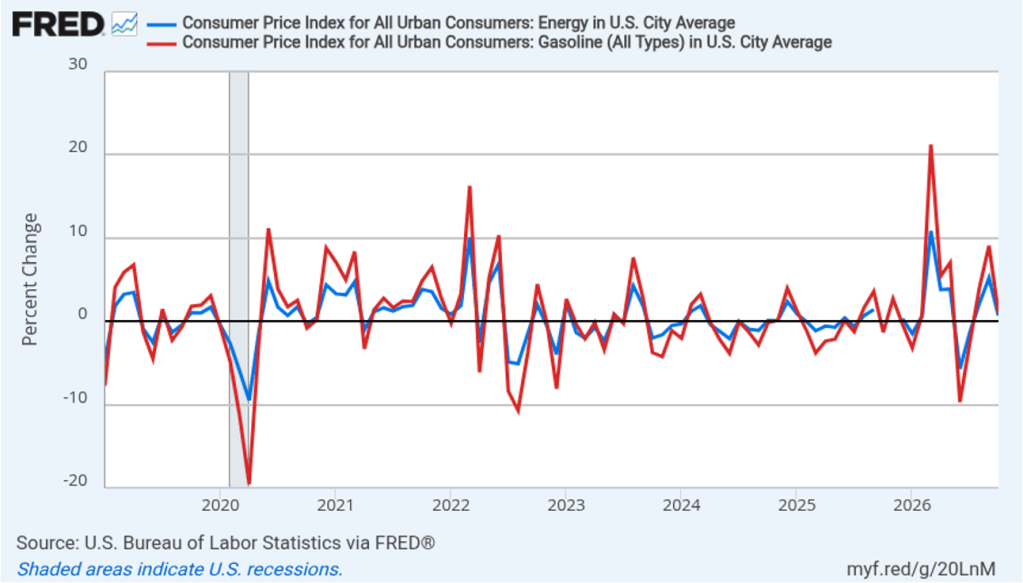
The fact that the gap between headline and core inflation narrowed in October compared with September is explained by a sharp decline in the rate of increase in energy prices. In the following figure, the red line shows the inflation rate in all energy prices included in the CPI, measured as the percentage change from the previous month. Inflation in energy prices was 1.0 percent in October, down from 5.2 percent in September. The blue line shows the monthly inflation rate in gasoline prices, which was also 1.0 percent in October, down from 9.1 percent in September.
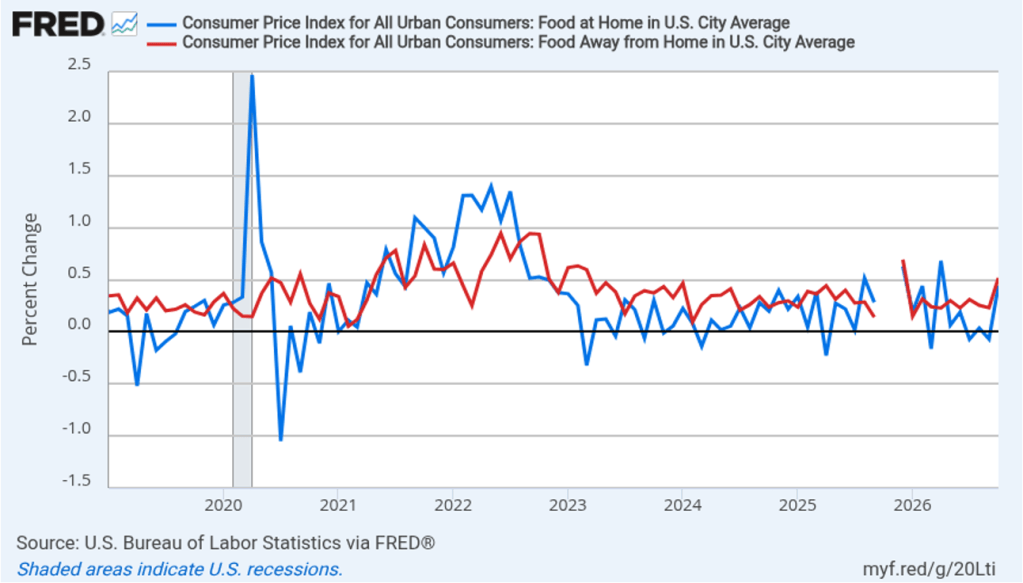
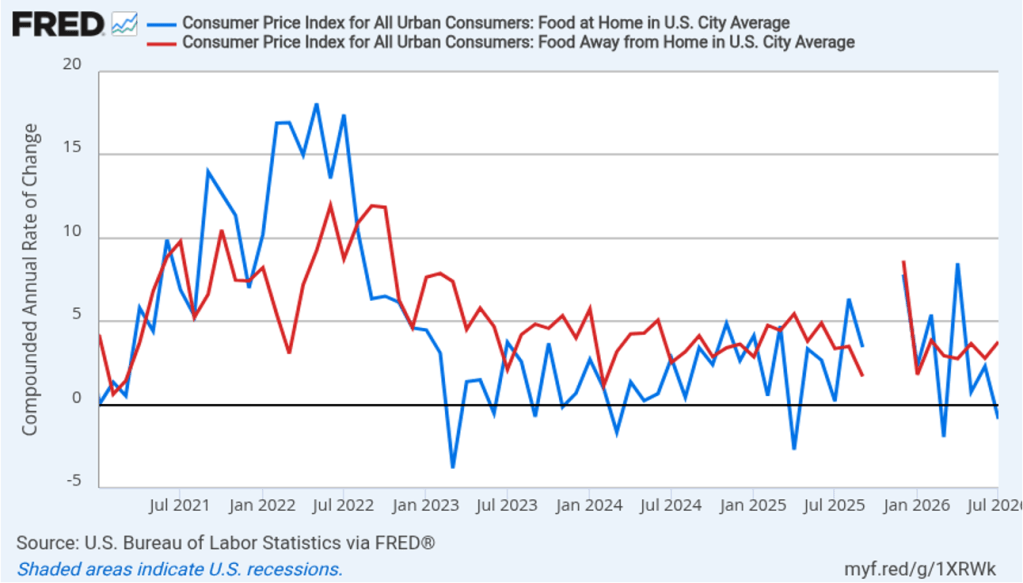
In October, while inflation in energy prices slowed, inflation in food prices increased. The following figure shows inflation, measured as the percentage change from the previous month, in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and in the category “food away from home” (the red bar)—primarily food purchased at restaurants. Grocery prices increased 0.52 percent in October, up from –0.07 percent in September (when grocery prices slightly declined). Restaurant prices also increased 0.52 percent October, up from 0.23 percent in September.
Today’s report showing that inflation remains persistently above the Fed’s 2 percent annual target has made it more likely that Federal Reserve policymakers will increase their target range for the federal funds rate from the current 3.75 percent to 4.00 percent by o.25 percentage points (or 25 basis points) at the next meeting of the FOMC on December 8–9. The inflation report has also increased speculation that the committee may increase its target range by 50 basis points. In recent speeches, both Fed Governor Christopher Waller and Federal Reserve Bank of Dallas President Lorie Logan have raised that possibility.
Trading in the federal funds futures market this afternoon indicates that investors assign an 88.2 percent probability to the FOMC raising its target range by 25 basis points at its December meeting, which is up from an 84.0 percent probability yesterday. Trading indicated that investors assign an 11.8 percent probability to the committee increasing its target range by 50 basis points at that meeting, up from 0 percent yesterday.
This morning (November 6), the Bureau of Labor Statistics (BLS) released its “Employment Situation” report (often called the “jobs report”) for October. Following September’s disappointing report, October brought better news: Payroll employment increased by 165,000, well above the 65,000 increase economists surveyed by the Wall Street Journal had forecast. The unemployment rate edged down from 4.2 percent to 4.1 percent. Revisions to earlier months also made recent job growth look stronger than previously reported.
The jobs report draws on two surveys. The establishment survey counts jobs on employers’ payrolls, while the household survey counts employed people and provides the unemployment rate. As we discuss in Macroeconomics, Chapter 9, Section 9.1 (Economics, Chapter 19, Section 19.1), the surveys cover somewhat different groups. The payroll survey generally provides a less volatile measure of monthly employment changes. The household survey supplies information about workers that payroll records cannot provide.
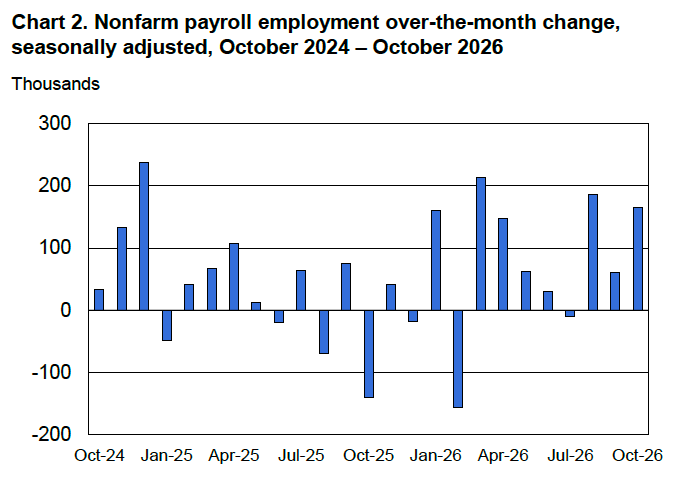
The BLS revised August’s payroll employment increase from 133,000 to 186,000 and September’s increase from 29,000 to 60,000. Together, those revisions added 84,000 jobs to the previously reported totals. ((The BLS notes that: “Monthly revisions result from additional reports received from businesses and government agencies since the last published estimates and from the recalculation of seasonal factors.”) With the revisions, job growth averaged 137,000 per month from August through October, compared with just 28,000 from May through July. Through October, payroll employment growth has averaged about 86,000 per month this year, compared with 10,000 per month in 2025 and 122,000 in 2024. Employment is growing faster than last year, but the average pace remains below that of 2024. The following figure from the jobs report shows the substantial monthly fluctuations in employment, as well as the stronger job growth over the past three months.
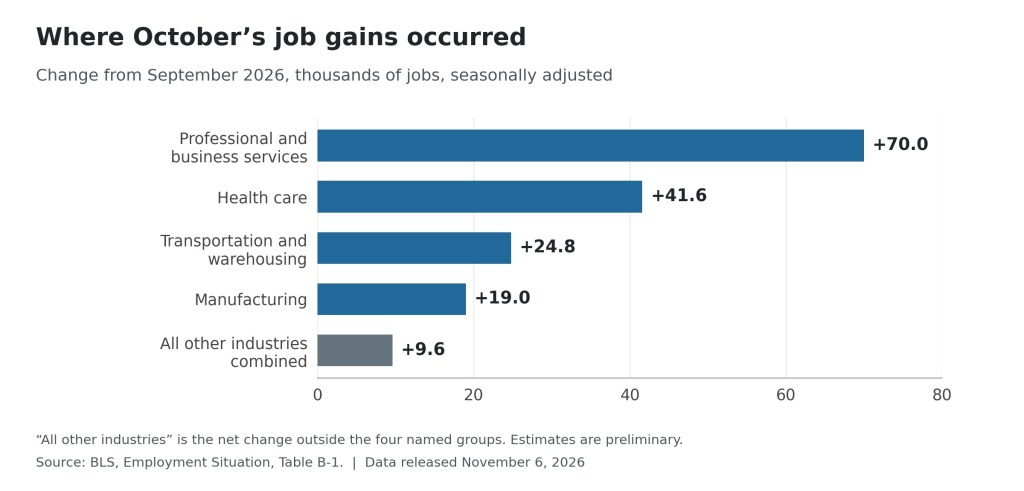
The professional and business services employment category led October’s job gains, adding 70,000. Health care added about 42,000 jobs, transportation and warehousing added about 25,000, and manufacturing added 19,000. These four groups accounted for about 94 percent of the net increase in employment. The leisure and hospitality and wholesale trade categories lost jobs. Of the overall 165,000 increase in jobs, 159,000 were in the private sector and 6,000 were in government. The following figure shows the contributions of the four leading groups and all other industries combined.
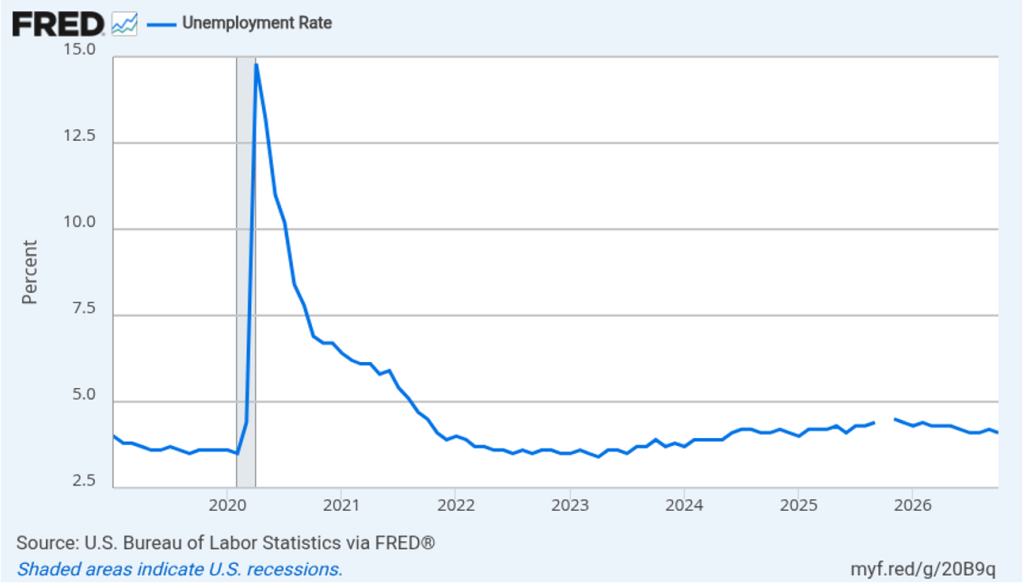
The unemployment rate, which is calculated from data in the household survey, was 4.1 percent in October, down slightly from 4.2 percent in September. The estimated size of the labor force and the number of workers employed increased in October, while the number of workers unemployed fell. The following figure shows that the unemployment rate has been remarkably stable over the past year and a half, staying between 4.0 percent and 4.4 percent in each month since June 2024. The Federal Open Market Committee’s most recent estimate of the natural rate of unemployment—the normal rate of unemployment over the long run—is 4.2 percent. So, currently the unemployment rate is slightly below that estimate of the natural rate. (We discuss the natural rate of unemployment in Macroeconomics, Chapter 9 and Economics, Chapter 19.)
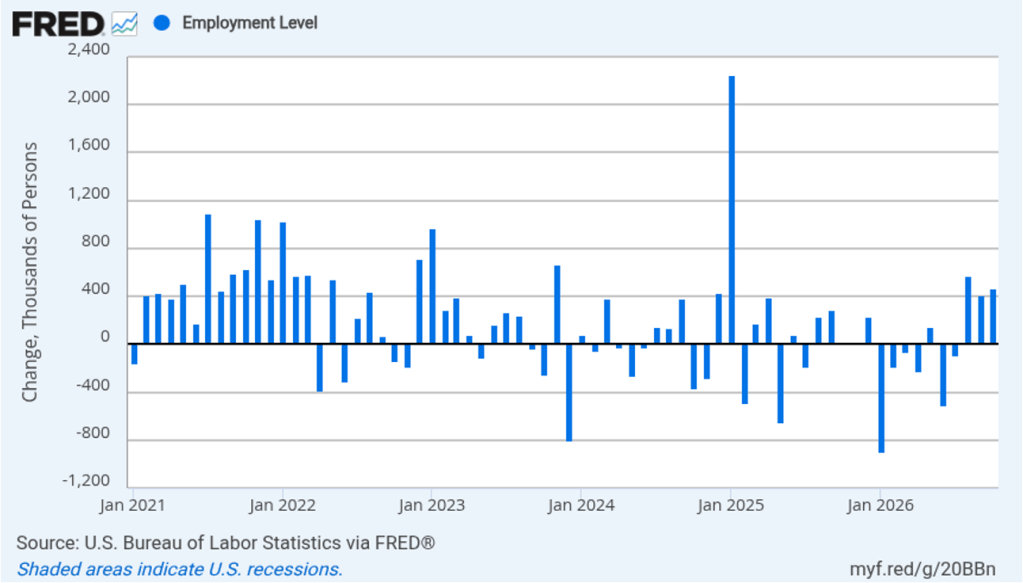
As the following figure shows, the monthly net change in jobs from the household survey moves much more erratically than does the net change in jobs from the establishment survey. As measured by the household survey, there was a net increase of 463,000 jobs in October, far larger than the net increase in employment shown in the establishment survey. Since January, the household survey has shown a net increase in jobs in only four months, with a total net decrease of 377,000 jobs over the period. In contrast, the establishment survey has shown a net increase of 861,000 jobs over the same period. (Note that because of last year’s shutdown of the federal government, there are no data for October or November.)
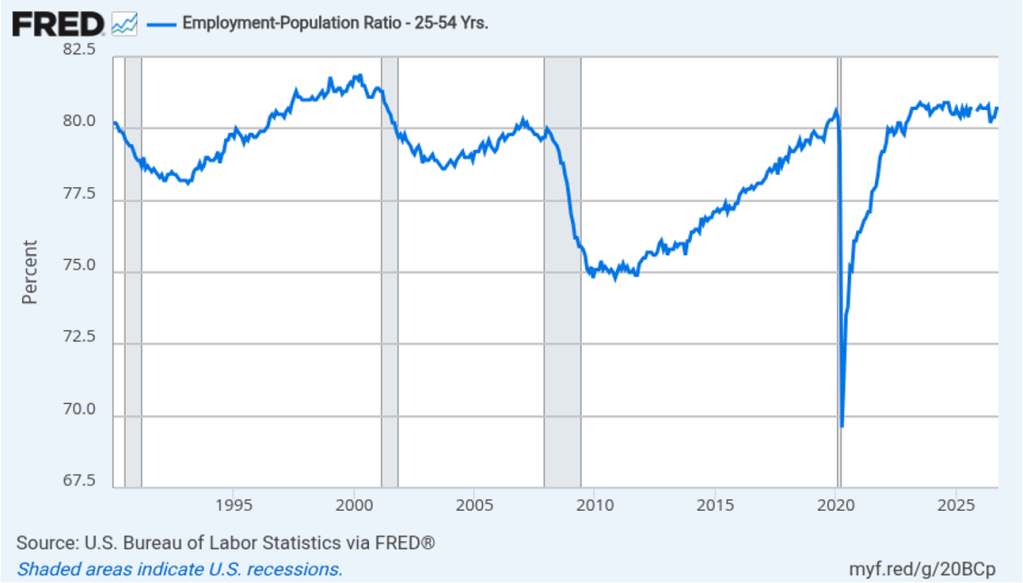
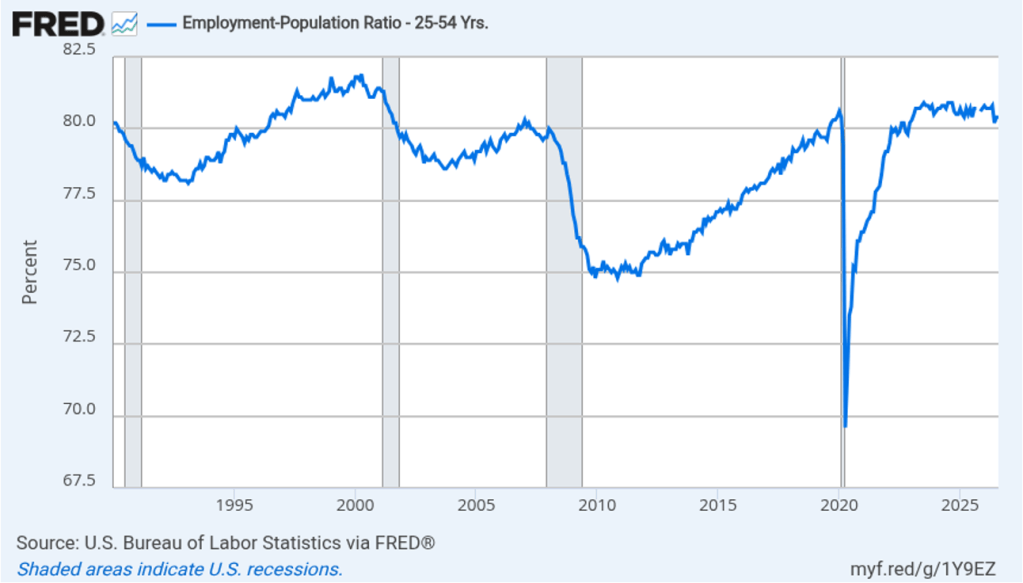
The household survey has another important labor market indicator: the employment-population ratio forprime age workers—those workers aged 25 to 54. In October, the ratio was 80.7 percent, unchanged from September. The prime-age population ratio can show volatility from month to month but has remained above 80 percent every month since December 2022.
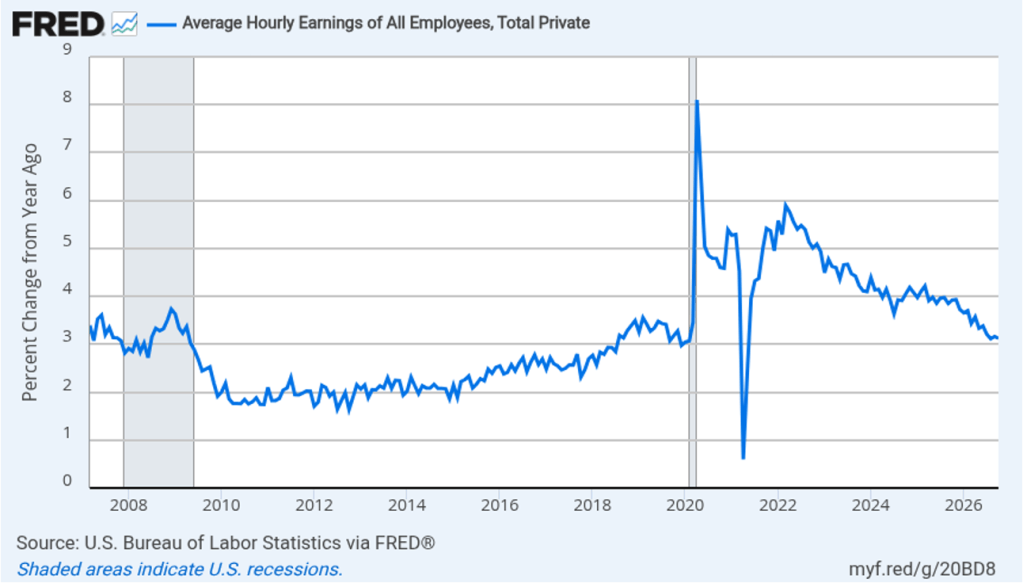
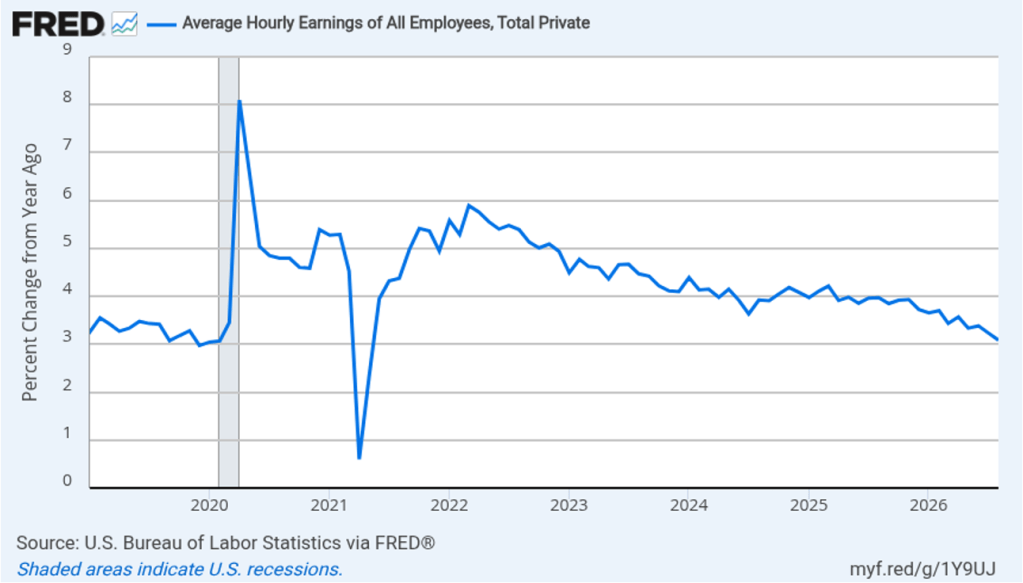
The establishment survey also includes data on average hourly earnings (AHE) measure of wages and salaries. The following figure shows the percentage change in AHE from the same month in the previous year. AHE increased 3.1 percent in October, down from 3.2 percent in September. That was the smallest increase since May 2021. The rate of increase in AHE has been below 4.0 percent each month since August 2025, indicating that cost pressure from wage increases has not been a significant source of price inflation during the past year. Over this same period, wage increases have struggled to keep up with price increases, resulting in a decline in real wages.
Will the strong October jobs report matter for Federal Reserve policy? At its October 27–28 meeting, the Federal Open Market Committee (FOMC) left its target range for the federal funds rate unchanged at 3.75 percent to 4.00 percent. Inflation remains a concern: The personal consumption expenditures price index in September was up 3.6 percent from September 2025, well over the Fed’s 2 percent annual target. Today’s jobs report indicates strength in labor market, which may make Fed policymakers more willing to focus on inflation. That would increase the likelihood that the committee will raise the target for the federal funds rate at its next meeting on December 8–9.
Trading in the federal funds futures market this afternoon indicates that investors believe that the committee will increase its federal funds rate target at its December meeting. Yesterday, trading in the federal funds futures market indicated that investors assigned a 66.9 percent probably to a rate increase at the December meeting, while this afternoon the probability had increased to 79.1 percent.
Photo of a meeting of the Federal Open Market Committee earlier this year from federalreserve.gov
What’s inflation? The answer seems easy: Inflation means that prices are rising …. but there are complications. When we experience inflation, does every price rise? If not, does it matter which prices or how many prices are rising? If a price rises one month and falls the next, is that still inflation?
We answer these questions in Macroeconomics, Chapter 19. As we discuss in that chapter, we measure inflation as the increase in the price level from one year to the next. We focus on the price level rather than on the prices of any particular goods or services because we want to know what is happening to a measure of average prices. Because we are looking at an average of prices, we would expect that when the economy experiences inflation, some prices will rise, but other prices may fall, and some prices may be unchanged.
Put another way, when we measure inflation, we are asking a macroeconomic question: Are there forces in the economy that are making an average of prices increase, and if so, by how much? When we look at individual prices, we are typically asking microeconomic questions: How much will an outbreak of avian flu increase the price of eggs? How much will a surge in constructing data centers increase the price of computer chips? Microeconomic developments do sometimes affect our inflation measures. For example, if conflict in the Middle East disrupts the flow of oil, raising oil prices, the effect may be large enough to increase the price level.
Image created by ChatGPT of oil tankers passing through the Strait of Hormuz
The two most closely watched measures of the price level are the consumer price index (CPI), which is compiled monthly by the Bureau of Labor Statistics (BLS), and the personal consumption expenditures (PCE) price index, which is compiled monthly by the Bureau of Economic Analysis (BEA). Economists and Federal Reserve policymakers prefer the PCE measure of the price level because it includes more goods and services than does the CPI. Each month’s release of CPI and PCE data can help answer three questions:
How much inflation are consumers experiencing?
How well is the Federal Reserve meeting its mandate from Congress to achieve price stability?
How likely is inflation to persist?
The public’s strongly negative reaction to the Covid-era surge in inflation that began in the spring of 2021 made it clear that high inflation rates were an important political issue. The persistence of inflation rates above the Fed’s 2 percent annual target caused “affordability” to be an important issue in the 2026 midterm elections in the United States.
The CPI is designed to answer question 1. Although the inflation any individual household experiences will depend on the particular mix of goods and services consumed, the percentage change in the CPI provides a good measure of the inflation experienced by the typical household. The Fed answers question 2. using the percentage change in the PCE from the same month in the previous year. Fed policymakers have met the Congressional mandate for stable prices if the annual inflation rate as measured by the PCE is 2 percent or less. (Note that there is some debate whether 2 percent inflation represents “price stability” in the way Congress intended.)
Question 3. is the most difficult to answer. Future inflation rates depend partly on macroeconomic policy, particularly monetary policy, and on geopolitical developments, such as the likelihood that conflict in the Middle East will be resolved or will accelerate. But the details of how particular prices have been changing can also provide clues as to how persistent inflation is likely to be. Federal statistical agencies, economists, and policymakers make adjustments to the CPI and PCE with the aim of better identifying the underlying rate of inflation—that is, the movement in average prices after eliminating prices that may be increasing or decreasing for short-run, microeconomic reasons.
The best-known adjustments to the CPI and PCE are the core measures that exclude the prices of food and energy. The BLS began issuing a monthly measure of core CPI in 1977 and the BEA began issuing a monthly measure of core PCE in 2000, although it had been compiling a similar measure since 1974.
Image created by ChatGPT
The BLS explains why it began issuing data on core CPI:
“Food and especially energy have been more volatile in recent years than almost everything else in the CPI, and their sharp short-term movements up and down can dominate the movement of the All items [CPI] index, obscuring longer term underlying trends or important changes in other categories. … Inflation due largely to higher food or energy prices might have different policy implications than broader inflation.”
Fed policymakers have looked at a number of other ways to adjust the PCE to gauge the underlying inflation rate. For example, as we discuss in a recent blog post, Fed policymakers believe that inflation in non-market services can skew PCE inflation. Non-market services are services whose prices the BEA imputes rather than measures directly. For instance, the BEA assumes that prices of financial services—such as brokerage fees—vary with the prices of financial assets. So that if stock prices rise, the prices of financial services included in the PCE price index also rise. Former Fed Chair Jerome Powell has argued that these imputed prices “don’t really tell us much about … tightness in the economy. They don’t really reflect that.”
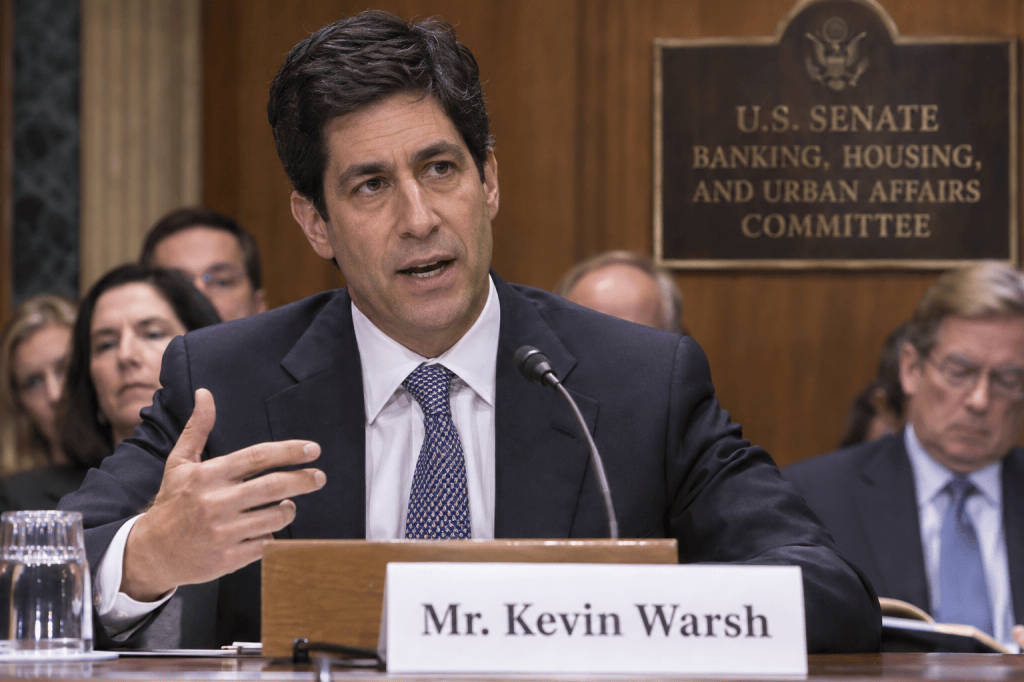
Image created by ChatGPT of Kevin Warsh testifying before the Senate Banking Committee
At his confirmation hearing before the Senate Banking Committee, Fed Chair Kevin Warsh, addressed the issue of determining the underlying inflation rate:
“What I’m most interested in is, what’s the underlying inflation rate? Not what’s the one time change in prices because of a change in geopolitics or a change in beef, but what’s the underlying generalized change in prices in the economy? … The measures I prefer are looking at things that are called trimmed averages, where we take out all of the tail risks, all of the one-off items, and we ask ourselves whether the generalized change in prices is having second order effects on the economy. … Some in the economics profession are increasingly looking to these median type measures ….”
As we’ve discussed in previous blog posts, two widely available measures of the type Warsh is referring to are:
Trimmed-mean PCE inflation, which drops the 31 percent of goods and services with the highest inflation rates and the 24 percent of goods and services with the lowest inflation rates, and
Median PCE inflation, which is calculated by listing the inflation rate in each individual good or service included in the PCE and identifying the inflation rate of the good or service that is in the middle of the list—that is, the inflation rate in the price of the good or service that has an equal number of higher and lower inflation rates.
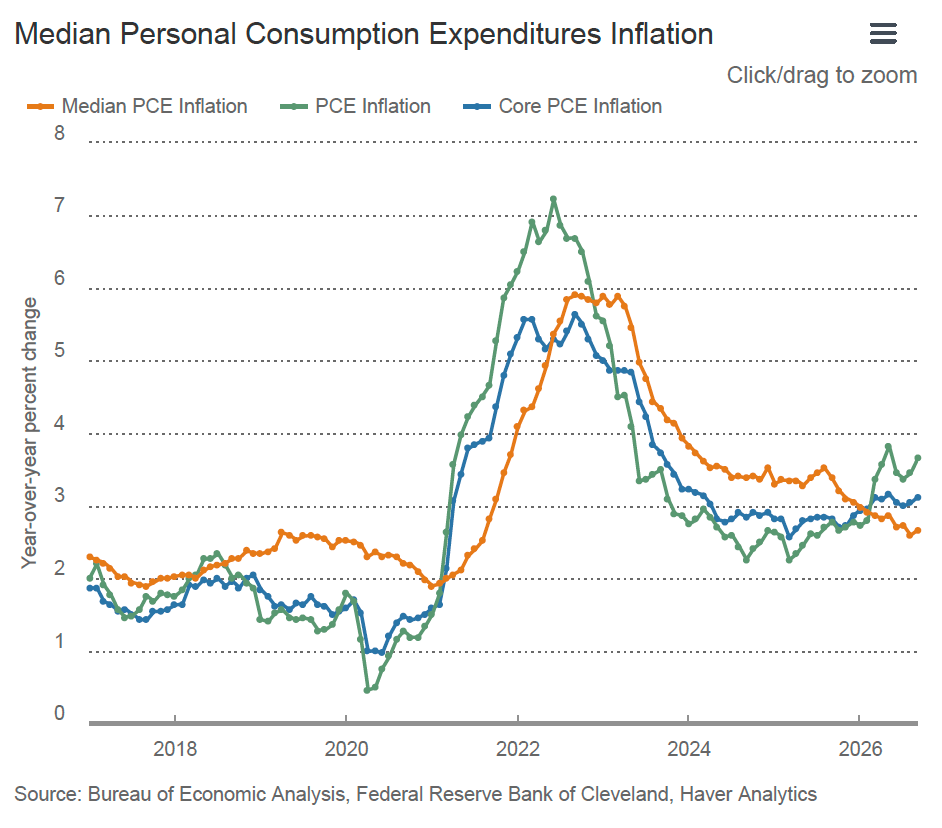
The following figure, from the website of the Federal Reserve Bank of Cleveland shows the relationship of headline PCE inflation (the green line), core PCE inflation (the blue line), and median PCE inflation (the brown line). Since March 2026, median inflation has been below both headline and core inflation, which may indicate that it is a better indicator of underlying inflation in the months since the conflict in the Middle East intensified.
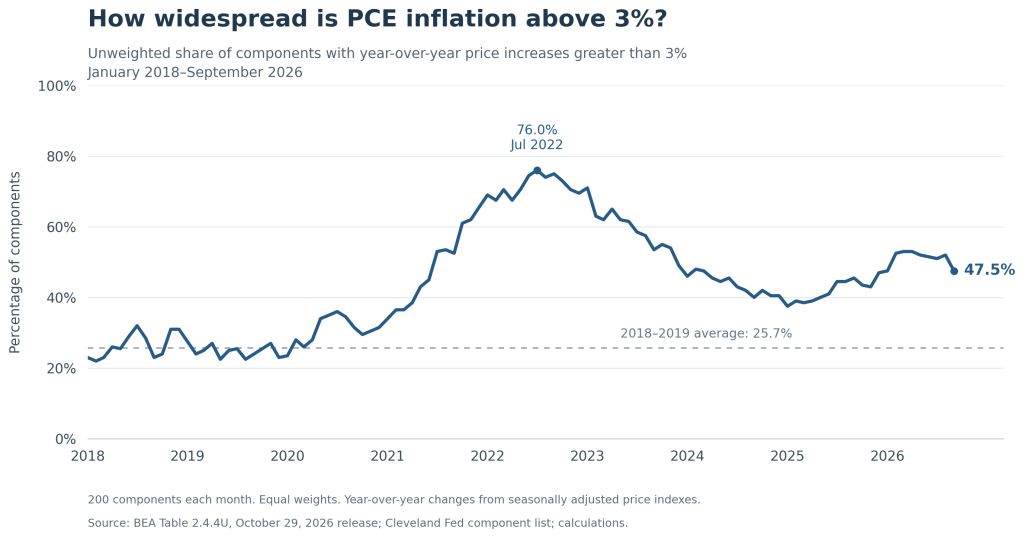
In an address in August at the Federal Reserve Bank of Kansas City’s economic policy symposium in Jackson Hole, Wyoming, Warsh discussed a less familiar indicator of underlying inflation: “To try to gauge underlying inflation, I find it instructive to disaggregate the 199 individual components of the PCE price measure. Over the past 12 months, 54 percent of goods and services in the PCE basket showed price increases above 3 percent. This is well below the post-pandemic highs of about 77 percent, but it remains well above the level of 32 percent in the two decades that preceded the pandemic.”
Image created by ChatGPT
The following figure shows for each month from January 2018 through September 2026, the fraction of PCE components that experienced price increases of greater than 3 percent. For instance, prices included in the PCE component “Personal computers/tablets and peripheral equipment” increased 9.7 percent from September 2025 to September 2026, while prices in the PCE component “Telephone and related communication equipment” decreased by 12.7 percent over the same period. The figure confirms Warsh’s statement: During 2018 and 2019, when headline PCE inflation was less than 2 percent in most months, 25.7 percent of PCE components experienced price increases of more than 3 percent, while in September 2026, 47.5 percent did.
As the following figure shows, we get a similar result if we plot the same indicator for the CPI.
So, we have a number of ways of attempting to measure the underlying inflation rate. The reason, once again, why Fed policymakers are concerned about the underlying inflation rate rather than just the headline inflation rate is that monetary policy is better equipped to respond to movements in the underlying inflation rate than it is to respond to blips in the headline inflation rate that may be caused by transitory factors such as a sharp increase or decrease in energy prices.
Which measure of underlying inflation might be best? Here is ChatGPT’s (very long!) analysis.
ChatGPT on measures of underlying inflation
The three approaches answer different questions. A trimmed mean or median estimates a central rate of price increase after limiting the influence of unusually large increases and decreases. The percentage of categories rising more than 3% measures how widespread relatively rapid price increases are. My preference would be to use a trimmed mean and a median to assess the underlying inflation rate, and breadth to assess how generalized the pressure is.
The distinction matters because these measures can move in different directions without either being incorrectly calculated.
1. What each measure is trying to tell us
It helps to distinguish the measured change in the overall price index from indicators intended to extract a more persistent signal.
Measure
Main question it answers
Principal strength
Principal limitation
Headline inflation
How much did the full price index increase?
Includes the entire consumption basket
Large movements in a few components can obscure the broader trend
Conventional core inflation
How much did prices excluding food and energy increase?
Simple, familiar, and consistently defined
Excludes some informative movements while retaining large movements elsewhere
Trimmed mean
What is the average increase among components in the middle of the price-change distribution?
Reduces sensitivity to extremes while preserving information about the size of central price changes
Results depend on trimming choices; excluded movements can contain useful information
Median
What price increase lies at the expenditure-weighted midpoint?
Strong protection against unusually large increases and decreases
Discards most information about the rest of the distribution
Share above 3%
How much of the basket—or how many categories—has inflation above a chosen threshold?
Makes the breadth of faster price increases easy to see
Does not measure how far above or below the threshold prices are rising
The first conceptual caution is that an outlying price increase is not necessarily an error or a temporary disturbance. It can be a genuine, persistent change in a relative price. Removing its influence may help estimate the common inflation trend, but it also removes part of what consumers are paying.
A simple illustration
Suppose a hypothetical fixed-weight basket contains ten equally weighted categories. For illustration, calculate a trimmed mean by dropping the highest and lowest observations. All changes refer to the same period.
Category price changes
Full-basket average
Trimmed mean
Median
Share above 3%
All ten rise 2%
2%
2%
2%
0%
Nine rise 2%; one rises 22%
4%
2%
2%
10%
Nine rise 4%; one falls 16%
2%
4%
4%
90%
These are hypothetical calculations, not the precise construction of any published index.
The second row captures the usual argument for robust inflation measures: one exceptionally large increase raises the average even though most categories are rising moderately.
The third row is equally important. One exceptionally large decline can hold down headline inflation while most prices rise rapidly. Median and trimmed mean measures can therefore indicate more inflation pressure than the headline measure. Their purpose is to reduce the influence of both tails, rather than systematically produce a lower number.
2. Trimmed mean: a useful compromise between robustness and information
A trimmed mean ranks component price changes and removes a specified portion from each end of the distribution. It averages the remaining changes using their expenditure weights.
The precise implementation matters:
The Dallas Fed trimmed mean PCE removes 24% of expenditure weight from the lower tail and 31% from the upper tail, retaining the middle 45%.
The Cleveland Fed 16% trimmed mean CPI removes 8% of expenditure weight from each tail, retaining the middle 84%.
These are percentages of expenditure weight, not percentages of the number of category names. They are also quite different degrees of trimming, so “the trimmed mean” does not identify a unique estimator. Sources: Dallas methodologyand Cleveland methodology.
Advantages
It adapts to where the unusual movements occur. Conventional core inflation always excludes food and energy. A trimmed mean instead excludes whichever components have the most extreme changes that month. Food or energy can remain in the calculation when their changes are near the middle; a large movement elsewhere can be removed.
That is attractive because the economic reason for discounting a price movement is generally its usefulness as a signal of continuing inflation, rather than its membership in a permanently excluded category.
It retains information about the magnitude of many price changes. If numerous components in the retained middle rise from 2% to 4%, the trimmed mean responds to the size of those increases. It uses more of the distribution than a median and substantially more information about magnitude than a threshold count.
It limits offsetting distortions from the two tails. It can help identify whether low headline inflation reflects broadly moderate increases or a combination of substantial increases and a few very large declines.
Disadvantages
The trimming rule requires judgment. How much should be trimmed? Should the upper and lower tails be treated symmetrically? The answers depend partly on the distribution of relative-price changes and the statistical objective being pursued.
The Dallas proportions were selected using historical data. That provides an empirical foundation, but it does not guarantee that the same proportions will remain optimal in every subsequent inflation regime. Its asymmetric trimming also illustrates that a simple symmetric distribution of price changes cannot be taken for granted. Dallas methodology
It can remove economically important signals. An extreme increase may be the first sign of pressure that will spread to other categories. Alternatively, a sector may experience sustained inflation for several years. The trimming procedure classifies observations by their position in the distribution; it does not know whether the underlying cause is temporary, persistent, supply driven, or demand driven.
It cannot remove a shock merely because the shock is temporary. If a temporary common disturbance moves most prices, it moves the middle of the distribution too. A trimmed mean is robust to sufficiently concentrated extremes, not to every disturbance that policymakers might wish to look through.
My assessment is that a trimmed mean offers an appealing balance: it reduces the influence of exceptional observations while retaining meaningful information about the size of price changes across a substantial portion of spending.
3. Median inflation: greater resistance to extremes, greater loss of information
The published Cleveland Fed median measures are expenditure weighted. The components are ranked by their monthly price changes, and the median is the change at the 50th percentile of expenditure weight. It is not the inflation rate of the middle category in a list where every category receives one vote. See the median CPI and median PCE descriptions.
Advantages
The median is highly resistant to the size of extreme observations. If a component already in the upper tail rises 30% instead of 10%, that change generally has no effect on the median. The same applies to exceptionally large declines.
It provides a clear indication of movement in the center of the distribution. An increase in the median suggests that the distribution’s midpoint has shifted. It is less vulnerable to the interpretation that a rise in the average reflects only one or two extreme observations.
It avoids having to choose particular trimming percentages. Within the family of measures that focus on the middle of the distribution, the median has a transparent definition. That does not eliminate every methodological choice—component definitions, weights, and seasonal adjustment still matter—but it removes the choice between, say, an 8% and a 15% trim.
Disadvantages
A large amount of inflation pressure can occur away from the midpoint. Suppose 51% of expenditure weight has inflation of 2%, while the remaining 49% has inflation of 8%. In a simple fixed-weight calculation:
Average inflation is 4.94%.
Median inflation is 2%.
The median accurately describes the midpoint, but a policymaker would lose important information by looking only at that number.
It can also change abruptly. Reverse the weights to 49% at 2% and 51% at 8%, and the median jumps from 2% to 8%, even though average inflation rises only from 4.94% to 5.06%. Real data are more complicated, but the example shows why the median is not always a smooth measure of changes in the whole distribution.
Large expenditure categories can have considerable influence over which observation becomes the median. A large category occupies a wide interval of cumulative expenditure weight. Housing is particularly relevant. Cleveland revised its CPI methodology by dividing owners’ equivalent rent into four regional components to reduce the distortion that a single large OER component could create. This is a concrete example of how the level of aggregation affects a median. Cleveland methodology revision
The median need not have the same long-run average as headline inflation. Persistent relative-price trends and asymmetry in the distribution can create a systematic gap between the median and the mean. A Cleveland study found such a positive gap for median PCE in its historical sample. Consequently, a median reading of 2% is not automatically equivalent to aggregate PCE inflation being at the Fed’s 2% objective. Carroll and Verbrugge, 2019
I would use the median as a valuable check on whether the center is moving, while continuing to examine what is happening on either side of it.
4. The share above 3%: particularly useful for breadth, limited as an estimate of the inflation rate
For the unweighted version we have been considering, the calculation is:\[ \text{Breadth}_t = 100\times \frac{\text{number of categories with inflation above 3%}} {\text{number of categories observed}}. \]
An expenditure-weighted version instead adds up the spending shares of the categories above 3%. Those two calculations answer different questions.
Advantages
It directly addresses whether inflation is concentrated or widespread. An aggregate rate can be high because of a few exceptional increases or because of moderate increases across many categories. Breadth helps distinguish those situations.
Extreme observations have bounded influence. In an unweighted count, a category rising 50% contributes exactly as much as a category rising 4%. Each category can change the numerator by at most one. This makes the measure well suited to the particular question of how widely elevated inflation is distributed.
It can reveal changes that the median misses. Suppose the share above 3% rises from 20% to 45%. The median can remain below 3% throughout, yet the growing upper portion of the distribution may be informative. Breadth shows that development directly.
An unweighted count can reveal generalization across sectors without being dominated by the largest spending categories. That can be useful when each category is being treated as a separate signal about price-setting behavior. Equal weighting has a coherent purpose, even though it sacrifices a direct interpretation in terms of household spending.
Disadvantages
It throws away information about magnitude
Consider two hypothetical changes:
Every category slows from 10% inflation to 4%. The share above 3% remains 100%, despite substantial disinflation.
Every category moves from 2.9% to 3.1%. The share jumps from 0% to 100%, despite an increase of only 0.2 percentage point in every category.
The first example shows how breadth can miss major progress. The second shows how a hard threshold can exaggerate the apparent importance of a small movement.
This is why I would examine several thresholds or inflation-rate ranges, rather than place too much weight on whether a single 3% line has been crossed.
Weighting changes the economic interpretation
Suppose six small categories each account for 5% of spending and have inflation of 4%, while four larger categories each account for 17.5% of spending and have inflation of 1%.
Then:
Statistic
Result
Percentage of categories above 3%
60%
Percentage of expenditure weight above 3%
30%
Expenditure-weighted median
1%
Simple expenditure-weighted average
1.9%
The unweighted measure correctly reports that most categories have relatively rapid increases. It does not establish that most consumer spending is experiencing those increases.
Both versions are useful, provided their interpretation is explicit. For example, the Federal Reserve’s 2026 research on inflation breadth uses weighted shares of the CPI basket, as specified in its accessible figures. Those shares should not be compared directly with unweighted counts. Federal Reserve, Figures 2–3
The category classification can materially change the answer
If a category with inflation above 3% is divided into ten subcategories, each with the same inflation rate, its influence on an unweighted count increases even though nothing economic has changed.
A count therefore requires a consistent set of mutually exclusive categories at a reasonably stable level of detail. Counting both a broad category and its subcategories would effectively give some prices multiple votes.
Expenditure weighting avoids the particular problem of splitting an otherwise identical category: its total spending weight remains unchanged. But aggregation can still matter when subcategories have different inflation rates.
There is no universal “normal” share implied by the 2% target
The Fed’s objective concerns aggregate PCE inflation, not the inflation rate of every individual component.
For example, five equally weighted categories with inflation rates of:\[ -1\%,\quad 1\%,\quad 2\%,\quad 4\%,\quad 4\% \]
have average inflation of 2%, median inflation of 2%, and 40% of categories above 3%.
A substantial share above 3% can therefore coexist with aggregate inflation at target. What matters is how the share compares with an appropriate historical benchmark calculated in the same way. Warsh’s comparison with the prepandemic 32% is informative for that reason. But the historical average is an empirical benchmark, not an additional policy target.
5. Time horizon creates an especially important difference
There are two separate issues here.
Annual breadth can remain elevated after current price increases have stopped
Suppose many prices rise 4% once and then remain unchanged. Their year-over-year inflation rates will continue to exceed 3% for roughly a year after the increase.
A persistently high annual breadth measure could therefore reflect the continued presence of a past price-level adjustment in the calculation. It does not necessarily mean that comparable increases are continuing each month.
Shorter horizons help. Six-month annualized inflation responds more quickly than twelve-month inflation, while three-month inflation responds more quickly still. The tradeoff is greater sensitivity to short-run fluctuations and seasonal-adjustment issues.
Warsh’s 49% six-month share, compared with 54% over twelve months, is consistent with less widespread rapid increases in the more recent window. It does not, by itself, establish how much the aggregate inflation rate has slowed or where it will go next.
Published annual median inflation is not the median of annual component inflation
This is easy to overlook.
The published median and trimmed mean measures are constructed from monthly component price changes. Their longer-horizon rates accumulate those monthly robust changes. Taking the median across components first and then accumulating through time can produce a different answer from calculating annual inflation for every component first and then taking the median. Cleveland median PCE methodology; Dallas calculation code
A hypothetical example makes the difference clear:
There are three equally weighted categories.
Category A rises 4% in January and is otherwise unchanged.
Category B is unchanged throughout the year.
Category C rises 4% in July and is otherwise unchanged.
Every month, at least two categories have zero inflation. The monthly median is therefore always zero, and an index built by compounding those medians has zero annual inflation.
Yet at year-end, two of the three categories have risen 4%. The median of their annual inflation rates is 4%, and annual breadth above 3% is 66.7%.
This is one reason an annual breadth measure and a published annual median series can give different signals.
There is a useful mathematical connection when the weights, categories, and horizon are identical: if more than half the weight has inflation above 3%, the corresponding weighted median exceeds 3%. If Warsh’s 54% is an unweighted count, it implies that the unweighted median of those annual component changes exceeds 3%. It does not directly establish the value of the published expenditure-weighted median inflation series.
6. None of these measures identifies the cause or persistence of inflation by itself
The motivation for robust measures is strongest when unusually large component movements are mainly idiosyncratic disturbances around a more persistent common trend. But that is an economic interpretation of the distribution, rather than something established by trimming it.
A common supply shock can raise prices across many categories. Tariffs, for example, can affect final imported goods and domestic goods or services that use imported inputs. Federal Reserve research explicitly traces both channels across PCE categories. Minton and Somale, 2025
Consequently:
High breadth does not establish that excess aggregate demand is the cause.
A rise in the median does not establish that the shock will persist.
A concentrated increase does not establish that its effects will soon disappear.
Breadth does help assess the claim that high inflation is confined to a few unusual categories. But distinguishing an ongoing inflation process from a price-level adjustment requires additional evidence about subsequent price changes, quantities, expectations, and the propagation of the original shock.
The same caution applies to smoothness. A smoother series is easier to interpret, but smoothness alone does not establish that it is a better forecast of future inflation.
7. What does the empirical evidence say?
The research supports using robust measures, but it does not identify a universal winner across objectives, samples, and forecast horizons.
Dallas Fed research finds a useful distinction between filtering and forecasting. Dolmas and Koenig’s 2019 comparison concludes that trimmed mean PCE is helpful for filtering transitory variation and has advantages as an estimate of underlying inflation. However, it does not clearly dominate conventional core PCE in real-time forecasts of headline PCE inflation. Those are different tests of usefulness. “Two Measures of Core Inflation: A Comparison”
Cleveland research finds that many trimming choices perform similarly. Meyer and Venkatu find a broad range of trimmed mean estimators with statistically indistinguishable performance, including the median. Their results support the usefulness of focusing on the middle of the distribution, while providing less support for claiming that one finely chosen trim is uniquely best. “Trimmed-Mean Inflation Statistics: Just Hit the One in the Middle”
Relative performance can change across periods. Carroll and Verbrugge’s comparison of median PCE, trimmed mean PCE, and conventional core measures finds that the performance of the median measures changed after the Great Recession. Their analysis emphasizes the role of changes in the asymmetry of the component-price distribution. “Behavior of a New Median PCE Measure: A Tale of Tails”
For breadth, an additional distinction is necessary. A measure can correlate closely with inflation in the same periodwithout being an especially good predictor of future inflation. The Federal Reserve’s 2026 breadth study estimates contemporaneous relationships and examines how those relationships changed after the pandemic. It does not establish that a count above 3% forecasts future inflation better than median or trimmed mean measures. Federal Reserve breadth study
These studies also cover different historical samples. Their results provide reasons to use the measures and evaluate them carefully, rather than guarantees about their ranking in the current environment.
8. How I would use them together
For assessing the inflation outlook relevant to Fed policy, I would give the measures distinct roles.
Keep headline PCE as the outcome to explain and forecast. It is the index to which the Fed’s inflation objective applies. Conventional core PCE remains a useful, familiar comparison.
Use trimmed mean PCE as a central estimate of underlying inflation, with median PCE as a check. My preference for the trimmed mean reflects its retention of more information about the magnitude of price changes. Agreement between it and the median increases confidence that the center of the distribution is moving. Disagreement is a reason to inspect the distribution.
Use breadth to assess generalization. I would look at both category counts and expenditure-weighted shares, with consistent definitions and historical benchmarks. Examining several thresholds would reveal whether a change reflects a substantial distributional shift or many observations barely crossing 3%.
Compare horizons and investigate the components driving disagreement. Twelve-month measures provide perspective; shorter-horizon measures help identify recent changes. The sector composition matters when deciding whether the signal reflects continuing pressure, an earlier adjustment, or an unusual pattern of offsetting increases and declines.
Applied to Warsh’s speech, the comparison of 54% with a prepandemic 32% is meaningful evidence that faster price growth was more widespread than in the benchmark period, assuming a consistent calculation. The fall from about 77% also documents a substantial reduction in breadth. Neither fact supplies a numerical estimate of the underlying inflation rate or determines its future persistence.
Breadth adds valuable distributional information to median and trimmed mean inflation. Its strongest role is as a complement: it tells us how far relatively rapid price increases extend across the basket, while the robust rate measures tell us more about the pace of price increases near the center.
After the Federal Open Market Committee (FOMC) increased its target for the federal funds rate at its September meeting, there was uncertainty as to whether it would raise its target again at its meeting on October 27–28. Today’s report from the Bureau of Labor Statistics (BLS) on the consumer price index (CPI) for September showed that inflation had risen more than expected, likely increase somewhat the probability of the committee raising its target range at its October meeting.
As we’ve noted before, and as we discuss in Macroeconomics, Chapter 15 (Economics, Chapter 25), monetary policy affects the economy with, in the words of Nobel laureate Milton Friedman, “long and variable lags.” As a result, most economists agree that the Federal Reserve should not attempt to “fine tune” the economy by responding to each government release of macroeconomic data. Nevertheless, in practice, it’s clear that during times when Fed policymakers are split over what course of action to take, a single data report can have a significant effect on their decision.
The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).
The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.7 percent in September, up from 3.4 percent in August.
The core inflation rate,which excludes the prices of food and energy, was 2.6 percent in September, up from 2.4 percent in August.
Headline inflation and core inflation were both higher than the forecasts of economics surveyed by the Wall Street Journal. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)
In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline inflation (the blue line) soared to 8.1 percent in September, up from 4.9 percent in August. Core inflation (the red line) was 4.1 percent in September, up from 3.5 percent in August.
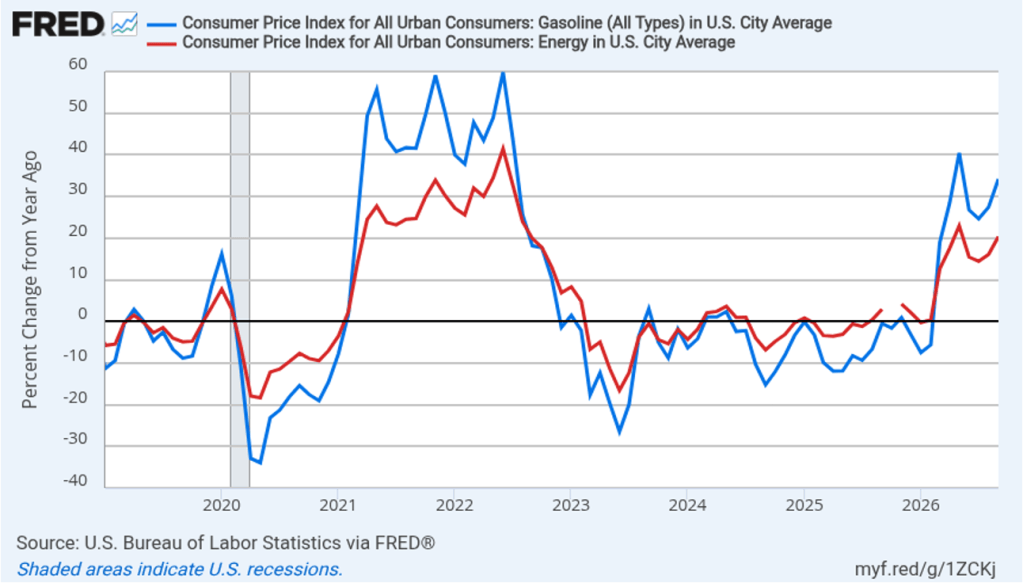
As the large gap between the headline and core 1-month inflation rates indicates, energy prices, particularly gasoline prices, rose sharply in September. In the following figure, the red line shows the 12-month inflation rate in all energy prices included in the CPI. Inflation in energy prices was 20.4 percent in September, up from 16.4 percent in August. The blue line shows the 12-month inflation rate in gasoline prices, which increased to 34.2 percent in September from 27.4 percent in August.
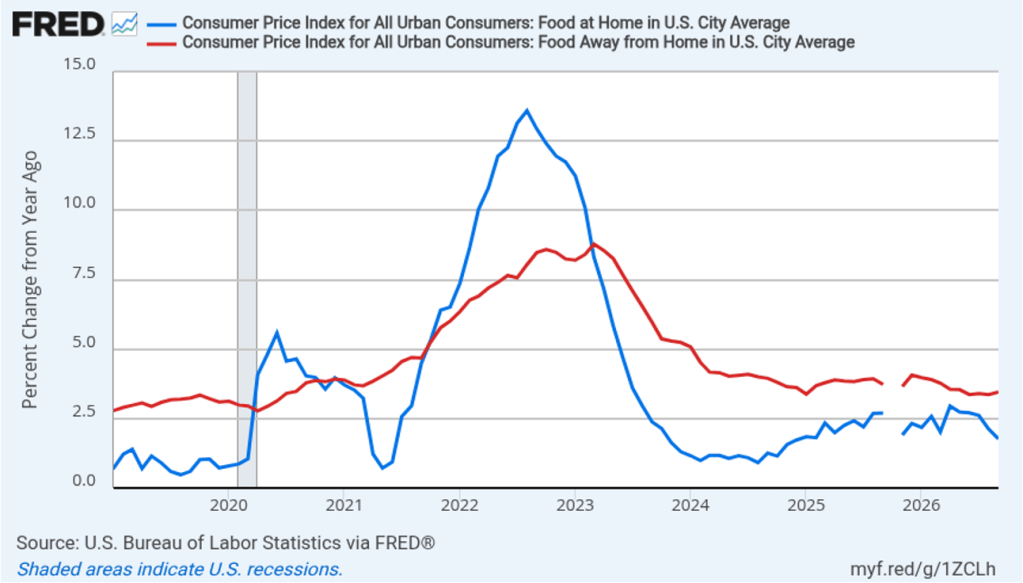
There has been a fear that the rise in energy prices that began in March will pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 12-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and in the category “food away from home” (the red bar)—primarily food purchased at restaurants. Grocery prices increased 3.5 percent in September from a year ago, down from 3.7 percent in August. Restaurant prices increased 3.5 percent from a year ago, up slightly from 3.4 percent in August. To this point, increases in energy prices seem to have had some effect on grocery prices and restaurant prices, although the extent of the effect is unclear.
Fed Chair Kevin Warsh has indicated that he favors measures of the inflation rate that exclude particularly small or particularly large changes in the prices of some goods or services—so-called outliers. Median CPI, which is compiled monthly by economists at the Federal Reserve Bank of Cleveland, is calculated by ranking the price changes of every good or service in the index from the largest price change to the smallest price change, and then choosing the price change in the middle. The idea is to eliminate the effect on measured inflation of any short-lived events that cause the prices of some goods and services to be particularly high or particularly low. Economists at the Cleveland Fed have conducted research that shows that, in their words, “the median CPI provides a better signal of the underlying inflation trend than either the all-items CPI or the CPI excluding food and energy. The median CPI is even better at forecasting [personal consumption expenditures] PCE inflation in the near and longer term than the core PCE price index.”
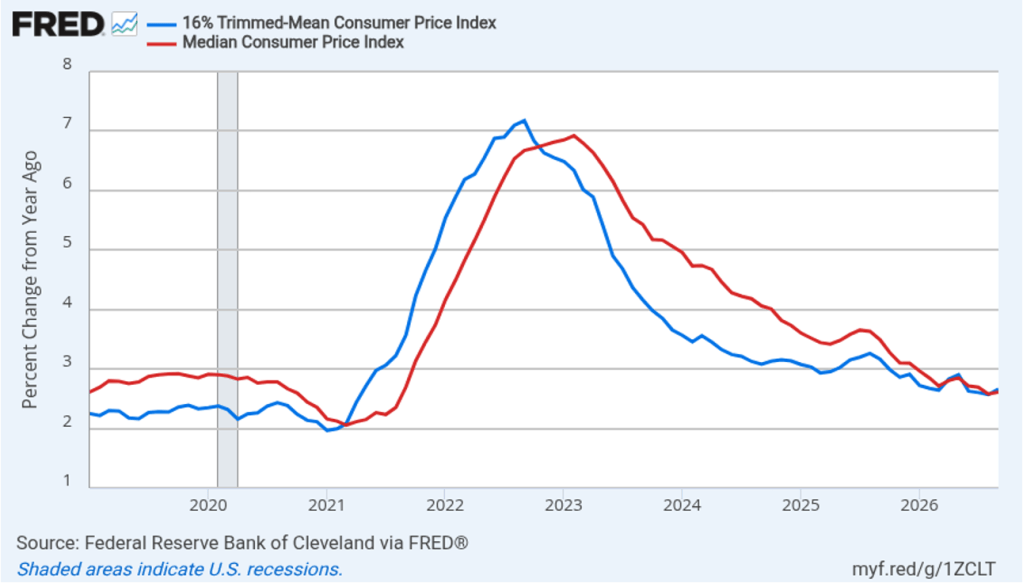
Trimmed-mean inflation, also compiled by economists at the Cleveland Fed, excludes the highest 8 percent of price changes and the lowest 8 percent. The following figure shows 12-month trimmed mean (the blue line) and median (the red line) CPI inflation. Trimmed-mean inflation was 2.7 percent in September, up from 2.6 percent in August. Median inflation was 2.6 percent in September, unchanged from August. So these measures of inflation are both lower than the conventional headline and core CPI inflation measures, which indicates that the acceleration in inflation during September was not affecting all sectors of the economy.
Note that the Fed uses the 12-month change in the personal consumption expenditures (PCE) price index, not the change in the CPI, when gauging whether it is hitting its 2 percent annual inflation target. Historically, PCE inflation has been about 0.4 percentage points to 0.5 percentage points lower than CPI inflation. The Bureau of Economic Analysis (BEA) won’t release its estimate of September PCE inflation until October 29, one day after the next FOMC meeting.
Today’s report showing that inflation remains persistently above the Fed’s 2 percent annual target has likely raised the chance that Federal Reserve policymakers will increase their target range for the federal funds rate from the current 3.75 percent to 4.00 percent by o.25 percentage points (or 25 basis points) at the next meeting of the FOMC on October 27–28. Trading in the federal funds futures market this afternoon indicates that investors assign a 33.8 percent probability to the FOMC raising its target range at that meeting, which is up from a 22.1 percent probability yesterday. Trading indicated that investors assign a 89.7 percent probability to the committee increasing its target range by at least 25 basis points at its last meeting of the year on December 8–9. Some analysts have speculated that the committee will postpone its next rate increase until December to avoid raising the rate before the midterm election on November 3.
Today’s report from the Bureau of Labor Statistics (BLS) on the consumer price index (CPI) for August was eagerly awaited by economists and policy analysts. As we discuss in Macroeconomics, Chapter 15 (Economics, Chapter 25), monetary policy affects the economy with, in the words of Nobel Laureate Milton Friedman, “long and variable lags.” As a result, most economists agree that the Federal Reserve should not attempt to “fine tune” the economy by responding to each government release of macroeconomic data.
There are some instances, however, including the present, when the Fed’s policymaking Federal Open Market Committee (FOMC) appears to be uncertain as to whether a change in policy is needed. As a result, there was a widespread expectation that if today’s report indicated that inflation is slowing, the FOMC would likely leave its target for the federal funds rate unchanged at its meeting on Tuesday and Wednesday of next week. But if the report didn’t indicate that inflation is slowing, the committee would likely raise its target. The report gave few indications that inflation is slowing.
The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).
The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.4 percent in August, the same as in July.
The core inflation rate,which excludes the prices of food and energy, was 2.4 percent in August, down from 2.5 in July.
Headline inflation was slightly higher, and core inflation was equal, to the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)
In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline (the blue line) was 4.6 percent In August, up from 0.9 percent in July. Core inflation (the red line) was 3.5 percent in August, up from 2.6 percent in July.
The following figure illustrates the role played by energy prices in contributing to the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had declined at an annual rate of 16.4 percent in July, increased at an annual rate of 28.3 percent in August. The blue line shows the 1-month inflation rate in gasoline prices, which had declined at an annual rate of 29.4 percent in July, increased at an annual rate of 58.3 percent in August.
There had been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and in the category “food away from home” (the red bar)—primarily food purchased at restaurants. Grocery prices, which had declined at annual rate of 0.9 percent in July, increased at an annual rate of 0.4 percent in August. Food prices away from home increased 3.1 percent in August, down from 3.9 percent in July. To this point, increases in energy prices seem to have had some effect on grocery prices and restaurant prices, although the extent of the effect is unclear.
Fed Chair Kevin Warsh has indicated that he favors measures of the inflation rate that exclude particularly small or particularly large changes in the prices of some goods or services—so-called outliers. Median CPI, which is compiled monthly by economists at the Federal Reserve Bank of Cleveland, is calculated by ranking the price changes of every good or service in the index from the largest price change to the smallest price change, and then choosing the price change in the middle. The idea is to eliminate the effect on measured inflation of any short-lived events that cause the prices of some goods and services to be particularly high or particularly low. Economists at the Cleveland Fed have conducted research that shows that, in their words, “the median CPI provides a better signal of the underlying inflation trend than either the all-items CPI or the CPI excluding food and energy. The median CPI is even better at forecasting [personal consumption expenditures] PCE inflation in the near and longer term than the core PCE price index.”
Trimmed-mean inflation, also compiled by economists at the Cleveland Fed, excludes the highest 8 percent of price changes and the lowest 8 percent. The following figure shows 1-month trimmed mean (the blue line) and median (the red line) CPI inflation. Trimmed-mean inflation was 2.7 percent in August, unchanged from July. Median inflation was 2.1 percent in August, down from 3.1 percent in July. So these measures of inflation are both lower than the conventional headline and core CPI inflation measures, although as the figure shows, both measures are volatile.
Note that the Fed uses the 12-month change in the personal consumption expenditures (PCE) price index, not the change in the CPI, when gauging whether it is hitting its 2 percent annual inflation target. Historically, PCE inflation has been about 0.4 percentage points to 0.5 percentage points lower than CPI inflation. The Bureau of Economic Analysis (BEA) won’t release its estimate of August PCE inflation until September 30, after the next FOMC meeting.
Today’s report showing that inflation remains persistently above the Fed’s 2 percent annual target, following last week’s jobs report showing an unexpectedly large increase in employment, has likely raised the chance that Federal Reserve policymakers will increase their target range for the federal funds rate from the current 3.50 percent to 3.75 percent by o.25 percentage points (or 25 basis points) at the next meeting of the FOMC on September 15–16. Trading in the federal funds futures market this afternoon indicates that investors assign a 86.5 percent probability to the FOMC raising its target range at that meeting, which is up from a 72.4 probability yesterday. Trading indicated that investors assign a 74.5 percent probability to the committee increasing its target range by at least 50 basis points by the end of the year, up from 64.6 percent yesterday and from 44.7 percent one week ago.
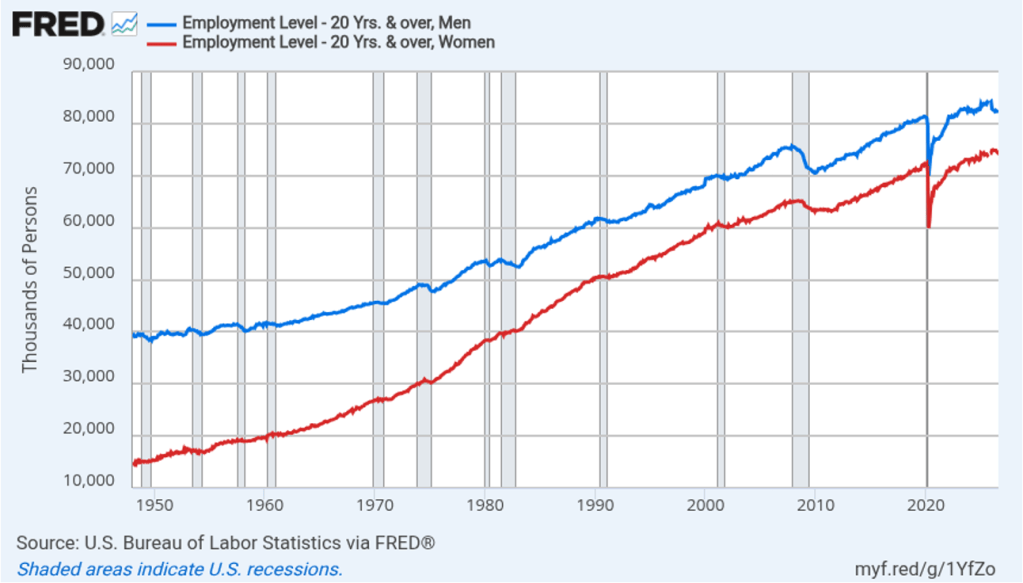
On this Labor Day, we look at an important issue: In recent years, women have been faring better than men in the job market. The following figure shows that, for workers 20 years and older, men still hold more jobs than women do, but the gap has been closing. For example, as measured by the household survey conducted by the Bureau of Labor Statistics (BLS), between January 2022 and August 2026, there was a net increase of 5,829,000 jobs in the United States. More than two thirds of those jobs were filled by women.
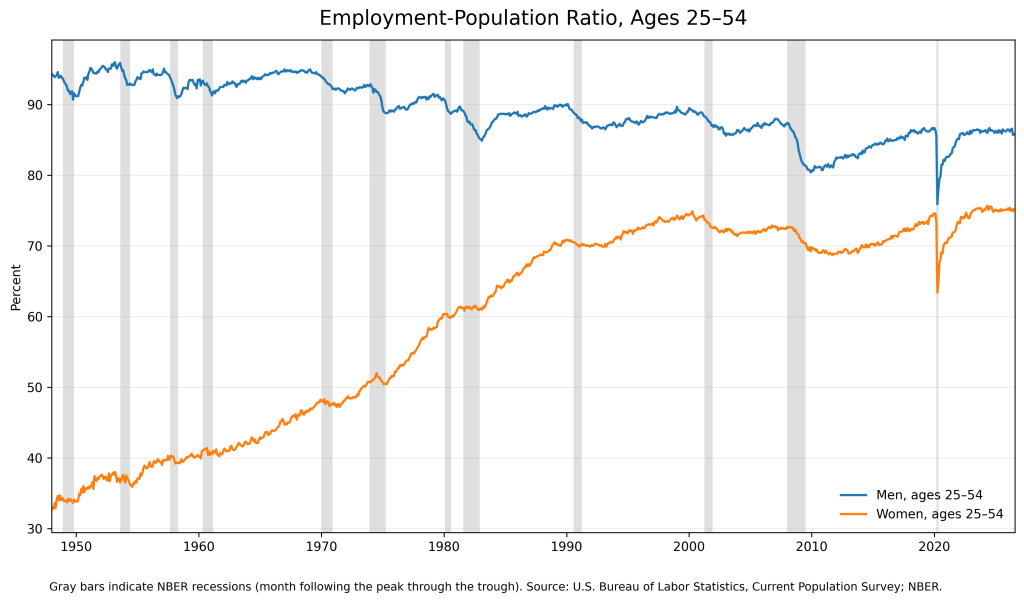
In recent months, the business press has begun to focus on this issue. Here are some recent headlines: “A Changing Job Market Leans Against Men,” “In This Job Market, Women Have the Upper Hand,” and “Young Men Are Abandoning the Workforce.” In Macroeconomics, Chapter 9 (Economics, Chapter 19), we discuss the employment-population ratio, which measures the fraction of the working-age population of a particular segment of the population that is employed. The following figure shows that the employment-population ratio for prime-age men—those aged 25 to 54—has been slowly trending downward for decades (the blue line), while that ratio has generally been increasing for women (the orange line).
In March 1953, the employment-population ratio for prime-age males reached a peak of 96.0 percent. In August 2026, the ratio was 85.8 percent. If prime-age males were working in 2026 at the rate that they did in 1953, 10 million more men would be working today than actually are.
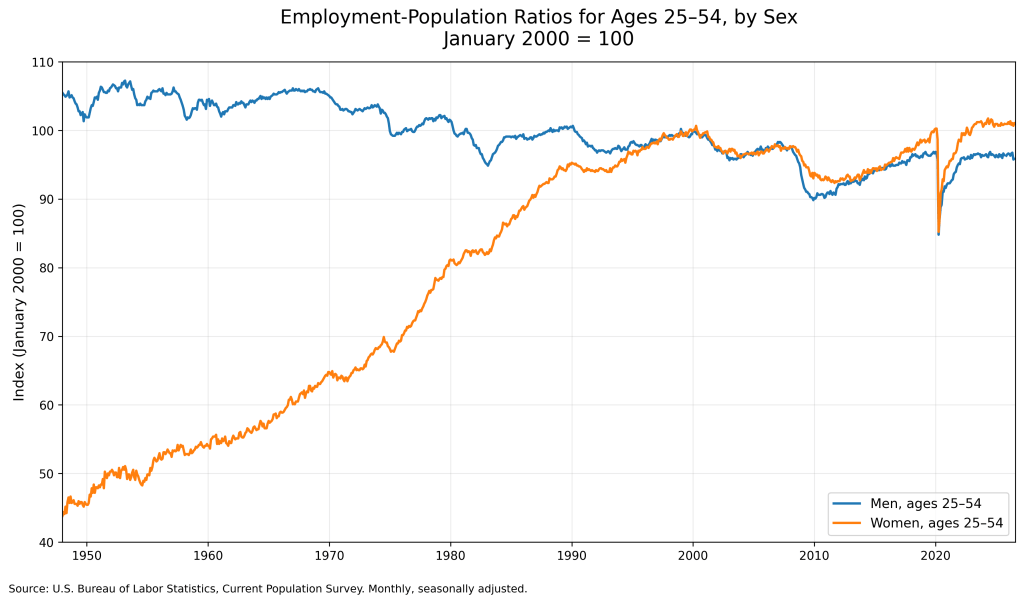
The following figure makes clearer the differing trends in men and women’s employment-population ratio in recent years. In this figure, the values for both ratios are set equal to 100 in January 2000. Since that time the employment-population ratio for prime-age women (the orange line) has increased by 1.1 percent, while the ratio for men (the blue line) has declined by 4.1 percent.
Why do a smaller fraction of prime-age men have jobs today than in the past? A large number of explanations have been offered, both in the business media and by academic economists. One key factor, as shown in the following figure, is that women (the orange line) are now more likely to earn a college degree than are men (the blue line).
The fraction of jobs requiring a four-year degree has been increasing over time, a trend that the BLS projects will continue. As the following figure shows, men with a bachelor’s degree or more have a higher employment-population ratio than do men with only a high school degree. (Note that the data in this figure are for all men 25 years and older, not just for prime-age men. The average age of men has been rising, which lowers the employment-population ratio as an increasing fraction of men become of retirement age. These data are not available on a seasonally-adjusted basis, which accounts for the choppiness in the figure.) As men have fallen behind in earning college degrees, more men have found themselves unqualified to be hired in some jobs.
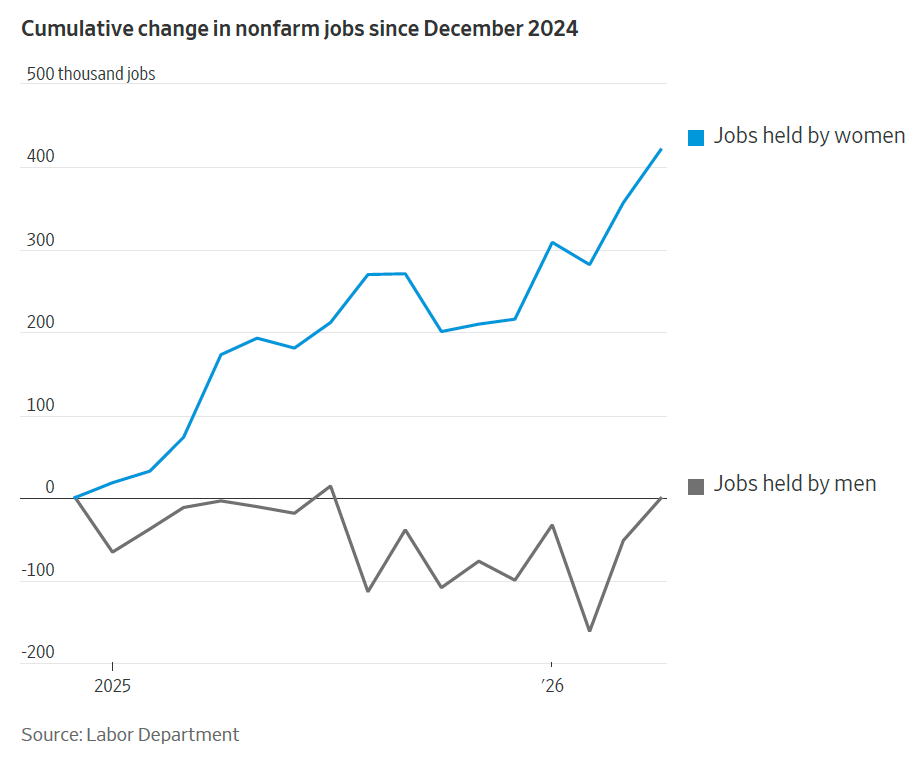
An article in the Wall Street Journal used BLS data to divide jobs primarily held by women and those primarily held by men. As the following figure from the article shows, jobs help primarily by women have been increasing faster than those held by men.
Image generated by ChatGPT
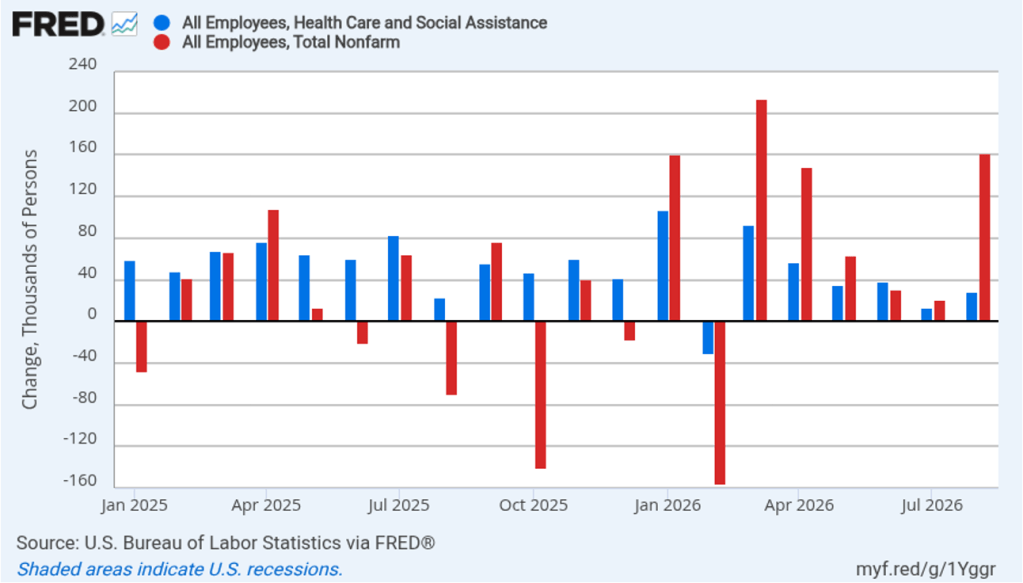
As we noted in a blog post earlier this year, health care jobs have come to dominate U.S. employment growth. The following figure shows monthly changes in health care and social assistance jobs (the blue bars) and monthly changes in total employment (the red bars) for each month since January 2025. During this time period, net employment in health care and social assitance increased by 1,027,300 jobs. All other job categories experienced a decrease of 268,300 jobs. Women account for 77.9 percent of health care and social assistance workers. In other words, the number of jobs in industries dominated by men have been declining.
Image generated by ChatGPT
If you look again at the graph showing changes in the employment-population ratio for prime-age men (the second graph in this blog post), you’ll notice that there seems to be a ratchet effect in the data: The employment-population ratio declines during each recession (shown by the gray bars in the figure) and then struggles to return to its pre-recession level. It’s unsurprising that the male employment-population falls sharply during recessions, because, as we discuss in Macroeconomics, Chapter 13 (Economics, Chapter 23) spending on residential construction and consumer durables, such as automobiles and appliances, falls sharply during a recession.In 2025, men were 86.8 percent of workers in construction and 77.9 percent of workers in manufacturing. (In fact, as we note in that chapter, the late Edward Leamer of the University of California, Los Angeles, went so far as to argue that “housing is the business cycle.”)
Image generated by ChatGPT
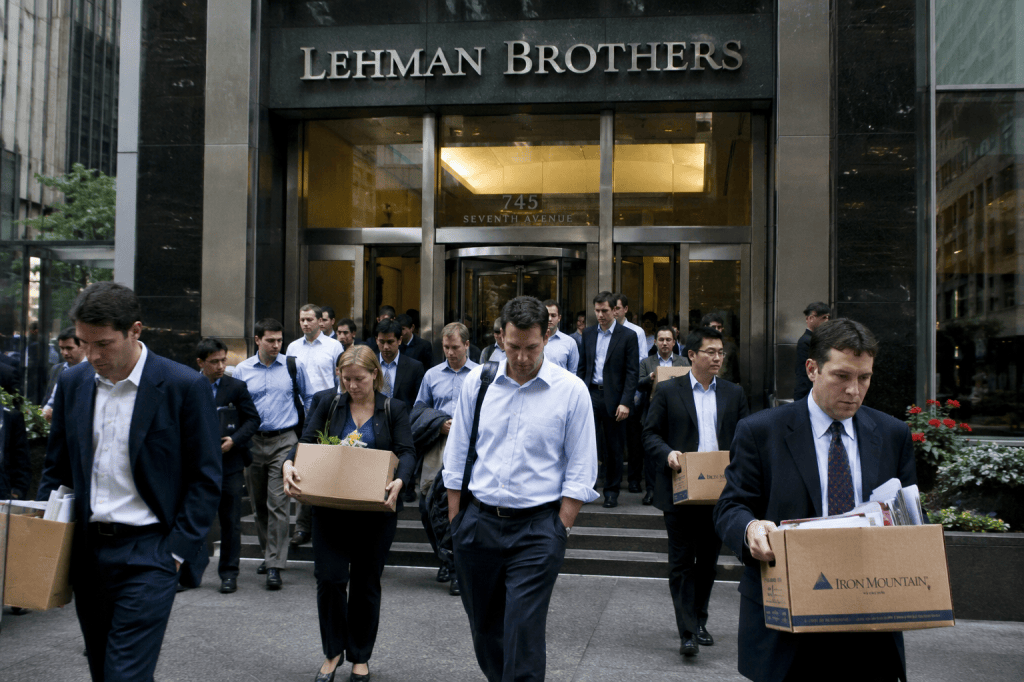
Just before the Great Recession and Global Financial Crisis of 2007–2009, the prime-age male employment-population ratio was 88.0 percent, a level it hasn’t attained since. (In a recent blog post, we discuss the role the bankruptcy of the Lehman Brothers investment bank played in the financial crisis.) The prolonged unemployment experienced by some male workers in construction and manufacturing may have led to their skills deteriorating, making it more difficult for them to find employment during the following economic recovery. Some of these workers may have dropped out of the labor force resulting in a decline in the employment-population ratio.
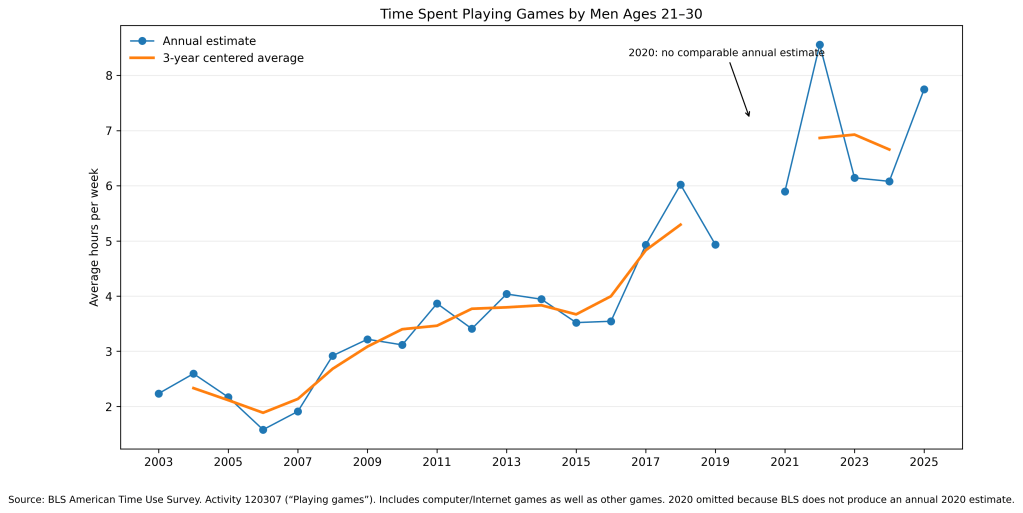
One explanation for the declining employment-population ratio for prime-age males that has received significant attention in the media is the increased appeal of video games. Or, as the headline of an article in the New York Times put it: “Why Some Men Don’t Work: Video Games Have Gotten Really Good.” The U.S. Census Bureau annually conducts the American Time Use Survey, which is published by the BLS. The following figure shows that young adult men have increased the time they spend playing games. In 2003, men aged 21 to 30 spent an average of 2.23 hours per week. In 2025, they spent an average of 7.75 hours per week, down from a peak of 8.56 hours per week in 2022.
Mark Aguiar, of Princeton University, and colleagues argue that the increase in time young men devote to playing video games and engaging in other “recreational computer activities” has significantly reduced the amount of hours that some young men work. There has, however, been an academic debate over this contention. First, it’s unclear which way the causality runs: Do young men work less because they find playing video games particularly attractive or has the ability of young men to find jobs declined, so they spend time playing video games that they would rather spend working? Second, older prime-age males, who have not increased their time playing video games by as much, have also experienced a falling employment-population ratio.
There have been a number of other changes in labor markets and in American society that may have contributed to the decline in employment of prime-age males. ChatGPT offers the following summary of the various factors:
“I would rank the explanations this way:
Most important: the disappearance of stable, comparatively well-paid routine and manual jobs available to men without college degrees, together with slow occupational and geographic adjustment.
Closely related: educational and skills differences, the concentration of new employment in female-heavy service sectors, and the difficulty men face moving into those jobs.
Important amplifiers: chronic health problems, mental illness, pain, opioids and other substance abuse, and the long-term effects of recessions and prolonged joblessness.
Important for particular groups: criminal records, incarceration, geographic isolation, and weak local labor markets.
Reinforcing social mechanisms: delayed marriage and parenthood, living with relatives, weaker social expectations concerning steady work, and reduced connection to employers and communities.
Real but often overstated: disability benefits, other public assistance, and video games.
The central academic message is therefore different from the most sensational press version. It is not principally that millions of otherwise successful men suddenly preferred video games or welfare to jobs. The decline began with a weakening of the kinds of labor-market opportunities historically available to noncollege men. Health, addiction, criminal records, family change, geographic immobility, and more attractive leisure then made the resulting withdrawal from employment more persistent.”
This morning (September 4), the Bureau of Labor Statistics (BLS) released its “Employment Situation” report (often called the “jobs report”) for August. The report showed an unexpectedly large increase in employment.
The jobs report has two estimates of the change in employment during the month: one estimate from the establishment survey, often referred to as the payroll survey, and one from the household survey. As we discuss in Macroeconomics, Chapter 9, Section 9.1 (Economics, Chapter 19, Section 19.1), many economists and Federal Reserve policymakers believe that employment data from the establishment survey provide a more accurate indicator of the state of the labor market than do the household survey’s employment and unemployment data. (The groups included in the employment estimates from the two surveys are somewhat different, as we discuss in this post.)
According to the establishment survey, there was a netincreaseof 162,000 nonfarm jobs during August. Economists surveyed by the Wall Street Journal had forecast an increase of only 55,000 jobs. Economists surveyed by FactSet had forecast a net increase of 65,000 jobs. The BLS revised upward its previous estimates of employment in June and July by a combined 55,000 jobs. The estimate of the net employment change in July was revised from a decrease of 23,000 to an increase of 21,000. (The BLS notes that: “Monthly revisions result from additional reports received from businesses and government agencies since the last published estimates and from the recalculation of seasonal factors.”)
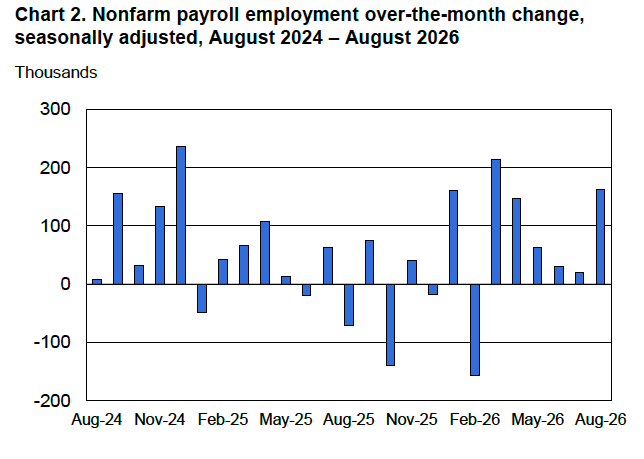
The following figure from the jobs report shows the net change in nonfarm payroll employment for each month in the last two years. The figure shows that since peaking in March with a net increase of 214,000 jobs, job growth slowed markedly over the following four months until strongly rebounding in August. In 2026, monthly net employment growth has averaged 80,375. That is much higher than the 2025 average monthly employment growth of only 9,667, but well below the 2024 average monthly employment growth of 121,583.
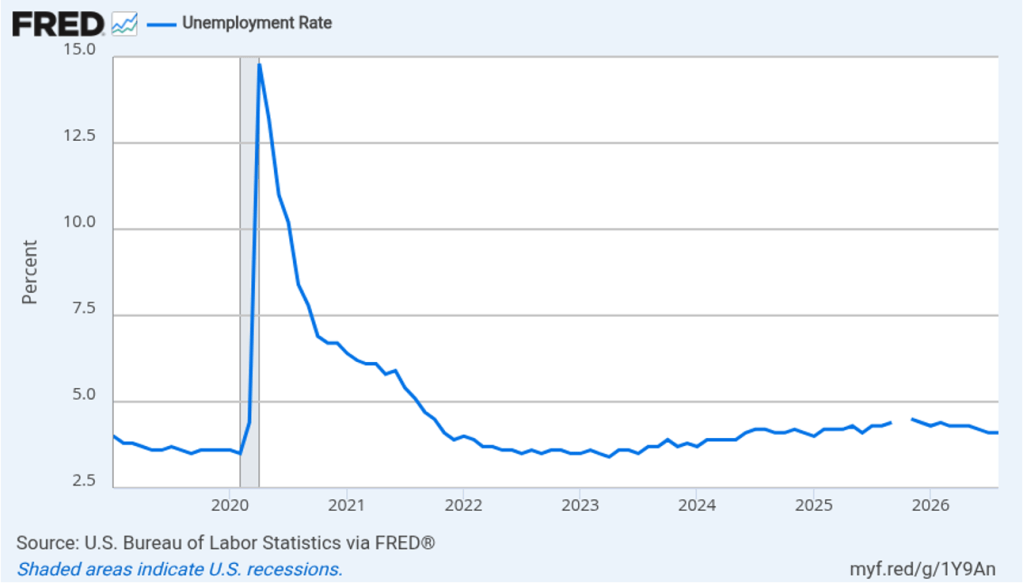
The unemployment rate, which is calculated from data in the household survey, was 4.1 percent, unchanged from July. The estimated size of the labor force, the number of workers employed, and the number of workers unemployed all increased in August. The following figure shows that the unemployment rate has been remarkably stable over the past year and a half, staying between 4.0 percent and 4.4 percent in each month since June 2024. The Federal Open Market Committee’s most recent estimate of the natural rate of unemployment—the normal rate of unemployment over the long run—is 4.2 percent. So, currently the unemployment rate is slightly below that estimate of the natural rate. (We discuss the natural rate of unemployment in Macroeconomics, Chapter 9 and Economics, Chapter 19.)
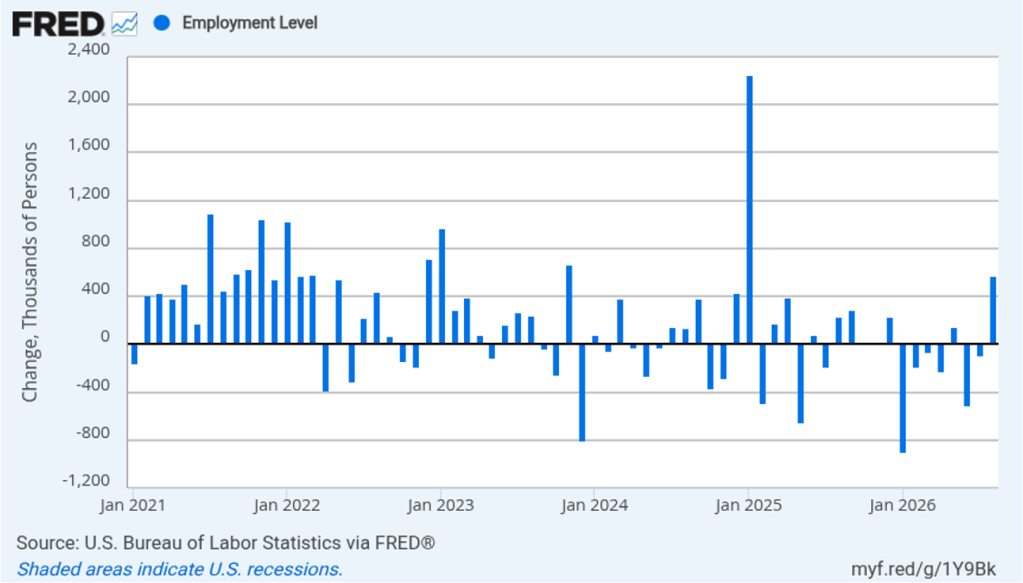
As the following figure shows, the monthly net change in jobs from the household survey moves much more erratically than does the net change in jobs from the establishment survey. As measured by the household survey, there was a net increase of 569,000 jobs in August, far larger than the net increase in employment shown in the establishment survey. Since January, the household survey has shown a net increase in jobs in only two months, with a total net decrease of 326,000 jobs over the period. In contrast, the establishment survey has shown a net increase of 643,000 jobs over the same period. (Note that because of last year’s shutdown of the federal government, there are no data for October or November.)
The household survey has another important labor market indicator: the employment-population ratio forprime age workers—those workers aged 25 to 54. In August, the ratio was 80.4 percent, unchanged from July. The prime-age population ratio can show volatility from month to month but has remained above 80 percent every month since December 2022.
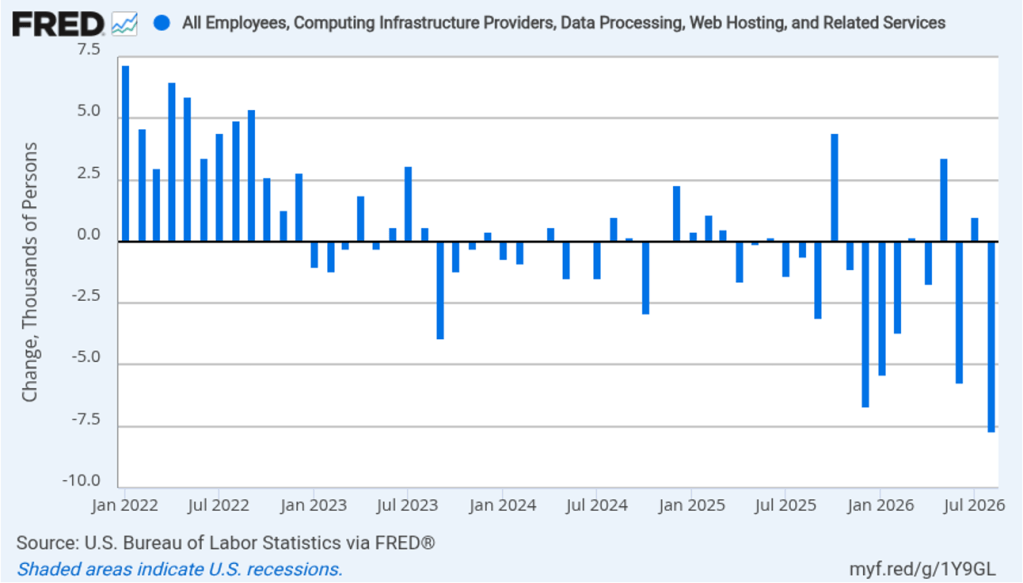
The rapid adoption of artificial intelligence (AI) by many firms has led to forecasts of substantial layoffs of workers in information systems. The following figure shows net employment changes in the BLS employment category of “computing infrastructure providers, data processing, web hosting, and related services.” Employment in this sector has been declining during most months since the beginning of 2023. In August, there was a net decrease of 7,700 jobs.
The establishment survey also includes data on average hourly earnings (AHE). As we noted in earlier posts, many economists and policymakers believe the employment cost index (ECI) is a better measure of wage pressures in the economy than is AHE. AHE does have the important advantage of being available monthly, whereas the ECI is only available quarterly. The following figure shows the percentage change in AHE from the same month in the previous year. AHE increased 3.1 percent in August, down from 3.2 percent in July. That was the smallest increase since May 2021. The rate of increase in AHE has been below 4.0 percent each month since August 2025, indicating that cost pressure from wage increases has not been a significant source of price inflation during the past year.
With inflation having been above the Federal Reserve’s 2 percent annual target every month since March 2021, there has been an expectation that the Fed’s policymaking Federal Open Market Committee (FOMC) would increase its target for the federal funds rate at least once before the end of 2026. At the FOMC’s last meeting in late July, three members of the committee voted to increase the target, an unusual amount of dissent from a committee decision.
Do today’s surprisingly strong employment data increase the chance that the FOMC will raise its target range for the federal funds rate at its next meeting on September 15–16? Investors in the federal funds futures market believe that the answer is “yes.” Yesterday, trading in the federal funds futures market indicated that investors assigned a 49.4 percent probability to the committee increasing its target range by 0.25 percentage points (25 basis points) at that meeting. This afternoon, that probability had increased to 58.4 percent. The probability that the committee will have increased its target range by at least 25 basis points from its current range of 3.50 percent to 3.75 percent after its meeting on October 27–28 increased from 62.8 percent yesterday to 69.4 percent this afternoon.
The BLS will release its estimate of inflation as measured by the consumer price index next Friday. That report will provide further evidence on the current state of inflation and may have a significant effect on the decision the FOMC makes at its meeting the following week.
Today (August 12), the Bureau of Labor Statistics (BLS) released its report on the consumer price index (CPI) for July. Lower energy and grocery prices contributed to a slight decline in the inflation rate in July compared with June.
The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).
The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.4 percent in July, down from 3.5 percent in June.
The core inflation rate,which excludes the prices of food and energy, was 2.5 percent in July, down from 2.6 in June.
Headline inflation and core inflation were both equal to the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)
In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, both headline (the blue line) and core inflation (the red line) increased in July from the negative values in June. That is, the U.S. economy experienced deflation in June because the price level, measured by the CPI and by the CPI less food and energy prices, fell in that month.
In July, 1-month headline CPI inflation was 0.9 percent and 1-month core CPI inflation was 2.6 percent.
The following figure illustrates the role played by energy prices in contributing to the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had increased at annual rate of 245 percent in March, declined at an annual rate of 16.4 percent in July. The blue line shows the 1-month inflation rate in gasoline prices, which in March had spiked to more than 900 percent measured at an annual rate, declined at an annual rate of 29.4 percent in July. A return to full-scale hostilities in the Middle East would increase oil prices, which would likely lead to an increase in the U.S. inflation rate.
There had been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and the category “food away from home” (the red bar)—primarily food purchased at restaurants. Inflation in grocery prices, which increased 2.3 percent in June, declined 0.9 percent in July. Inflation in food prices away from home increased from 2.8 percent in June to 3.8 percent in July. To this point, increases in energy priced do not seem to have caused a significant increase in either grocery prices or restaurant prices.
Today’s relatively good inflation report, following last week’s report showing an unexpected decline in employment, has likely reduced the chance that Federal Reserve policymakers will increase their target for the federal funds rate at the next meeting of the Federal Open Market Committee (FOMC) on September 15–16. In trading in the federal funds futures market this afternoon, investors assigned a 62.1 percent probability to the FOMC keeping its target unchanged at that meeting, which was up from a 51.6 probability yesterday. Traders assign a 53.2 percent probability to the committee increasing its target at its October 27–28 meeting, down from 62.2 percent yesterday.
It’s worth noting, however, that inflation is still running above the Federal Reserve’s 2 percent annual inflation target. In testimony before Congress in a hearing on his nomination as Fed Chair, Kevin Warsh cautioned that good news in a single month’s inflation report should be treated with caution. Warsh has intentionally moved away from discussing the circumstances under which monetary policy might change in the future—so-called forward guidance. (We discuss forward guidance in Macroeconomics, Chapter 15 (Economics, Chapter 25)). Uncertainty about actions the FOMC may take during its three remaining meeting this year remains high.
This morning (August 7), the Bureau of Labor Statistics (BLS) released its “Employment Situation” report (often called the “jobs report”) for July. The report showed a decline in employment.
The jobs report has two estimates of the change in employment during the month: one estimate from the establishment survey, often referred to as the payroll survey, and one from the household survey. As we discuss in Macroeconomics, Chapter 9, Section 9.1 (Economics, Chapter 19, Section 19.1), many economists and Federal Reserve policymakers believe that employment data from the establishment survey provide a more accurate indicator of the state of the labor market than do the household survey’s employment and unemployment data. (The groups included in the employment estimates from the two surveys are somewhat different, as we discuss in this post.)
According to the establishment survey, there was a net decrease of 23,000 nonfarm jobs during July. Economists surveyed by the Wall Street Journal had forecast an increase of 83,000 jobs. Economists surveyed by FactSet had forecast a higher net increase of 100,000 jobs. The BLS revised downward its previous estimates of employment in May and June by a combined 103,000 jobs. (The BLS notes that: “Monthly revisions result from additional reports received from businesses and government agencies since the last published estimates and from the recalculation of seasonal factors.”)
The following figure from the jobs report shows the net change in nonfarm payroll employment for each month in the last two years. The figure shows that since peaking in March with a net increase of 214,000 jobs, job growth has slowed markedly over the last four months. Over the last three months, we’ve seen only an average of 20,000 net new jobs created.
The slow pace of recent job growth is consistent with the view among some economists that slowing labor force growth has driven the break-even rate of employment growth—the rate required to keep the unemployment rate constant—down to nearly zero
Despite the decrease in employment in July, the unemployment rate, which is calculated from data in the household survey, declined to 4.1 percent from 4.2 percent in June. The decline in the unemployment rate was due to a decline in the estimated size of the labor force. Although the estimated size of the labor force can fluctuate significantly from month to month, July was the fifth month in a row during which the labor force is estimated to have declined. Despite that fact, as the following figure shows, the unemployment rate has been remarkably stable over the past year and a half, staying between 4.0 percent and 4.4 percent in each month since June 2024. The Federal Open Market Committee’s current estimate of the natural rate of unemployment—the normal rate of unemployment over the long run—is 4.2 percent. So, currently the unemployment rate is slightly below that estimate of the natural rate. (We discuss the natural rate of unemployment in Macroeconomics, Chapter 9 and Economics, Chapter 19.)
As the following figure shows, the monthly net change in jobs from the household survey moves much more erratically than does the net change in jobs from the establishment survey. As measured by the household survey, there was a net decrease of 87,000 jobs in July, roughly similar to the net decrease in employment shown in the establishment survey. Since January, the household survey has sown a net increase in jobs in only one month, with a total net decrease of 1.8 million jobs. In contrast, the establishment survey has shown a net increase of 426,000 jobs over the same period. (Note that because of last year’s shutdown of the federal government, there are no data for October or November.)
The household survey has another important labor market indicator: the employment-population ratio forprime age workers—those workers aged 25 to 54. In July, the ratio increased to 80.4 percent, partially reversing the sharp decline in June. The prime-age population ratio can show volatility from month to month but has remained above 80 percent every month since December 2022.
There have been media reports of firms, including Salesforce, Cloudflare, Coinbase, Cisco Systems, and Meta Platforms, laying off workers in information systems. The following figure shows net employment changes in the BLS employment category of “computing infrastructure providers, data processing, web hosting, and related services.” Employment in this sector has been declining during most months since the beginning of 2023. July was an exception with a net increase of 2,400 jobs.
The establishment survey also includes data on average hourly earnings (AHE). As we noted in earlier posts, many economists and policymakers believe the employment cost index (ECI) is a better measure of wage pressures in the economy than is AHE. AHE does have the important advantage of being available monthly, whereas the ECI is only available quarterly. The following figure shows the percentage change in AHE from the same month in the previous year. AHE increased 3.2 percent in July, down from 3.4 percent in June. The rate of increase in AHE has been below 4.0 percent each month since August 2025, indicating that cost pressure from wage increases has not been a significant source of price inflation during the past year.
With inflation having been above the Federal Reserve’s 2 percent annual target every month since March 2021, there has been increasing speculation that the Fed’s policymaking Federal Open Market Committee (FOMC) would increase its target for the federal funds rate at least once before the end of 2026. At the FOMC’s last meeting in late July, three members of the committee voted to increase the target, an unusual amount of dissent from a committee decision.
Does the slowdown in employment growth in recent months reduce the chance that the FOMC will increase its target range for the federal funds rate at its next meeting on September 15–16? Investors in the federal funds futures market believe that the answer is “yes.” Yesterday, investors assigned only a 45.0 percent probability to the committee keeping its target rate unchanged. This afternoon, that probability had increased to 55.9 percent. The BLS will release its estimate of inflation as measured by the consumer price index next Wednesday. That report will provide further evidence about the current state of inflation.
Today (July 14), the Bureau of Labor Statistics (BLS) released its report on the consumer price index (CPI) for June. In May, higher energy prices caused by the conflict in Iran contributed to inflation increasing to the highest rate in more than three years. In June, as energy prices decreased, inflation experienced the largest one-month decrease since April 2020.
The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).
The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.5 percent in June, down from 4.2 percent in May.
The core inflation rate,which excludes the prices of food and energy, declined from 2.8 percent in May to 2.6 percent in June.
Headline inflation and core inflation were both well below the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October and November 2025 are not available.)
In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, both headline (the blue line) and core inflation (the red line) were negative in June. That is, the U.S. economy experienced deflation last month because the price level, measures by the CPI and by the CPI less food and energy prices, fell in June.
The following figure illustrates the role played by energy prices in causing the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had increased at annual rate of 245 percent in March, fell at annual rate of 50.6 percent in June. The blue line shows the 1-month inflation rate in gasoline prices, which in March had spiked to more than 900 percent measured at an annual rate, fell at an annual rate of 70.6 percent in June. The recent escalation in the conflict in Iran has increased oil prices, which will likely lead to an increase in the inflation rate in July.
There has been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and the category “food away from home” (the red bar)—primarily food purchased at restaurants. Inflation in grocery prices increased from 0.8 percent in May to a still fairly low 2.3 percent in June. Inflation in food prices away from home fell from 3.7 percent in May to 2.8 percent in June. To this point, increases in energy priced do not seem to have had much effect on grocery prices or on restaurant prices.
The unexpectedly large decline in inflation in today’s report has likely reduced the chance that Federal Reserve policymakers will increase their target for the federal funds rate at the next meeting of the Federal Open Market Committee (FOMC) on July 28–29. In trading in the federal funds futures market this morning, investors assigned a 83.4 percent probability to the FOMC keeping its target unchanged, which was up sharply from a 58.3 probability yesterday. Traders assign a 61.3 percent probability to the committee increasing its target at its September 15–16 meeting, down from 75.1 percent yesterday.
In testimony before Congress today after the CPI report was released, Fed Chair Kevin Warsh cautioned that good news in a single month’s inflation report should be treated with caution: “There might be some who look at today’s data and say ‘mission accomplished.’ That is not my view.”