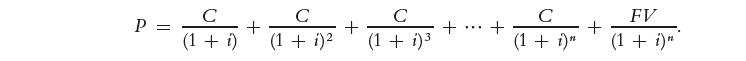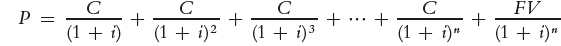Did Seattle Succeed in Raising the Monthly Pay of Gig Drivers?

Supports: Microeconomics and Economics, Chapter 16, Section 16.4.
Image created by ChatGPT

Regulations don’t always have the effect that policymakers hope they will. In 2022, the Seattle City Council unanimously passed the App-Based Worker Minimum Payment (ABWMP) ordinance, which took effect in January 2024. Most app-based (or gig) workers who deliver for DoorDash, Uber Eats, or Grubhub are independent contractors rather than employees of those companies. The ordinance was intended to raise the compensation of these workers by requiring that they receive a minimum payment for each delivery based on the time they worked and the distance they traveled. The intention was for gig workers to receive compensation similar to the minimum wage that hourly workers receive.

In December 2025, a research paper by Yuan An, Andrew Garin, and Brian Kovak of Carnegie Mellon University concluded that the ordinance was not having its intended effect. They found that for experienced (or “highly attached”) drivers, “the ordinance increased pay per delivery, but decreased the number of delivery tasks completed per month” and, as a result, there was “
no effect on total delivery earnings among highly attached workers after the first month.” The authors note that “free entry [of drivers in the gig delivery market] plays an important role” in their results and that “the equilibrium value of doing delivery work must always remain equal to the fixed, constant outside option available to all workers.”

a. What effect would we expect Seattle enacting a regulation increasing the pay per delivery for gig delivery drivers to have on the number of gig delivery drivers working in Seattle?

b. Explain the reasoning behind the authors’ statement that “the equilibrium value of doing delivery work must always remain equal to the fixed, constant outside option available to all workers.”

c. Use your answers to parts (a) and (b) to explain why the authors found that the Seattle ordinance increasing pay per delivery did not increase the monthly pay of gig delivery drivers in the city.

Solving the Problem

Step 1: Review the chapter material. This problem is about compensating differentials, so you may want to review the section “Compensating Differentials.”

Step 2: Answer part (a) by explaining what effect a regulation increasing the pay per delivery for gig delivery drivers will have on the number of gig delivery drivers working in Seattle. There is free entry into being a gig delivery driver. Anyone who has a car (although a bike, motorcycle, or scooter is also acceptable) and a good driving record can become a gig delivery driver. As a result, we would expect that a Seattle regulation increasing the pay per delivery will increase the number of gig delivery drivers by making gig delivery more attractive in comparison with other jobs.

Step 3: Answer part (b) by explaining the reasoning behind the authors’ statement that: “the equilibrium value of doing delivery work must always remain equal to the fixed, constant outside option available to all workers.” Although stated in technical terms, the authors are making the basic point that the compensation a worker receives in a job must be at least equal to the worker’s opportunity cost—the compensation the worker would receive in his or her next best available job. In this case, the next best available job might be working in a warehouse for Amazon, being a server in a restaurant, or some other job that has free entry and doesn’t require significant training. At any given time, workers in Seattle will have chosen jobs with compensation packages that fit their particular preferences, which include the wages received, as well as some of the other job characteristics—such as health insurance—that we’ve mentioned in this section. Holding the level of compensation in other occupations constant, raising pay for gig delivery drivers will make those jobs more attractive and therefore cause more workers to switch to gig delivery from other jobs. We would expect that the supply of gig delivery drivers will increase until the compensation from being one of those drivers falls back to the “fixed, constant outside options” available to drivers.

Step 4: Answer part (c) by explaining why your answers to parts (a) and (b) will lead to the authors’ conclusion that the ordinance increasing gig delivery drivers’ pay per delivery did not increase their monthly pay. We’ve seen in the first two parts of this problem that raising the pay of gig delivery drivers will increase the supply of these drivers and that the supply will continue to increase until their compensation is competed back down to the compensation they can receive from similar alternative jobs. As a consequence, drivers earn more per delivery because of the ordinance—but they make fewer deliveries because the higher pay attracts additional drivers. As An, Garin, and Kovak found, the result is drivers’ monthly pay was no higher after the Seattle City Council passed the ordinance than it was before.
CPI Inflation Increases in September

Image created by ChatGPT

After the Federal Open Market Committee (FOMC) increased its target for the federal funds rate at its September meeting, there was uncertainty as to whether it would raise its target again at its meeting on October 27–28. Today’s report from the Bureau of Labor Statistics (BLS) on the consumer price index (CPI) for September showed that inflation had risen more than expected, likely increase somewhat the probability of the committee raising its target range at its October meeting.

As we’ve noted before, and as we discuss in Macroeconomics, Chapter 15 (Economics, Chapter 25), monetary policy affects the economy with, in the words of Nobel laureate Milton Friedman, “long and variable lags.” As a result, most economists agree that the Federal Reserve should not attempt to “fine tune” the economy by responding to each government release of macroeconomic data. Nevertheless, in practice, it’s clear that during times when Fed policymakers are split over what course of action to take, a single data report can have a significant effect on their decision.

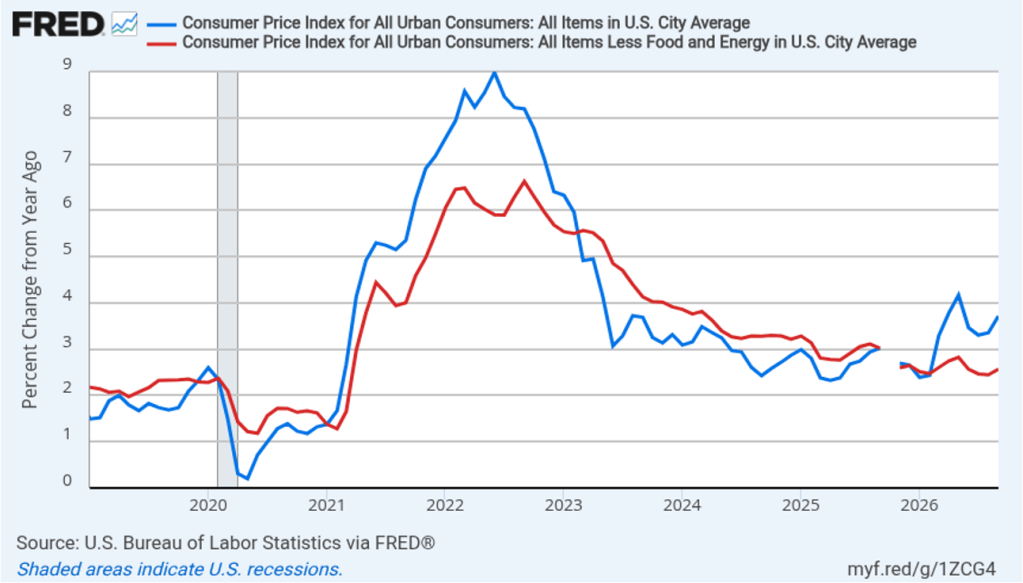
The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).

  • The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.7 percent in September, up from 3.4 percent in August.
  • The core inflation rate, which excludes the prices of food and energy, was 2.6 percent in September, up from 2.4 percent in August.

Headline inflation and core inflation were both higher than the forecasts of economics surveyed by the Wall Street Journal. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)

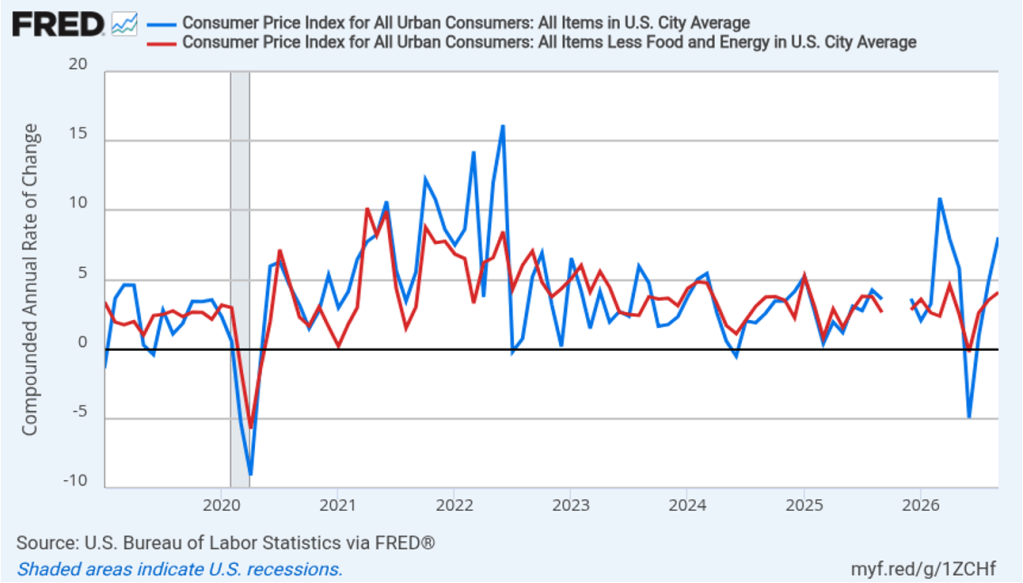
In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline inflation (the blue line) soared to 8.1 percent in September, up from 4.9 percent in August. Core inflation (the red line) was 4.1 percent in September, up from 3.5 percent in August.

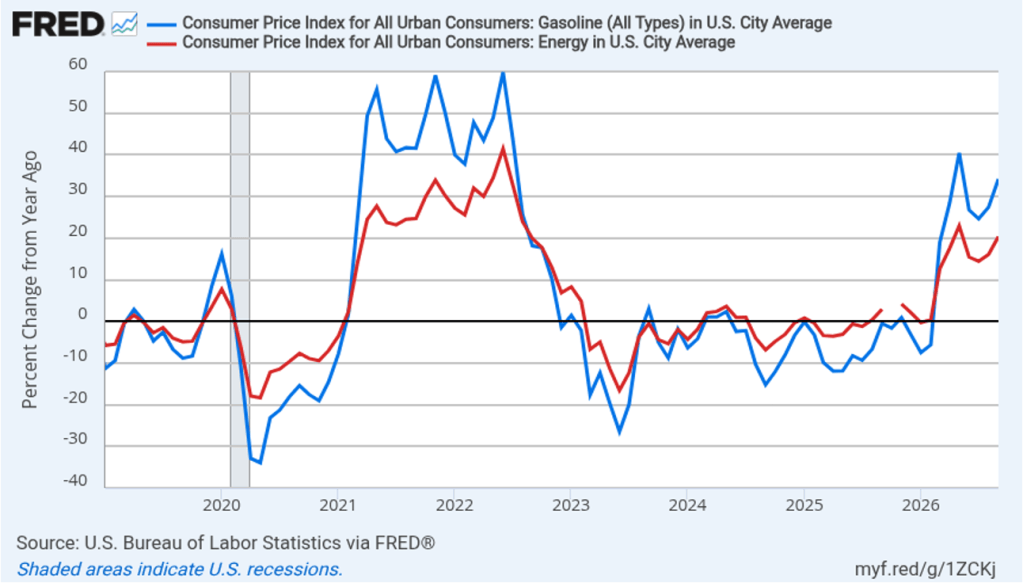
As the large gap between the headline and core 1-month inflation rates indicates, energy prices, particularly gasoline prices, rose sharply in September. In the following figure, the red line shows the 12-month inflation rate in all energy prices included in the CPI. Inflation in energy prices was 20.4 percent in September, up from 16.4 percent in August. The blue line shows the 12-month inflation rate in gasoline prices, which increased to 34.2 percent in September from 27.4 percent in August.

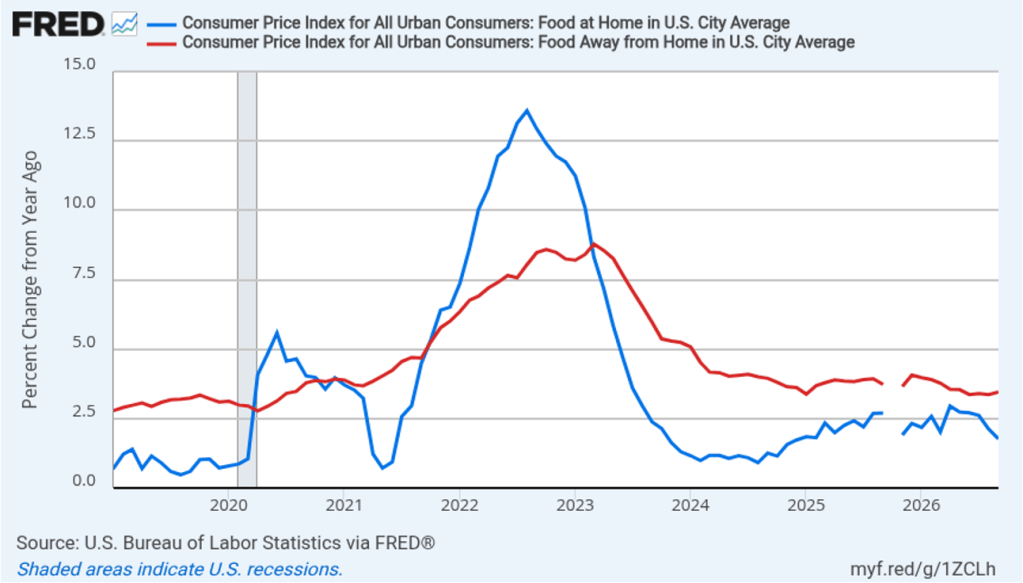
There has been a fear that the rise in energy prices that began in March will pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 12-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and in the category “food away from home” (the red bar)—primarily food purchased at restaurants. Grocery prices increased 3.5 percent in September from a year ago, down from 3.7 percent in August. Restaurant prices increased 3.5 percent from a year ago, up slightly from 3.4 percent in August. To this point, increases in energy prices seem to have had some effect on grocery prices and restaurant prices, although the extent of the effect is unclear.

Fed Chair Kevin Warsh has indicated that he favors measures of the inflation rate that exclude particularly small or particularly large changes in the prices of some goods or services—so-called outliers. Median CPI, which is compiled monthly by economists at the Federal Reserve Bank of Cleveland, is calculated by ranking the price changes of every good or service in the index from the largest price change to the smallest price change, and then choosing the price change in the middle. The idea is to eliminate the effect on measured inflation of any short-lived events that cause the prices of some goods and services to be particularly high or particularly low. Economists at the Cleveland Fed have conducted research that shows that, in their words, “the median CPI provides a better signal of the underlying inflation trend than either the all-items CPI or the CPI excluding food and energy. The median CPI is even better at forecasting [personal consumption expenditures] PCE inflation in the near and longer term than the core PCE price index.”

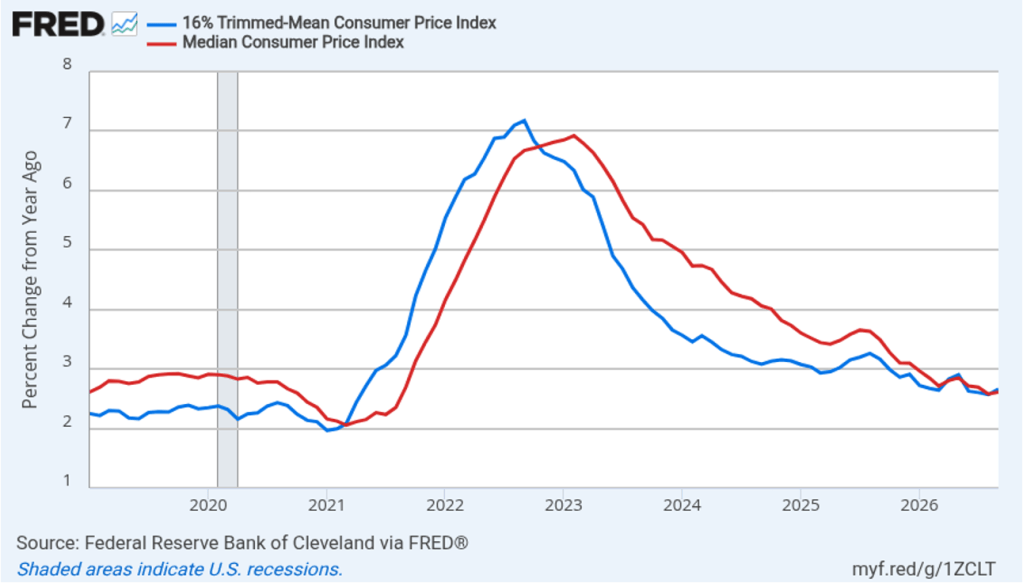
Trimmed-mean inflation, also compiled by economists at the Cleveland Fed, excludes the highest 8 percent of price changes and the lowest 8 percent. The following figure shows 12-month trimmed mean (the blue line) and median (the red line) CPI inflation. Trimmed-mean inflation was 2.7 percent in September, up from 2.6 percent in August. Median inflation was 2.6 percent in September, unchanged from August. So these measures of inflation are both lower than the conventional headline and core CPI inflation measures, which indicates that the acceleration in inflation during September was not affecting all sectors of the economy.

Note that the Fed uses the 12-month change in the personal consumption expenditures (PCE) price index, not the change in the CPI, when gauging whether it is hitting its 2 percent annual inflation target. Historically, PCE inflation has been about 0.4 percentage points to 0.5 percentage points lower than CPI inflation. The Bureau of Economic Analysis (BEA) won’t release its estimate of September PCE inflation until October 29, one day after the next FOMC meeting.

Today’s report showing that inflation remains persistently above the Fed’s 2 percent annual target has likely raised the chance that Federal Reserve policymakers will increase their target range for the federal funds rate from the current 3.75 percent to 4.00 percent by o.25 percentage points (or 25 basis points) at the next meeting of the FOMC on October 27–28. Trading in the federal funds futures market this afternoon indicates that investors assign a 33.8 percent probability to the FOMC raising its target range at that meeting, which is up from a 22.1 percent probability yesterday. Trading indicated that investors assign a 89.7 percent probability to the committee increasing its target range by at least 25 basis points at its last meeting of the year on December 8–9. Some analysts have speculated that the committee will postpone its next rate increase until December to avoid raising the rate before the midterm election on November 3.

Hall and Woodford Win 2026 Nobel Prize in Economics

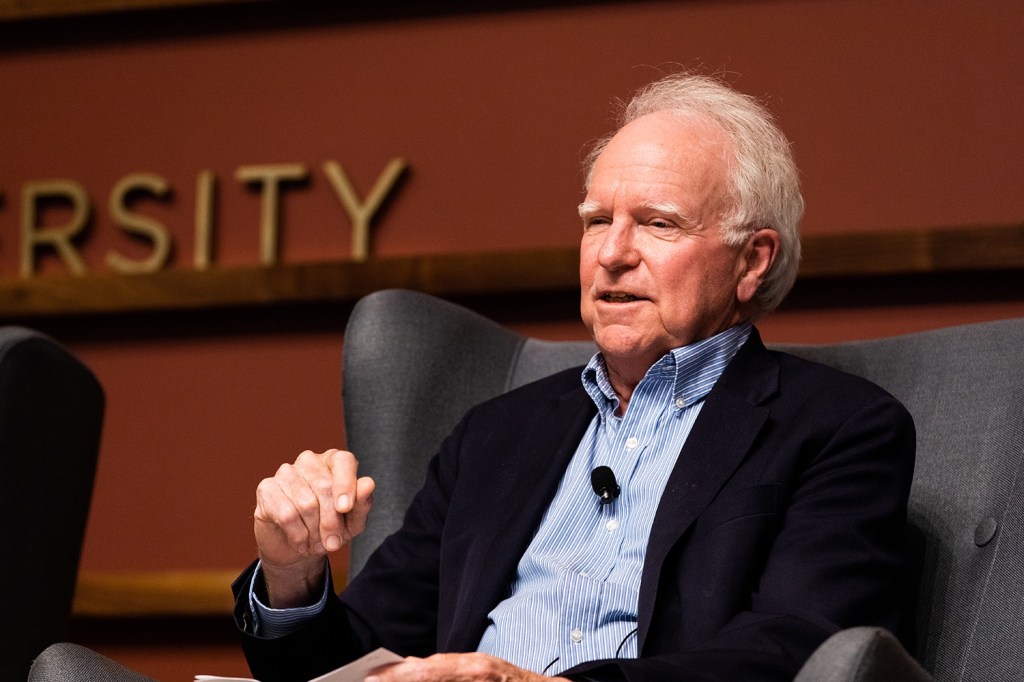
Photo of Robert Hall from news.stanford.edu

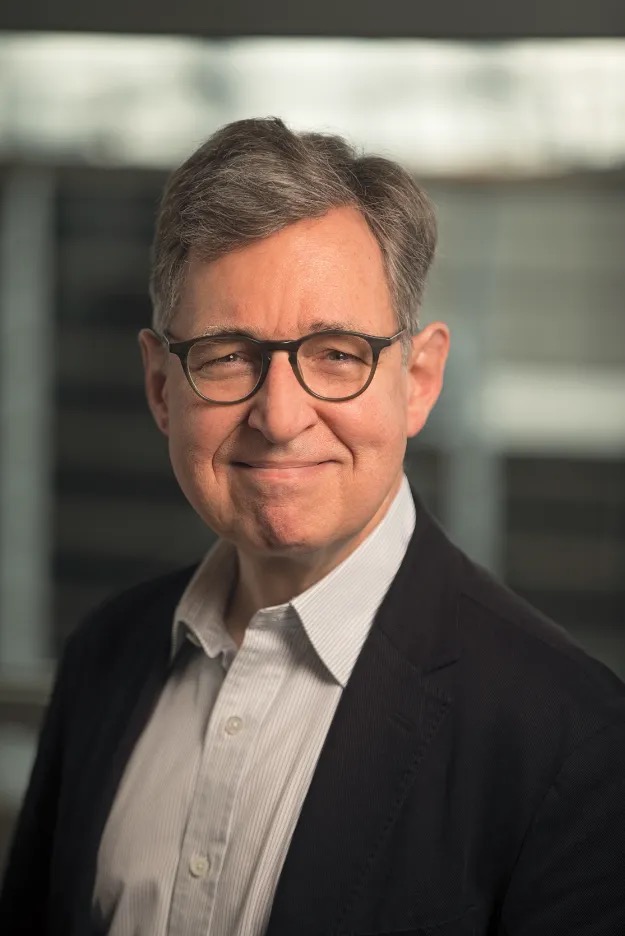
Photo of Michael Woodford from politicaleconomy.columbia.edu

Robert Hall of Stanford and Michael Woodford of Columbia have been awarded the 2026 Nobel Prize in Economics. Their careers have helped define the evolution of macroeconomics during the past 50 years.

Principles of economics is often taught as one semester of microeconomics and one semester of macroeconomics. In microeconomics we focus on analyzing the households’ decisions about which products to buy and on firms’ decisions about which products to sell and what prices to charge. In macroeconomics we switch the focus to the economy as a whole, analyzing what determines total production in the economy, as measured by GDP, and what determines the price level, as measured by the consumer price index (CPI) or the personal consumption expenditures (PCE) price index. An important part of macroeconomics is analyzing the effects of the federal government’s monetary and fiscal policies on production, employment, and prices.

Microeconomics and macroeconomics are connected because macroeconomic aggregates (like GDP, the unemployment rate, and the price level) ultimately depend on the decisions of households and firms. Similarly, the effects of fiscal and monetary policies on the economy depend on how households and firms react to the policies.

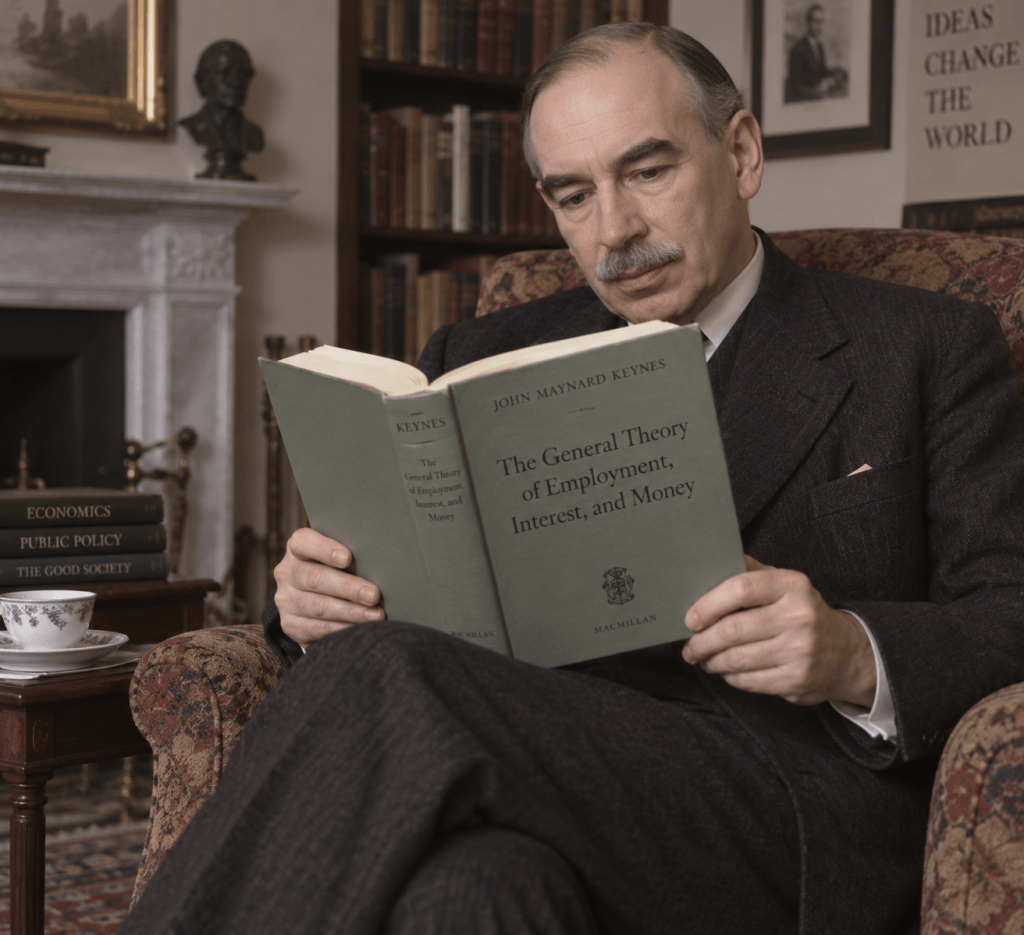
Image of John Maynard Keynes created by ChatGPT

The focus on economic aggregates in macroeconomics dates back to the publication of John Maynard Keynes’s General Theory of Employment, Interest, and Money in 1936. Keynes’s book was long and complicated, which led shorter, more straightforward, interpretations of his ideas by Nobel laureate John Hicks of Oxford and Alvin Hansen of Harvard to become widely accepted. The Hicks-Hansen interpretation was embodied in the IS-LM model, which focused on the relationships among a few macroeconomic variables. (We discuss the IS-LM model in the appendix to Chapter 18 of Money, Banking, and the Financial System.)

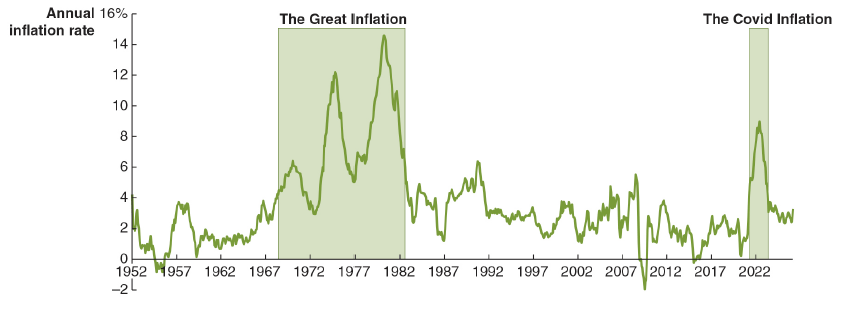
During the Great Inflation of the 1970s of the 1970s and early 1980s, many economists concluded that the basic IS-LM model was no longer a good guide to understanding events in the U.S. economy. That conclusion increased the interest in grounding macroeconomics in the basic decision making of households and firms. This approach became known as the microfoundations of macroeconomics.

This new focus on microeconomics led some economists to reject the idea that discretionary monetary and fiscal policy was able to stabilize the economy by reducing fluctuations in aggregate output and employment. This approach is called the New Classical Macroeconomics. (We discuss the New Classical Macroeconomics in the appendix to Macroeconomics, Chapter 13.) Other economists argue that discretionary policy can play a role in stabilizing the economy, which is a key argument advanced by Keynesians since the 1930s, but believe that policymakers need to take into account how households and firms react to policy. This approach is called the New Keynesian economics. The work of Hall and Woodford contributed to the development of New Keynesian economics.

Early in his career, Hall published an academic article making a major contribution to understanding the microfoundations of consumption spending. Hall’s work elaborated Milton Friedman’s permanent income hypothesis. As we discuss in Macroeconomics, Chapter 12, Section 12.2 and Chapter 16, Section 16.5, consumers are forward looking, which means their consumption decisions take into account not just their current income but also their expected future income—which Friedman called permanent income. For example, a real estate agent might have a high income in a year when she earns a commission on the sale of 15 houses and a much lower income in a year when the local housing market is weak and she earns a commission on only 2 houses. Most people like to smooth out their consumption over time, so the agent is likely to spend less of her current income in good sales years and more of her current income in the bad sales years.

Image created by ChatGPT

Hall formalized Friedman’s insight using the tools of dynamic optimization and also showed that the model fit the macroeconomic data well. One important implication of Hall’s work is that households are unlikely to significantly adjust their spending in response to temporary policy changes, such as a temporary cut in personal income taxes. Hall made a number of additional contributions to macroeconomics, including by analyzing why prices and wages don’t always respond quickly to changes in total spending. As we discuss in Macroeconomics, Chapter 10, Section 10.3, the federal government produces many statistics that make it possible to monitor the state of the economy, but the federal government does not officially decide when a recession begins or when it ends. Instead, most economists and policymakers accept the decisions of the Business Cycle Dating Committee of the National Bureau of Economic Research (NBER), a private research group located in Cambridge, Massachusetts. Hall served as chair of the committee for 46 years, from 1978 to 2024.

Image of the NBER building from the Wikipedia Commons

Woodford has made wide-ranging contributions to the development of New Keynesian economics. In particular, he developed a model that synthesized the contributions of a number of other economists to provide a general framework for understanding macroeconomics and for evaluating the effects of monetary policy. His 2003 book, Interest and Prices: Foundations of a Theory of Monetary Policy, has been particularly influential.

Image from amazon.com

The Nobel Committee’s announcement of the prize can be found here. A longer discussion of the Hall and Woodford’s work can be found here. The scope of their research can be seen by reviewing their curricula vitae, which can be found here and here. The amount of the prize this year is 12 million Swedish kronor (about $1.2 million).
Glenn on a Novel Approach to Reforming Social Security

Image created by ChatGPT

In Macroeconomics, Chapter 16 (Economics, Chapter 26), we discuss the problems facing the Social Security system. In this opinion column, which first appeared on the website of the Economist, Glenn discusses a new approach to discovering the views of the public on possible reforms to the system.

America Needs a Citizens’ Assembly to Reform Social Security

Of the various fiscal challenges faced by America, the one the public feels most keenly is the looming crisis in Social Security. It also presents an opportunity for a bold reform process outside the polarised and dysfunctional electoral process, built around consulting a sample of voters directly in a citizens’ assembly. This would have the twin benefits of bypassing both voters’ mistrust of politicians and politicians’ incomplete understanding of voters’ attitudes towards reform.

Voters are clearly ready for reform. Recent polling of swing-state voters by the Peterson Foundation, an organisation launched to promote fiscal responsibility, revealed broad opposition to inaction and support for reforms including raising the earnings cap subject to the payroll tax and capping Social Security benefits for better-off households. Only 17% of voters said they were likely to support a candidate in the upcoming midterms who promised not to touch the current system.

Social Security pays retirement benefits to 62m Americans and disability benefits to another 8m. But the 2026 Social Security Trustees Report (sstr) predicts that the system’s trust funds will be exhausted in 2032, and if no action is taken by Congress, benefits will need to be cut across the board by 22% at that time.

Elected officials have responded in a now-familiar way, with a proposal for a 13-member commission of members of Congress and experts. Historically, a commission held promise: one assembled in 1981 and commonly known as the Greenspan Commission after its chairman, Alan Greenspan, offered a sensible roadmap for gradual reforms in 1983. Today, such an approach, however well intentioned, is likely to fail, given how out-of-balance the system is. According to the sstr, it faces an actuarial deficit of 4.4% of payroll annually for the next 75 years. Tackling that via a commission would have been extremely difficult in the 1980s. Doing so today, with public trust in government and experts a lot lower, looks impossible. According to the Pew Research Centre, just 17% of Americans trust the federal government to do “what is right” always or most of the time, down from around 40% in the early 1980s.

America needs to experiment more boldly this time by entrusting the big decisions to voters, via a citizens’ assembly tasked with presenting clear options to elected officials. Social Security reform offers a logical use case for such an approach because the areas where change is needed are clearly delineated: retirement age, benefit formulas and the level and structure of taxation. And it can give insight to politicians about voters’ real views about the thorny economic and political trade-offs that will need to be made.

Citizens’ assemblies date back to ancient Athens as a way to inform democracy. In the modern era they have been used in several countries, including Belgium, France and Ireland, to develop policy. In Ireland, for example, recent citizens’ assemblies illustrated to politicians that attitudes towards abortion and same-sex marriage had changed more than legislators had realised.

A citizens’ assembly can help to break through policy gridlock by allowing ideas to be developed and debated in a higher-trust environment than a commission drawn from politicians and experts in whom the public has declining faith. Moreover, the ideas emerging from an assembly can sometimes reveal the “Overton window”—the range of reforms that the public can live with at that particular time—better than elected leaders can alone, as seen in the Irish case.

Three steps are critical to the success of any citizens’ assembly. The first concerns its composition. Its members, typically 50-100, should be chosen by lot, as with candidates for a jury. It should be an electorate in miniature, representative of the nation’s social strata and demography. Towards this end, sampling should be random to avoid simply selecting volunteers with particular upfront points of view. Those selected should be compensated for their time and expenses. Structured in this way, the citizens’ assembly can channel mistrust of politicians towards a reclaimed populism of actual voters’ input, not slogans.

Second, per the advice of William McChesney Martin, a former chair of the Federal Reserve, experts should be on tap, not on top. In contrast to the typical commission, experts’ role would be to provide information, not to suggest prescriptions. That would allow an assembly to develop reform options that reveal genuine voter sentiment, while neutralising populist mistrust of experts.

Third, politicians and their existing institutions need to support the work of the assembly. Congress should signal strongly that it will give serious consideration to proposals coming out of an assembly—and commit to an up-or-down vote on them, as with the process for military-base closures in 1988. Elected officials should not need reminding about the large benefit reductions that will kick in as a result of a failure to act by 2032.

Selection, expert input and politicians’ commitment map well into Social Security reform. Over multiple sessions (the Irish deliberation on abortion unfolded over several weekends in a six-month period) the assembly would agree upon objectives and principles, a menu of reform options and a recommendation for formal consideration by Congress. Outside experts would provide background information on design choices (say, refining the current system or moving, for example, to a system with a flat benefit for all) and the budget and individual tax-and-benefit consequences of options (say, changes in the retirement age, payroll tax, and benefit level and structure). With this input, the assembly would evaluate options with both principles and political feasibility in mind.

Such an assembly offers an opportunity for meaningful action before the 2032 deadline. Were it successful, that would also provide momentum in related areas, such as the need for budget consolidation and policies towards artificial intelligence.

Social Security reform is stuck in deep political mud. A citizens’ assembly might just be the way to free it. It’s surely worth a tr

How Good Were the Deals during Amazon’s Prime Big Deal Days?

Image created by ChatGPT

Amazon concluded its fall Prime Big Deal Days yesterday. Amazon also has a Prime Day in the summer. The company generally reports that its Prime Days result in higher sales and that the lower prices Amazon charges during these periods result in substantial savings to consumers. For example, in October 2024, Amazon announced that, “Globally, Prime members saved more than $1 billion across millions of deals, including on seasonal merchandise and gifts.”

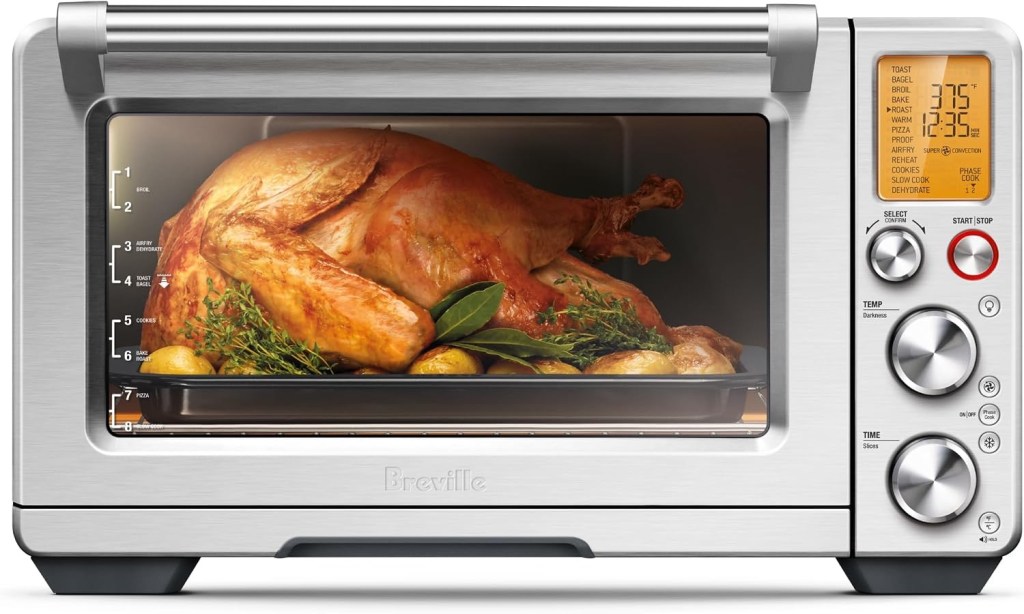
Most consumers likely expect that on Prime Days they can buy goods more cheaply on Amazon than on competing sites. That assumption isn’t always accurate, however. For example, Wirecutter is a product-review website owned by the New York Times. Yesterday, it recommended as one of several “best deals from Amazon’s Prime Big Deal Days” Breville’s Smart Oven Air Fryer Pro. Amazon was selling the oven at a price of $320, 20 percent less than its regular price of $400.

Image from amazon.com

Was that price unusually low? Not in comparison with Amazon’s competitors. Target, Best Buy, and Macy’s were also charging $320 for the same oven. Walmart was charging only $280. This price matching is unsurprising. Amazon’s Prime Days are widely publicized and Amazon’s competitors have an incentive to respond with sales of their own rather than lose business to Amazon. For instance, during Prime Days, Walmart was also advertising that on their site “Deals Are Heating Up in a Major Way.”

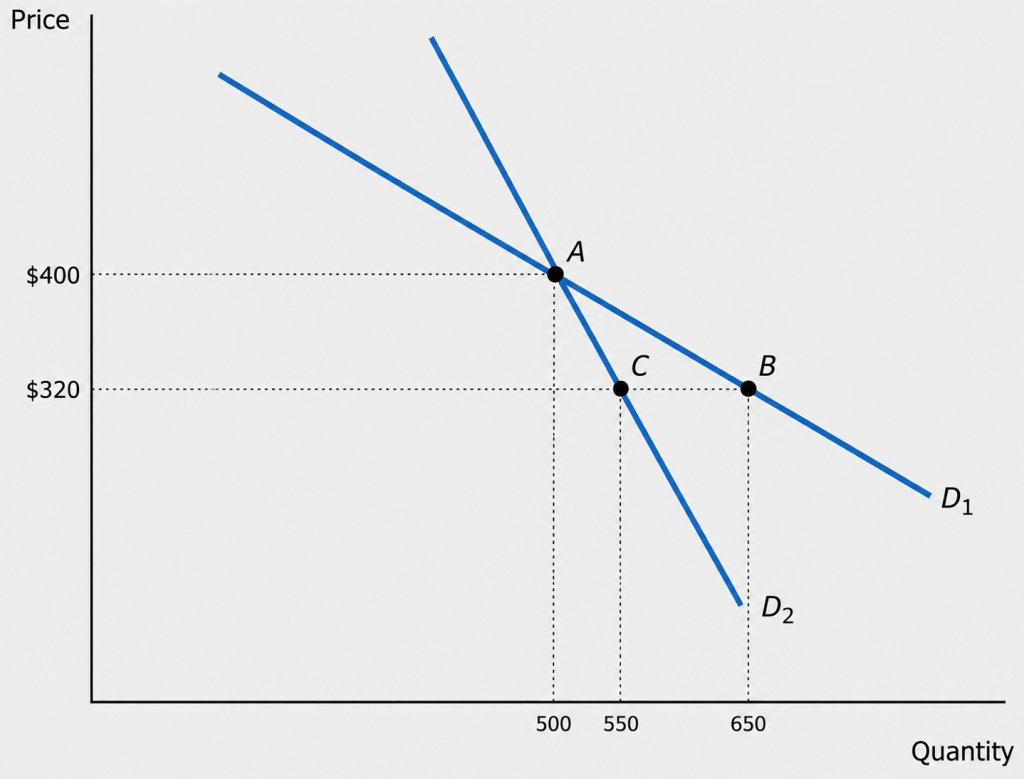
The price matching by competitors is, of course, not good news for Amazon. The following figure shows the demand for Breville ovens on amazon.com. For Amazon to experience an increase in the revenue it earns on the ovens from cutting the price by 20 percent, the quantity of ovens it sells would need to increase by more than 20 percent. Suppose that, hypothetically, Amazon would have sold 500 ovens per day at a price of $400 (point A).

If Amazon cuts the price of the ovens to $320 and its competitors keep their prices at $400, the demand curve for the ovens on amazon.com is D1, so the quantity of ovens Amazon sells increases to 650 per day (point B). In this case, Amazon’s revenue increases from $400 × 500 = $200,000 to $320 × 650 = $208,000. But if Amazon’s competitors match Amazon’s price cut—as we know that they did—then the demand curve for the ovens is D2, so the quantity of ovens Amazon sells increases only to 550 (point C). In this case, Amazon’s revenue decreases from $400 × 500 = $200,000 to $320 × 550 = $176,000.

(In Microeconomics, Chapter 6, we note that when two demand curves intersect, the flatter demand curve, D1—the one with the smaller slope in absolute value—is more price elastic than is the steeper demand curve, D2. In other words, a firm faces a more elastic demand curve when competitors match the firm’s price cuts than when they don’t.)

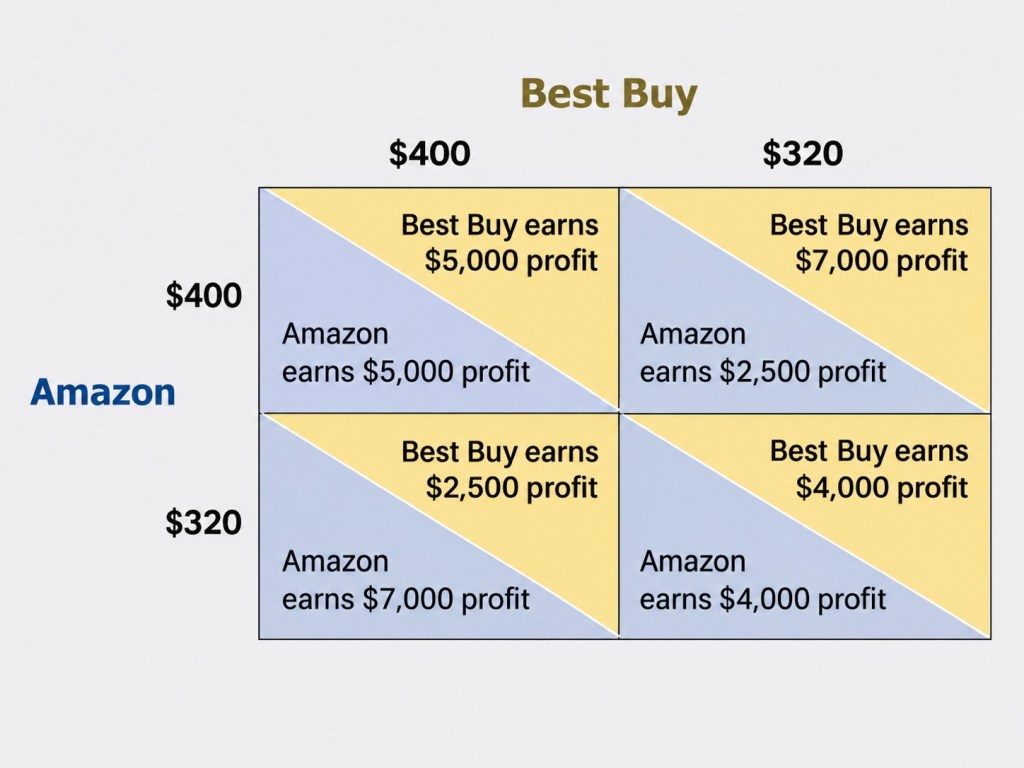
One way to think about the pricing of these ovens is that with Prime Day price cuts, Amazon pushed itself and its competitors into a prisoner’s dilemma. If we simplify the situation by including just Amazon and Best Buy, we can construct the following payoff matrix. (We discuss payoff matrices and the prisoner’s dilemma in Microeconomics, Chapter 14, Section 14.2.)

In this payoff matrix, Amazon and Best Buy are better off if they both charge $400 and earn a profit of $5,000 per day from selling the ovens (the upper left-hand quadrant). But if Amazon knows that Best Buy will charge $400, Amazon is better off gaining sales by charging $320 and earning a profit of $7,000 rather than a profit of $5,000 (the lower left-hand quadrant). If Amazon knows that Best Buy will charge $320, Amazon is better off also charging $320 and earning a profit of $4,000 rather than a profit of $2,500 (the lower right-hand quadrant).

Because the payoffs are symmetrical, we can conclude that both firms will charge $320, ending up with the smaller profit shown in the lower right-hand quadrant rather than the larger profit shown in the upper left-hand quadrant. The two firms are in a prisoner’s dilemma.

As we discuss in Chapter 14, in practice, firms can escape the prisoner’s dilemma in situations like this one because the firms are in a repeated game. In that situation, firms are better off cooperating by implicitly colluding and both charging $400. But we wouldn’t expect implicit collision here because during Prime Days, Amazon is publicly announcing that it will charge the lower price. In that case, Amazon’s competitors have an incentive to also charge a lower price, which they did. (Walmart, as we mentioned, decided to charge a price that was even below Amazon’s Prime Day price.)

So, can you get good deals during Amazon’s Prime Days? Yes, not only on their site, but on competitors’ sites as well.

Solved Problem: A Half-Price Sale on U.S. Treasury Bonds?

Supports: Money, Banking, and the Financial System, Chapter 3.

Image generated by ChatGPT of the U.S. Treasury building in Washington, DC

In a recent book review in the Wall Street Journal, financial analyst James Grant wrote: “The Treasury may indeed pay off every claim in freshly printed dollars. But 30-year Treasurys issued at the sub-2% yields prevailing in 2020 change hands today for less than 45 cents on the dollar.”

To illustrate Grant’s point: On May 15, 2020, the U. S. Treasury issued a 30-year bond with a $12.50 coupon and a face value, or par value, of $1,000. On October 6, the market price of the bond was $424.25. If you buy this bond today, you will receive a payment of $1,000 from the U.S. Treasury on May 15, 2050. The U.S. Treasury most recently issued 30-year bonds on August 17, 2026. Those 30-year bonds have a coupon of $51.25.

a. What does Grant mean by writing that 30-year Treasury bonds issued in 2020 “change hands today for less than 45 cents on the dollar”?

b. Why would anyone would be willing to sell you a bond for less than 50 percent of the amount the seller would receive by holding the bond to maturity?

Solving the Problem
Step 1: Review the chapter material. This problem is about why bond prices fluctuate, so you may want to review Money, Banking, and the Financial System, Chapter 3, “Interest Rates and Rates of Return,” particularly the section “What Happens to Bond Prices When Interest Rates Change?”

Step 2: Answer part a. by explaining what Grant meant by bonds changing hands at less than 45 cents on the dollar. By “changing hands” Grant is referring to buying and selling bonds in the bond market. By “less than 45 cents on the dollar,” Grant means that bonds with a face value of $1,000 are selling for less than $450.

Step 3: Answer part b. by explaining why someone would be willing to sell you a bond for only $450 even though the bond has a face value of $1,000. In the bond market, as bonds are bought and sold, bonds of the same characteristics should have the same yield, as measured by the yield to maturity on the bonds. The 30-year bonds the Treasury issued in August of this year currently have a yield to maturity of about of about 5.31%. (The yield to maturity on these bonds is greater than the bonds coupon rate of 5.125% because the prices of the bonds are currently less than $1,000.) As an investor, you would only be willing to buy the 30-year bonds the Treasury issued in 2020 with a coupon rate of 1.25% if the price of the bonds will result in your receiving a yield to maturity of 5.31%.

The expression that links the price of a coupon bond, P, to the yield to maturity on the bond, i, is:

Keeping mind that the coupon, C, on a bond is fixed once the bond is issued, an increase in the yield to maturity must cause a decline in price of the bond. Because the gap in coupon rates between Treasury bonds issued in 2020 and in 2026 is so large, the 2020 bonds must have much lower prices in order to have the same yield to maturity.

Extra credit. The U.S. Treasury only started regularly issuing coupon bonds in the 1970s as the federal government began to run substantial budget deficits nearly every year. Prior to that, individuals rarely bought Treasury bonds with the exception of the tens of billions of “war bonds” the Treasury issued to raise funds during World War I and World War II.

Image from the American Museum of Natural History

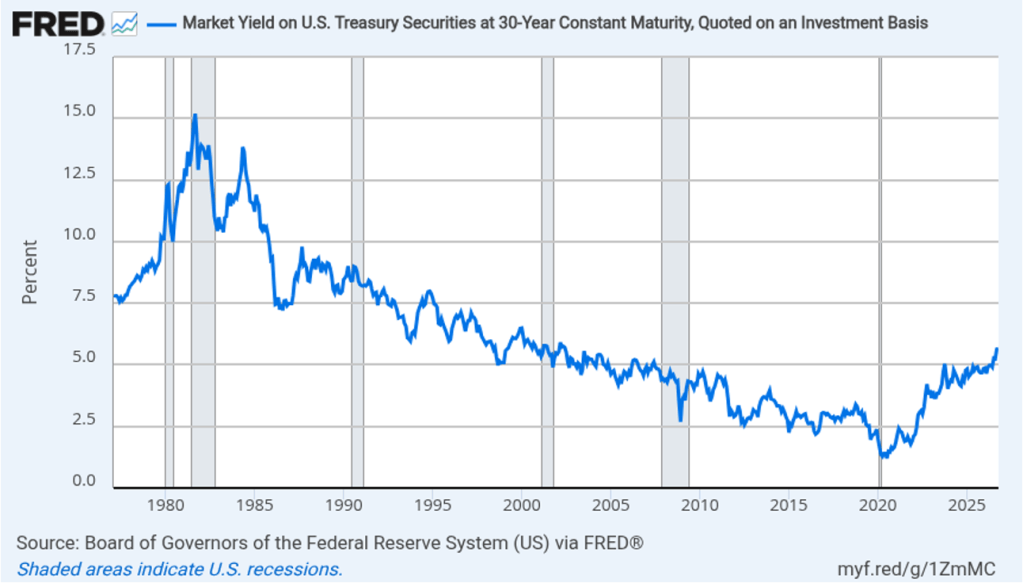
As the following figure shows, since the 1970s, the yields on 30-year Treasury bonds have changed dramatically over time, from more than 15% in 1981 to less than 2% in 2020. These variations in yields reflect the higher or lower coupon rates the Treasury needs to offer investors as a result of fluctuations in inflation and in other factors that affect the demand for bonds.

Is It Fine to Bring an Iced Coffee to a Job Interview? Jadrian Wooten Provides an Economic Analysis

Image created by ChatGPT

There’s a vigorous debate on social media over whether it’s acceptable for a job candidate to bring an iced coffee to an interview. In his always interesting “Monday Morning Economist” Substack, Jadrian Wooten provides an economic analysis based on the signaling theory of Nobel laureate Michael Spence of New York University and Stanford. 

Photo of Michael Spence from gsb.stanford.edu

Signaling can be important in markets affected by the problem of asymmetric information, which occurs when one party to an economic attraction has less information than the other party. As we discuss in Microeconomics, Chapter 7, George Akerlof—who was awarded the Nobel Prize in Economics in the same year as Spence—provided a classic early analysis of asymmetric information in the used car market. The seller of a used car will know whether a failure to maintain the car by, for instance, regularly changing its oil, has caused the car’s engine to suffer damage that even an auto mechanic may have difficulty detecting.

Image created by ChatGPT

Asymmetric information in a market can lead to adverse selection in which one party to a transaction—in this case, a car seller—takes advantage of knowing more than the other party—in this case, a car buyer. For example, suppose you intend to buy a car, and you contact people who have listed cars on Facebook Marketplace or Craigslist. You have no good way of determining whether a car listed has been well maintained, a “creampuff,” or poorly maintained, a “lemon.” If you had full information on the car you would offer to pay $25,000 to buy a creampuff, but only $15,000 to buy a lemon. Because of this uncertainty, you might offer to pay $20,000 for a car of unknown quality. Your offer seems reasonable to you, given your uncertainty about the quality of the car. However, a seller who knows the quality of the car will be reluctant to accept your offer if the car is a creampuff, but happy to accept your offer if the car is a lemon. The result is that cars offered for sale are more likely to be lemons than creampuffs. Or, in other words, because of asymmetric information, the market has adversely selected the cars that will be offered for sale.

Asymmetric information also exists in the job market. When you apply for a job, you know much more about how hard you will work and how developed your relevant skills are than does the company you are applying to. Suppose that the company would pay you a salary of $60,000 per year if the company was sure that you would turn out to be a hard worker, but only $40,000 if the company believed that you would turn out be a slacker. Because of this uncertainty, the company might offer a starting salary of $50,000. That salary would be attractive to slackers but unattractive to hard workers. As a result, the company might find that most of the people applying to work for them are slackers.

Michael Spence argues that in markets in which asymmetric information is important, economic agents will have an incentive to signal that the good or service they are selling is of higher quality than buyers might otherwise think. For example, a firm selling used cars may invest in making their dealership clean and attractive or by offering warranties on the cars they sell. The firms are attempting to signal buyers that the cars they are selling are creampuffs rather than lemons.

One strong signal you can send to employers when you apply for jobs is that you have earned a college degree. There has been a long debate among economists over whether a college degree indicates to potential employers that you have accumulated knowledge and skills in college—in other words, your human capital is higher than for non-college graduates—or whether a college degree is mainly a signal to potential employers that you are likely to be a hard worker because you have completed a task as difficult as obtaining a college degree.

Image created by ChatGPT

The sheepskin effect is often raised by economists arguing that for potential employers your having college degree is more about signaling than about the human capital you have accumulated in college. If you complete three years of college but drop out in your fourth year before earning your degree, you have likely learned almost as much, and have nearly the same level of human capital, as someone who has taken the few additional classes needed to earn a degree. In the job market, though, you are likely to earn significantly less than someone who has a college degree. This result makes it seem that a college degree is primarily a signal to employers that you have the characteristics of a good employee. Note: The sheepskin effect gets its name from the fact that years ago college diplomas were often printed on material derived from animal skins.

This older blog post by Noah Smith, including the responses from Bryan Kaplan of George Mason University, covers the main points raised in the debate over whether the value of a college degree is mainly the signal it sends to potential employers.

So, what signal are you sending when you bring an iced coffee to a job interview? Jadrian Wooten’s Substack post explains.

Solved Problem: Why Do Bond Prices and Bond Yields Move Inversely?

Supports: Money, Banking, and the Financial System, Chapter 3, and Microeconomics, Chapter 8, Appendix.

Image created by ChatGPT

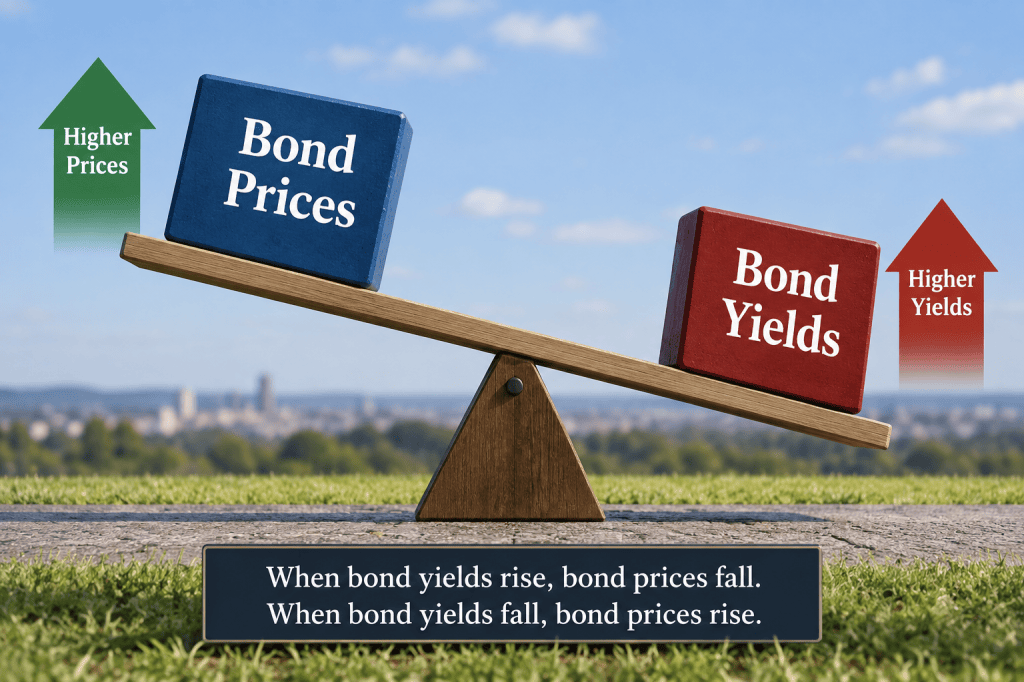
A recent article in the Wall Street Journal was titled “A Primer on Why Bond Prices Fall When Yields Rise.” A student reading the title of the article asks, “How can that be right? Investors would prefer to own bonds that have higher yields, so when the yields on bonds rise, investors should demand more of them. When the demand for something goes up, the price increases. Therefore, bond yields and bond prices should go up (or down) together.” Briefly explain the error in this student’s reasoning.

Solving the Problem
Step 1: Review the chapter material. This problem is about the relationship between bond yields and bond prices, so you may want to review Money, Banking, and the Financial System, Chapter 3 (for a complete discussion) or Microeconomics, Chapter 8, Appendix (for a brief discussion).

Step 2: Solve the problem by explaining what is wrong with the argument that if bond yields increase, so will bond prices, and if bond yields decrease, so will bond prices. In solving the problem, we should first consider the sometimes confusing number of “interest rates” on a coupon bonds. Coupon bonds pay interest in the form of coupons, which are usually quoted on an annual basis although typically paid twice per year. For example, Apple may issue a bond that pays a coupon of $47.50. The coupon rate on this bond is quoted per $1,000 of face value, or par value, which in this case would be 4.750%.

Bonds, like other financial assets such as shares of stock, are bought and sold in financial markets. A key point is that in financial markets, bonds with similar characteristics—including the same level of default risk, the same liquidity, and the same tax treatment of the bonds’ coupons—should provide investors with the same expected return. If this condition didn’t hold—for instance, if a bond issued by Apple was expected to provide a higher return than comparable bonds—then investors would increase their demand for the Apple bond, forcing up its price until its yield fell by enough to make its expected return the same as on other comparable bonds.

The price of a bond can fluctuate depending on how its coupon rate compares to the coupon rates on newly issued bonds, changes in investors’ expectations of future inflation, changes in investors’ expectations of the default risk of the bond, and other factors. For example, an article in the Wall Street Journal reported that, “Lenders on Monday demanded higher yields on bonds from a new data-center project in El Paso, Texas, leased by Meta compared with a similar project last year.” According to the article, the reason for the higher yields was that investors had raised their estimates of the default risk on bonds issued to fund data centers. Investors needed higher yields on bonds to compensate them for the higher default risk.

An image created by ChatGPT of Meta’s data-center complex under construction in El Paso, Texas.

What happens to the prices of existing bonds when newly issued bonds have higher coupon rates? Keeping in mind that, because the coupon rate on a bond is fixed and won’t change after the bond has been issued, the only way that the yield on a bond can change is if the price of the bond declines. By “yield” we are here referring to the yield to maturity, which is the best way of calculating the yield on a bond and which is ordinarily what economists and investors mean when they refer to the interest rate on a bond.

Formally, the yield to maturity is defined as the interest rate that makes the present value of the payments from the bond equal to the bond’s current price. In the following expression, where C is the coupon on the bond, FV is the face value of the bond, and n is the number of years until the bond matures, i is the yield to maturity.

The arithmetic of this expressions shows that if the yield to maturity increases, because, for example, the coupon rate on similar newly issued bonds are higher than the coupon rate on this bond, the price of the bond must decline. The economics of this expression is that an increase in the yield to maturity reduces the present value of a bond’s coupon payments and face value.

The reverse happens if the yield to maturity on a bond falls: The price of the bond will rise as a matter of arithmetic. As a matter of economics, a lower yield to maturity increases the present value of a bond’s coupon payments and face value.

So, although the student’s assertion seems logical, the economics of bond prices shows that the prices and yields on bonds move inversely.

Unexpectedly Weak September Jobs Report

Image created by ChatGPT

This morning (October 2), the Bureau of Labor Statistics (BLS) released its “Employment Situation” report (often called the “jobs report”) for September. The August jobs report had showed an unexpectedly large increase in employment, while the September report shows an unexpectedly small increase in employment.

The jobs report has two estimates of the change in employment during the month: one estimate from the establishment survey, often referred to as the payroll survey, and one from the household survey. As we discuss in Macroeconomics, Chapter 9, Section 9.1 (Economics, Chapter 19, Section 19.1), many economists and Federal Reserve policymakers believe that employment data from the establishment survey provide a more accurate indicator of the state of the labor market than do the household survey’s employment and unemployment data. (The groups included in the employment estimates from the two surveys are somewhat different, as we discuss in this post.)

The BLS is housed in the Suitland Federal Center in Maryland. (Image created by ChatGPT)

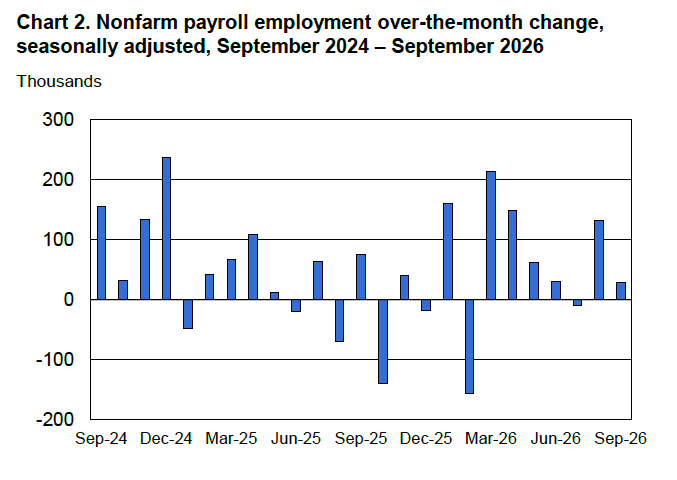
According to the establishment survey, there was a net increase of only 29,000 nonfarm jobs during September. Economists surveyed by the Wall Street Journal had forecast an increase of 90,000 jobs. Economists surveyed by FactSet had forecast a net increase of 95,000 jobs. The BLS revised downward its previous estimates of employment in July and August by a combined 60,000 jobs. The estimate of the net employment change in July was revised from an increase of 21,000 to a decrease of 10,000. (The BLS notes that: “Monthly revisions result from additional reports received from businesses and government agencies since the last published estimates and from the recalculation of seasonal factors.”)

The following figure from the jobs report shows the net change in nonfarm payroll employment for each month in the last two years. The figure shows that since peaking in March with a net increase of 214,000 jobs, job growth slowed markedly over the following four months, then strongly rebounding in August, before returning to slower growth in September. In 2026, monthly net employment growth has averaged 68,000. That is much higher than the 2025 average monthly employment growth of only 10,000, but well below the 2024 average monthly employment growth of 122,000.

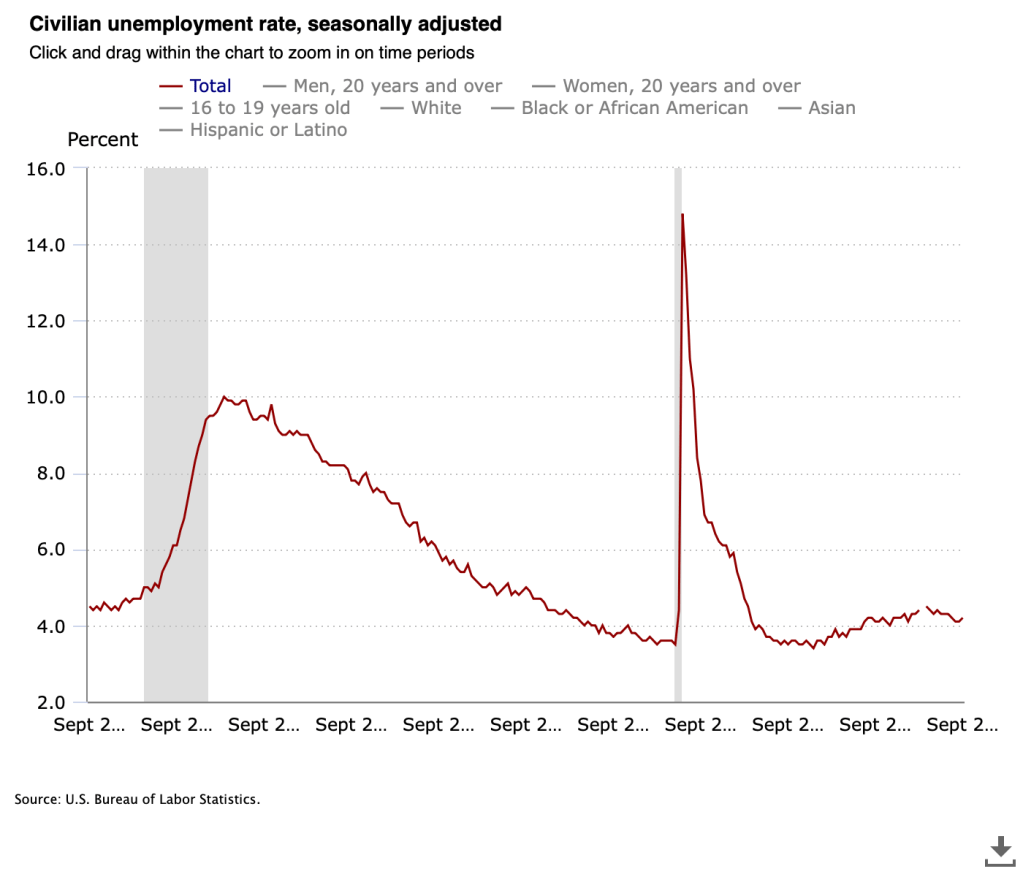
The unemployment rate, which is calculated from data in the household survey, was 4.2 percent in September, up slightly from 4.1 percent in August. The estimated size of the labor force, the number of workers employed, and the number of workers unemployed all increased in September. The following figure shows that the unemployment rate has been remarkably stable over the past year and a half, staying between 4.0 percent and 4.4 percent in each month since June 2024. The Federal Open Market Committee’s most recent estimate of the natural rate of unemployment—the normal rate of unemployment over the long run—is 4.2 percent. So, currently the unemployment rate is equal to that estimate of the natural rate. (We discuss the natural rate of unemployment in Macroeconomics, Chapter 9 and Economics, Chapter 19.)

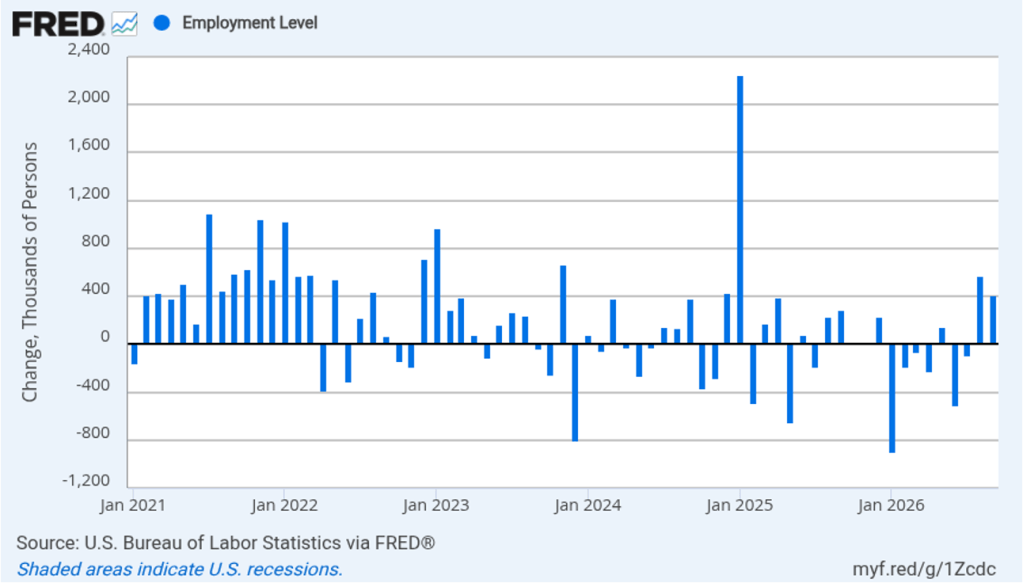
As the following figure shows, the monthly net change in jobs from the household survey moves much more erratically than does the net change in jobs from the establishment survey. As measured by the household survey, there was a net increase of 406,000 jobs in August, far larger than the net increase in employment shown in the establishment survey. Since January, the household survey has shown a net increase in jobs in only three months, with a total net decrease of 840,000 jobs over the period. In contrast, the establishment survey has shown a net increase of 612,000 jobs over the same period. (Note that because of last year’s shutdown of the federal government, there are no data for October or November.)

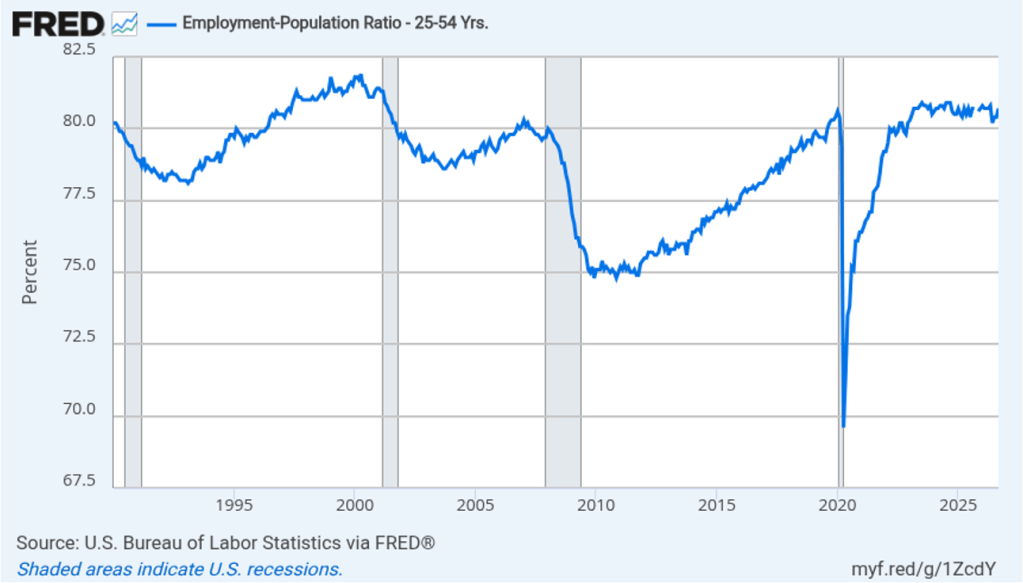
The household survey has another important labor market indicator: the employment-population ratio for prime age workers—those workers aged 25 to 54. In September, the ratio was 80.7 percent, up from 80.4 in August. The prime-age population ratio can show volatility from month to month but has remained above 80 percent every month since December 2022.

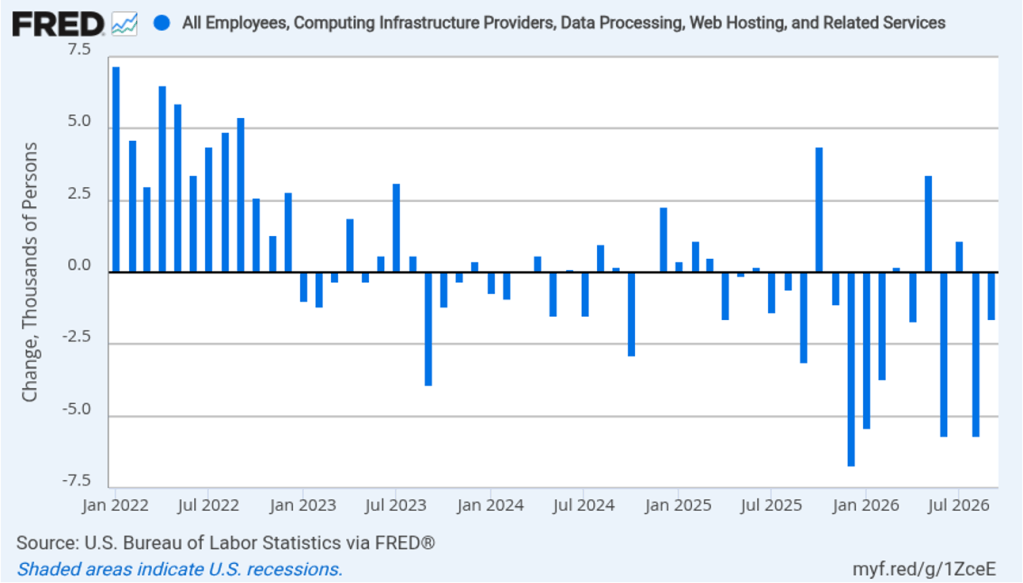
The rapid adoption of artificial intelligence (AI) by many firms has led to forecasts of substantial layoffs of workers in information systems. The following figure shows net employment changes in the BLS employment category of “computing infrastructure providers, data processing, web hosting, and related services.” Employment in this sector has been declining during most months since the beginning of 2023. In September, there was a net decrease of 1,600 jobs.

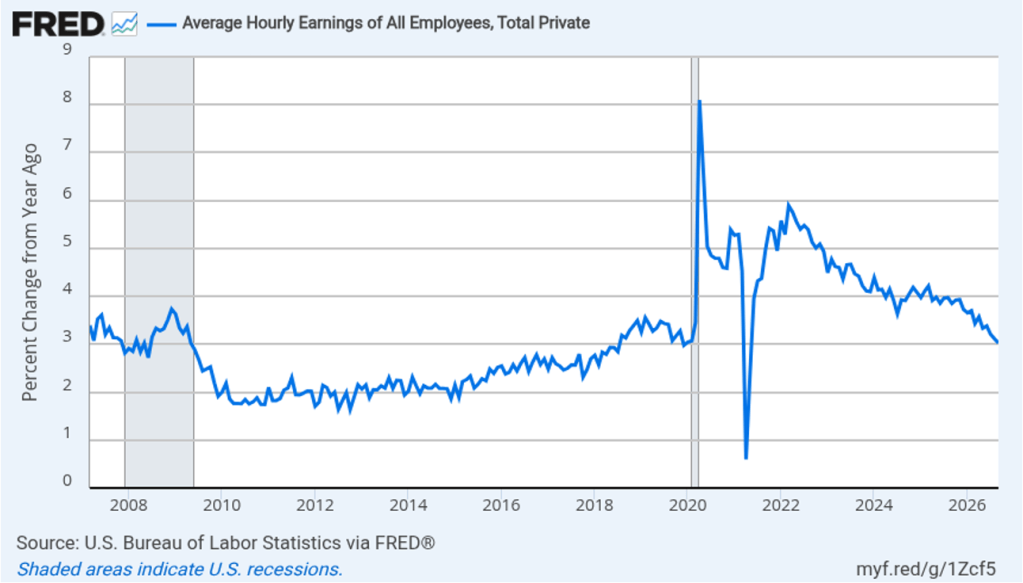
The establishment survey also includes data on average hourly earnings (AHE). As we noted in earlier posts, many economists and policymakers believe the employment cost index (ECI) is a better measure of wage pressures in the economy than is AHE. AHE does have the important advantage of being available monthly, whereas the ECI is only available quarterly. The following figure shows the percentage change in AHE from the same month in the previous year. AHE increased 3.0 percent in September, down from 3.1 percent in August. That was the smallest increase since May 2021. The rate of increase in AHE has been below 4.0 percent each month since August 2025, indicating that cost pressure from wage increases has not been a significant source of price inflation during the past year. Over this same period, wage increases have struggled to keep up with price increases, resulting in a decline in real wages.

With inflation having been above the Federal Reserve’s 2 percent annual target every month since March 2021, the Fed’s policymaking Federal Open Market Committee (FOMC) raised its target range for the federal funds rate at its September meeting. At that time, many analysts expected that the committee would raise its target again at its next meeting on October 27–28.

Trading in the federal funds futures market this morning indicates that investors no longer believe that the committee will increase its federal funds target at its October meeting. A week ago, trading in the federal funds futures market indicated that investors assigned a 64.2 percent to a rate increase at that meeting, while this morning the probability had declined to 21.6 percent. Investors still expect that the committee will increase its target for the federal funds rate at its meeting on December 8–9, although the probability has declined from 92.6 percent a week ago to 85.1 percent today.

New BEA Data Releases Show Higher Growth and Lower Inflation than Expected

Image created by ChatGPT

The Bureau of Economic Analysis (BEA) released two reports this morning (September 30). One report indicated that economic growth was higher in the second quarter of 2026 than the BEA had previously estimated. The other report indicated that inflation as measured by the percentage increase in personal consumption expenditures (PCE) price index was lower than expected.

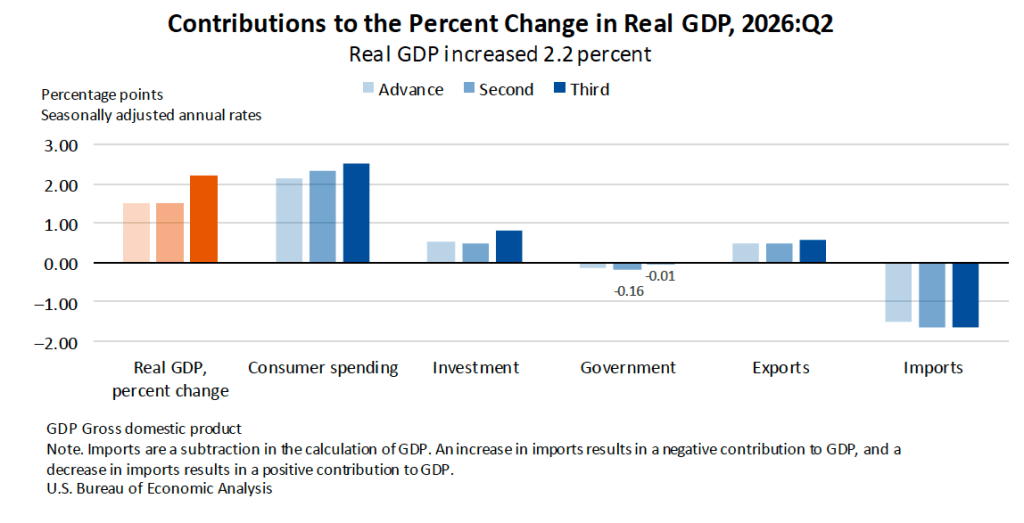
The BEA’s latest estimate is that real GDP increased at an annual rate of 2.2 percent in the second quarter (May, June, and July) of 2026. That is a sharp upward revision of the BEA’s previous estimate that real GDP had increased at an annual rate of 1.5 percent in the second quarter. The following figure from the report shows that upward revisions of investment, consumer spending, and government spending account for the upward revision of real GDP growth. The figure shows the BEA’s advance (original estimate) and two subsequent revised estimates. The BEA revises its estimates of real GDP growth as over time as it collects more complete and accurate data on growth in the components of GDP.

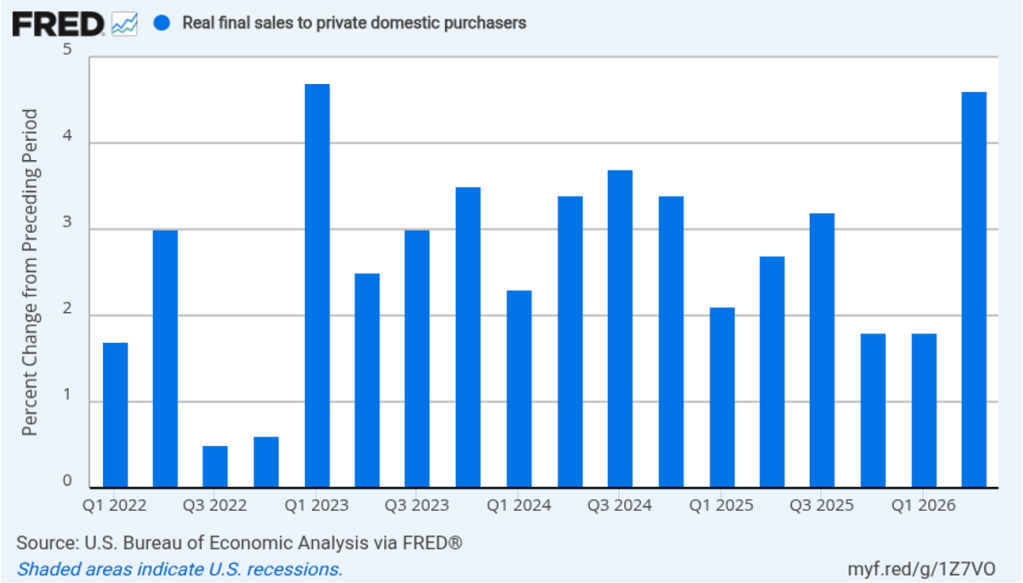
As we’ve discussed in previous blog posts, to better gauge the state of the economy, Federal Reserve policymakers often prefer to strip out the effects of imports, inventory investment, and government expenditures—which can be volatile—by looking at real final sales to private domestic purchasers, which includes only spending by U.S. households and firms on domestic production. As the following figure shows, real final sales to domestic purchasers increased at an annual rate of 4.6 percent in the second quarter, revised upward from 4.4 percent. The growth rate in real final sales to domestic purchasers was more than twice the growth rate of real GDP, as well as much higher than the U.S. economy’s expected long-run annual real growth rate of 1.8 percent. So estimated growth in real final sales to domestic purchasers indicates that the U.S. economy is expanding more rapidly than is indicated by estimated growth in real GDP. Typically, growth in real final sales to domestic purchasers is steadier than growth in real GDP and is likely a better indicator of the underlying growth rate in the economy.

The BEA’s “Personal Income and Outlays” report this morning included monthly data on the personal consumption expenditures (PCE) price index. The Fed relies on annual changes in the PCE price index to evaluate whether it’s meeting its 2 percent annual inflation target. As we noted in an earlier blog post, Fed Chair Kevin Warsh indicated in his press conference following the July meeting of the Federal Open Market Committee (FOMC) that the committee intended to continue using the PCE price index as its gauge of inflation, although that decision would be revisited early next year. Some analysts have interpreted Warsh’s statement that the decision would be revisited next year as an indication that he favored moving to a measure that would show lower rates of inflation than those shown by the PCE.

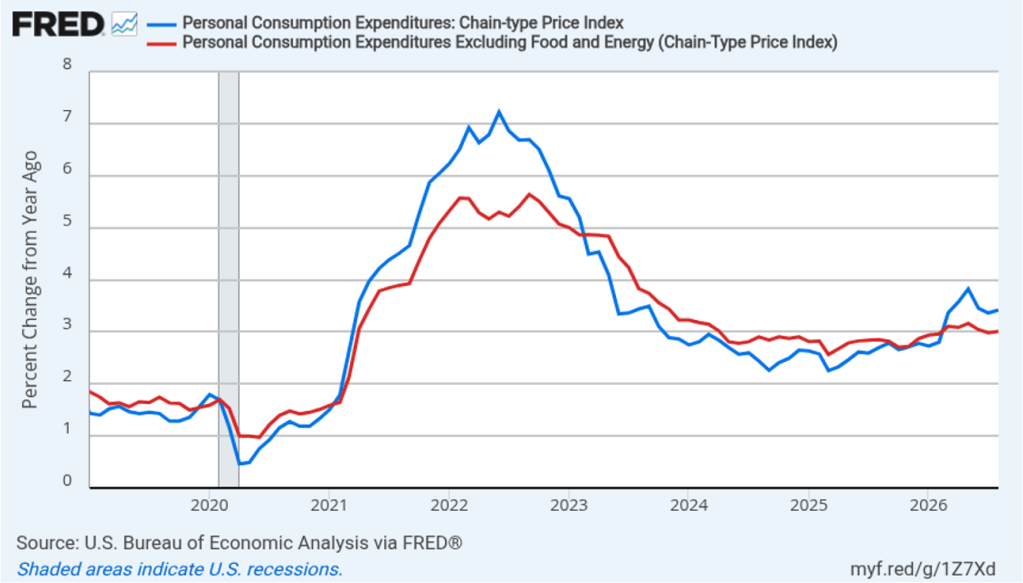
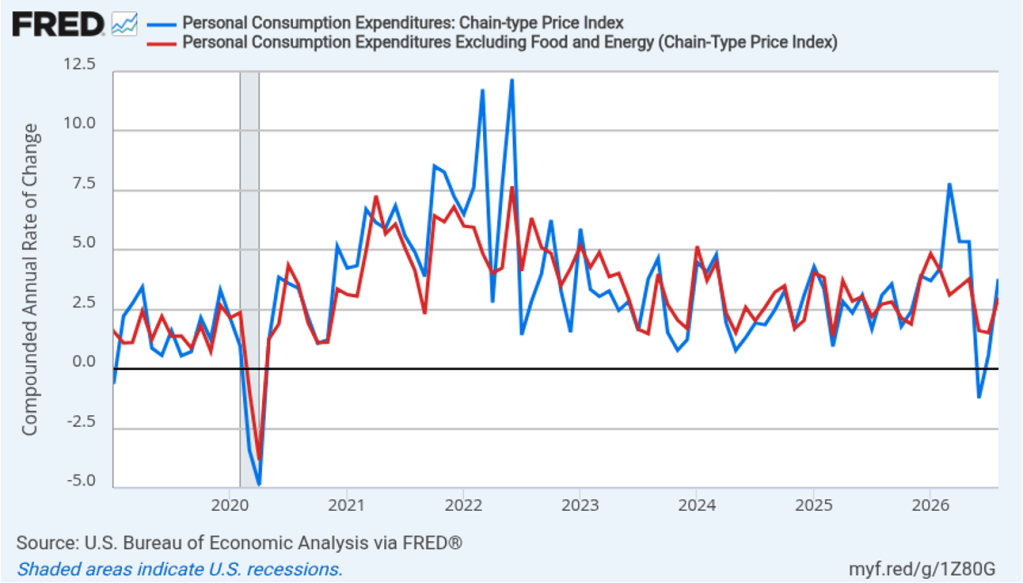
The following figure shows headline PCE inflation (the blue line) and core PCE inflation (the red line)—which excludes energy and food prices—for the period since January 2019, with inflation measured as the percentage change in the PCE from the same month in the previous year. In August, headline PCE inflation was 3.4 percent, unchanged from July. Core PCE inflation in August was 3.0 percent, also unchanged from July. Headline and core PCE inflation were both lower than forecast by economists surveyed by FactSet. Both headline PCE inflation and core PCE inflation remain well above the Fed’s 2 percent annual inflation target.

The following figure shows headline PCE inflation and core PCE inflation calculated by compounding the current month’s rate over an entire year. (Often referred to as 1-month inflation.) Measured this way, headline PCE inflation increased from 0.6 in July to 3.8 percent in August. Core PCE inflation increased from 1.5 percent in July to 3.0 percent in August. In contrast with the 12-month inflation rates, the 1-month inflation rates show noticeable acceleration in inflation during August. Of course, it’s important not to overinterpret the data from a single month.

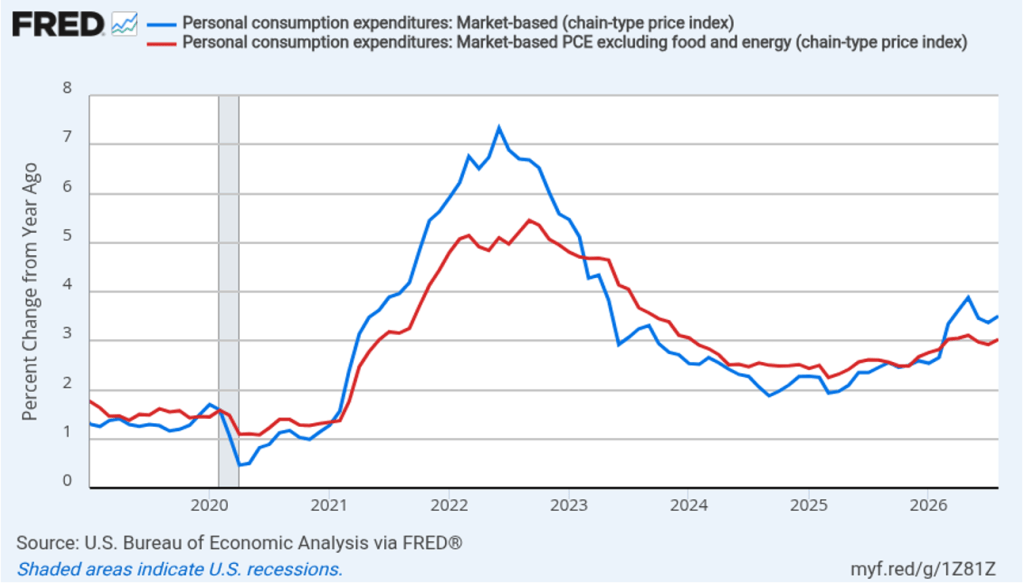
Fed policymakers believe that inflation in non-market services can skew PCE inflation. Non-market services are services whose prices the BEA imputes rather than measures directly. For instance, the BEA assumes that prices of financial services—such as brokerage fees—vary with the prices of financial assets. So that if stock prices rise, the prices of financial services included in the PCE price index also rise. Former Fed Chair Jerome Powell has argued that these imputed prices “don’t really tell us much about … tightness in the economy. They don’t really reflect that.” The following figure shows 12-month headline inflation (the blue line) and 12-month core inflation (the red line) for market-based PCE. (The BEA explains the market-based PCE measure here.)

Headline market-based PCE inflation was 3.5 percent in August, up slightly from 3.4 percent July. Core market-based PCE inflation was 3.0 percent in August, up from 2.9 percent in July. So, both market-based measures show inflation in August remaining well above the Fed’s 2 percent target.

Fed Chair Kevin Warsh argued in testimony at his confirmation hearing before the Senate that the Fed should stop relying on headline PCE inflation: “The measures [of inflation] I prefer are looking at things that are called trimmed averages. We take out all of the tail-risks, all of the one-off items, and we ask ourselves whether the generalized change in prices is having second-order effects on the economy.” 

Trimmed-mean PCE inflation drops the 31 percent of goods and services with the highest inflation rates and the 24 percent of goods and services with the lowest inflation rates. A closely related measure, median PCE inflation, is calculated by listing the inflation rate in each individual good or service included in the PCE and identifying the inflation rate of the good or service that is in the middle of the list—that is, the inflation rate in the price of the good or service that has an equal number of higher and lower inflation rates. 

The following figure shows 12-month headline PCE inflation the (blue line), core PCE inflation (the red line) and trimmed-mean PCE inflation (the green line). Trimmed-mean PCE inflation in August was 2.2 percent, well below both headline and core PCE inflation.

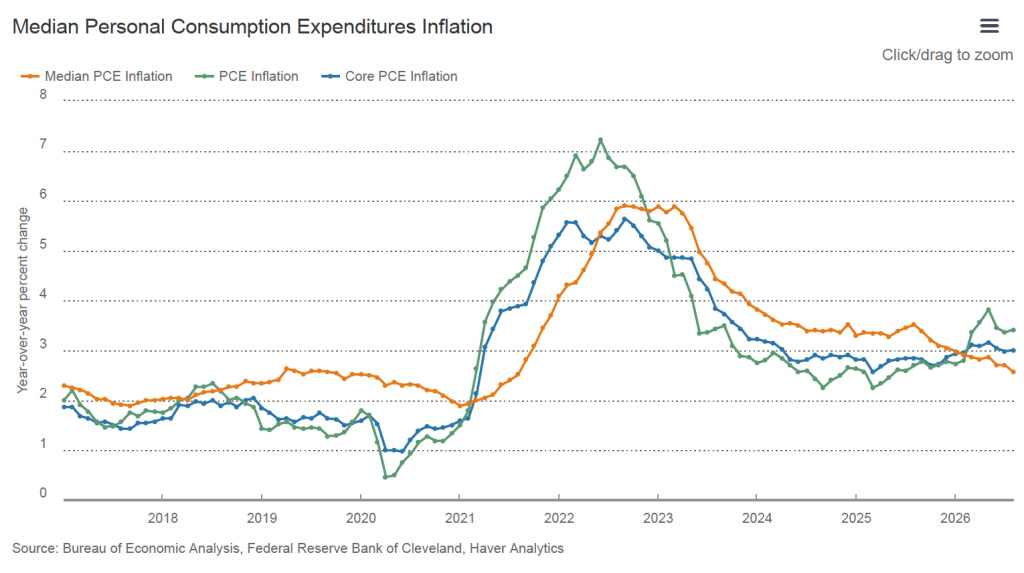
The following figure from the website of the Federal Reserve Bank of Cleveland shows headline PCE inflation (the green line), core PCE inflation (the blue line), and median PCE inflation (the brown line). In August, median PCE inflation was 2.6 percent, which was down from 2.7 percent in July. So Warsh has a point that these two measures of inflation, which are less affected by particularly high or low rates of inflation in some goods and services, indicate that inflation has been running below the Fed’s currently preferred measure. But these measures also show inflation still running well above the Fed’s 2 percent annual inflation target.

Today’s macro data releases appear to have caused of investors who buy and sell federal funds futures contracts to believe that the Federal Open Market Committee (FOMC) is now less likely to raise its target for the federal funds rate at the committee’s next meeting on October 27–28. Trading on the federal funds futures market this afternoon implies that the probability of a target rate increase at that meeting is 39.3 percent, down from a probability of 50.9 percent yesterday.