Image created by ChatGPT
After the Federal Open Market Committee (FOMC) increased its target for the federal funds rate at its September meeting, there was uncertainty as to whether it would raise its target again at its meeting on October 27–28. Today’s report from the Bureau of Labor Statistics (BLS) on the consumer price index (CPI) for September showed that inflation had risen more than expected, likely increase somewhat the probability of the committee raising its target range at its October meeting.
As we’ve noted before, and as we discuss in Macroeconomics, Chapter 15 (Economics, Chapter 25), monetary policy affects the economy with, in the words of Nobel laureate Milton Friedman, “long and variable lags.” As a result, most economists agree that the Federal Reserve should not attempt to “fine tune” the economy by responding to each government release of macroeconomic data. Nevertheless, in practice, it’s clear that during times when Fed policymakers are split over what course of action to take, a single data report can have a significant effect on their decision.
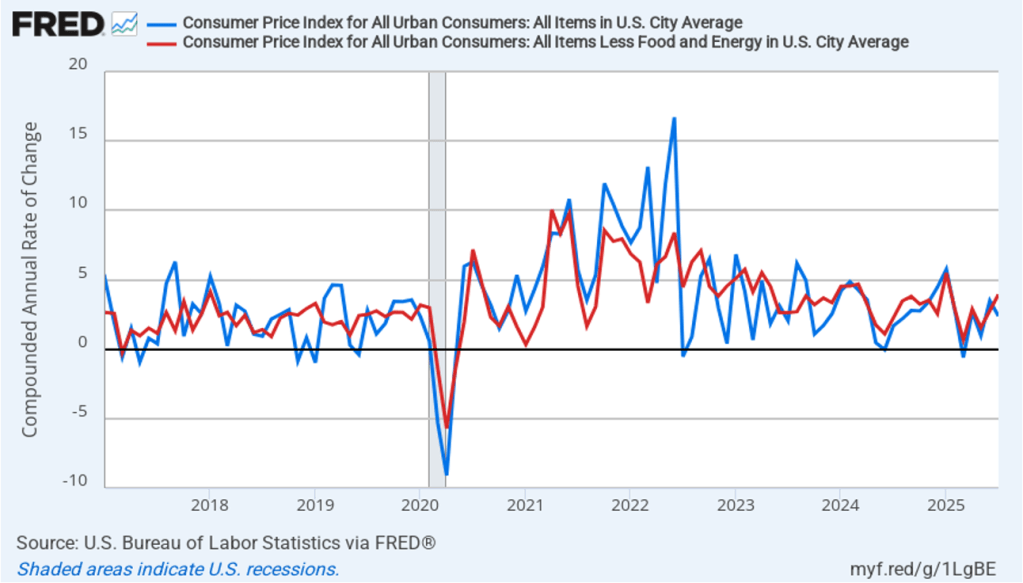
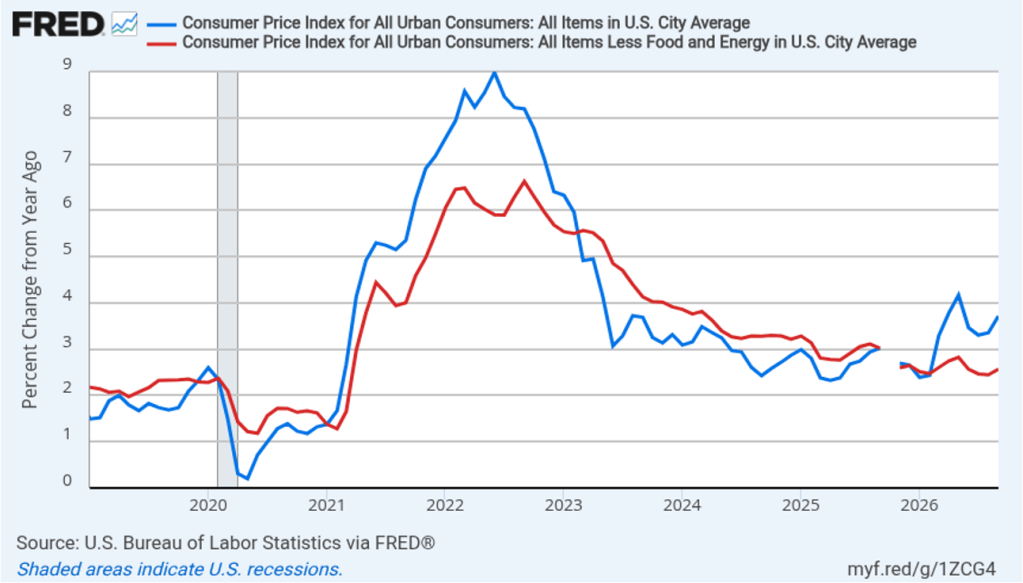
The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).
- The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.7 percent in September, up from 3.4 percent in August.
- The core inflation rate, which excludes the prices of food and energy, was 2.6 percent in September, up from 2.4 percent in August.
Headline inflation and core inflation were both higher than the forecasts of economics surveyed by the Wall Street Journal. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)
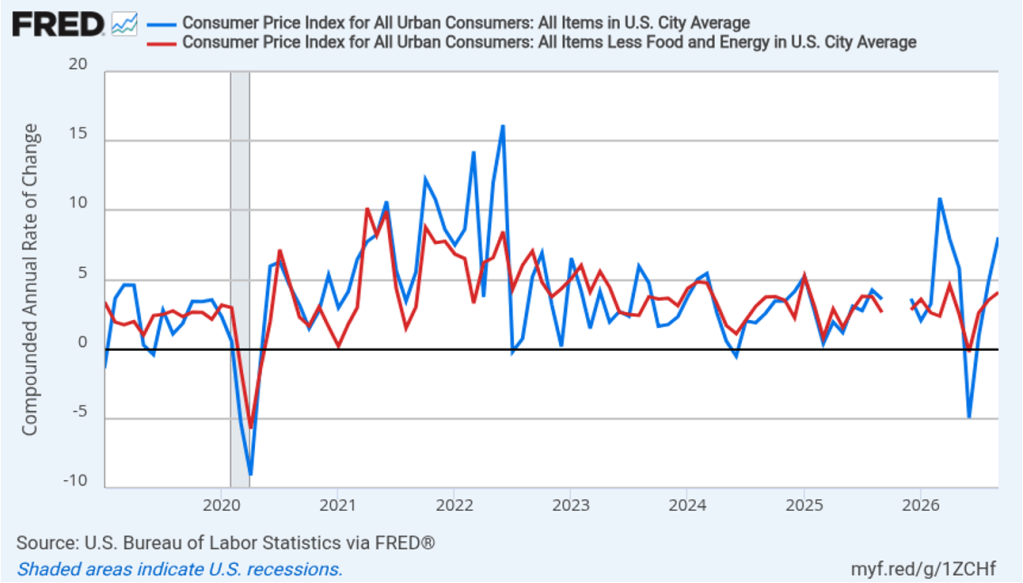
In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline inflation (the blue line) soared to 8.1 percent in September, up from 4.9 percent in August. Core inflation (the red line) was 4.1 percent in September, up from 3.5 percent in August.
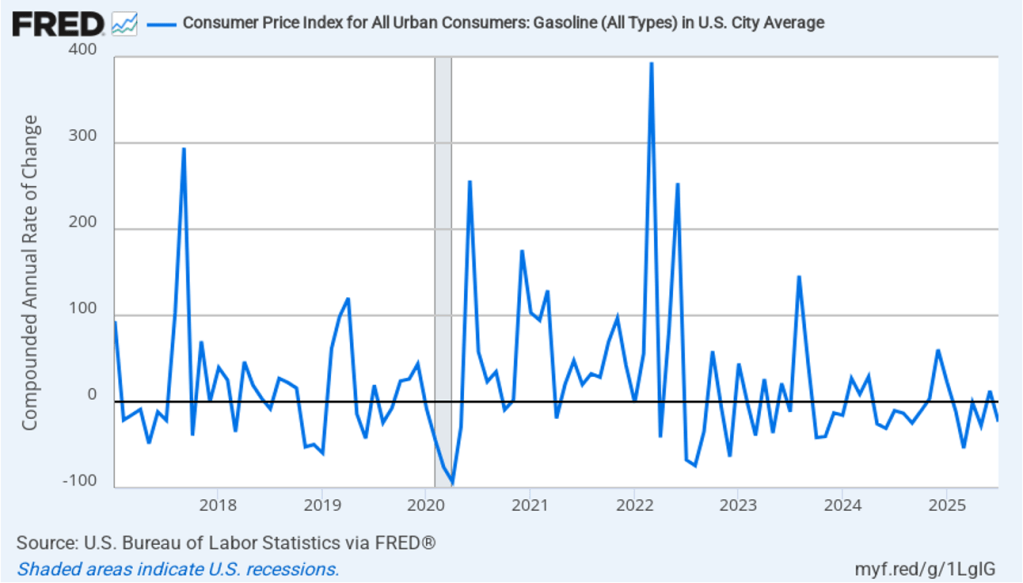
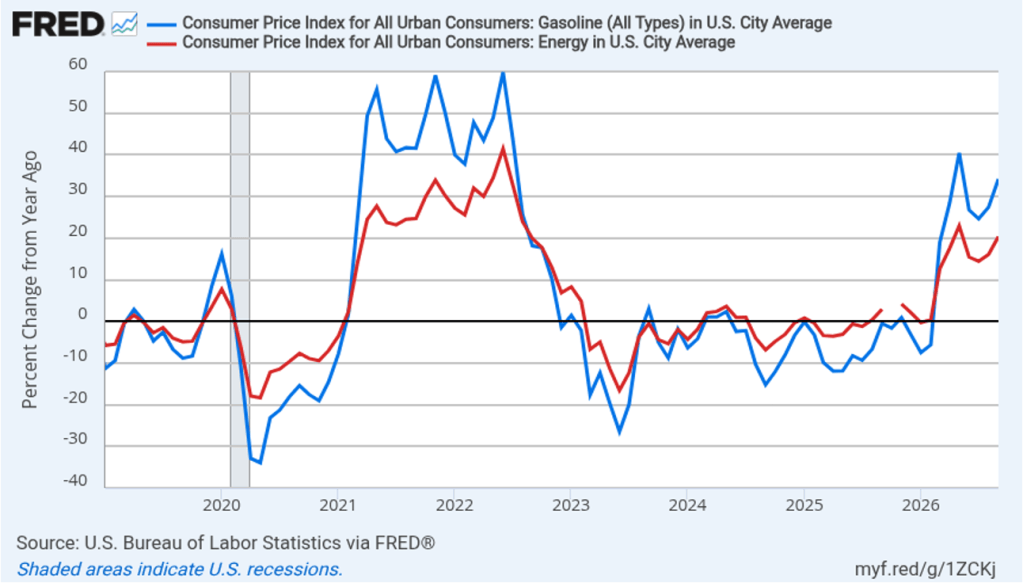
As the large gap between the headline and core 1-month inflation rates indicates, energy prices, particularly gasoline prices, rose sharply in September. In the following figure, the red line shows the 12-month inflation rate in all energy prices included in the CPI. Inflation in energy prices was 20.4 percent in September, up from 16.4 percent in August. The blue line shows the 12-month inflation rate in gasoline prices, which increased to 34.2 percent in September from 27.4 percent in August.
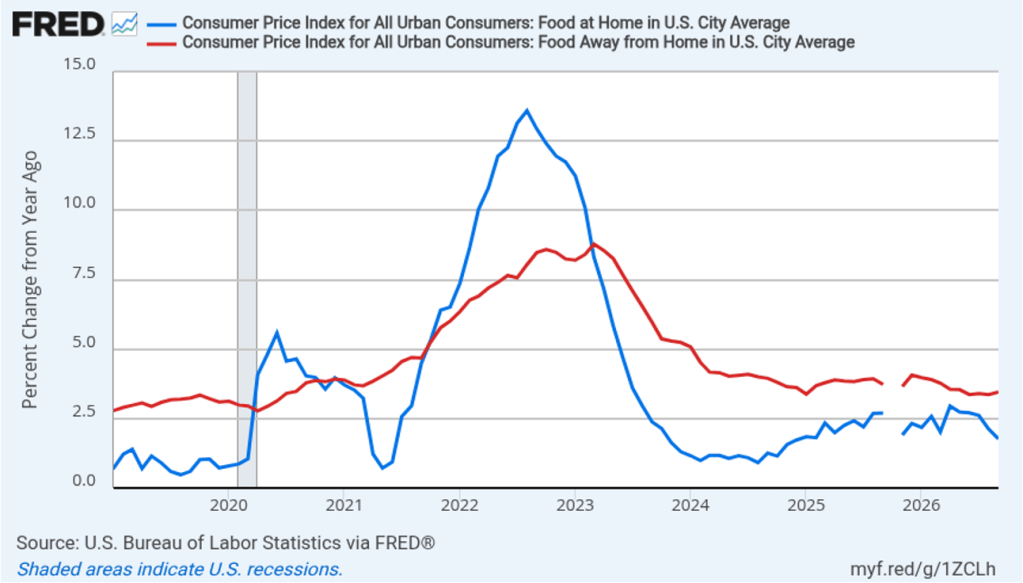
There has been a fear that the rise in energy prices that began in March will pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 12-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and in the category “food away from home” (the red bar)—primarily food purchased at restaurants. Grocery prices increased 3.5 percent in September from a year ago, down from 3.7 percent in August. Restaurant prices increased 3.5 percent from a year ago, up slightly from 3.4 percent in August. To this point, increases in energy prices seem to have had some effect on grocery prices and restaurant prices, although the extent of the effect is unclear.
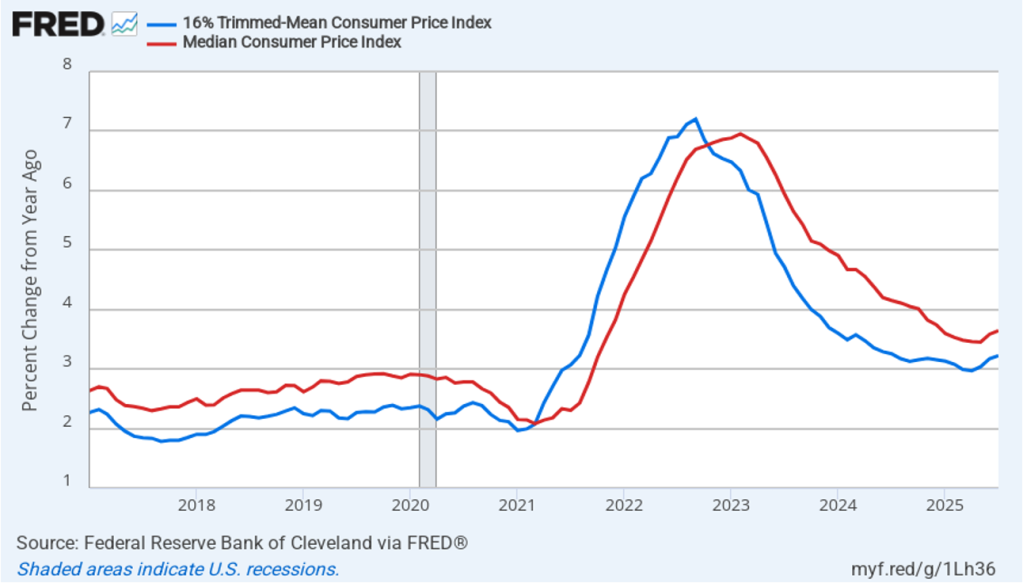
Fed Chair Kevin Warsh has indicated that he favors measures of the inflation rate that exclude particularly small or particularly large changes in the prices of some goods or services—so-called outliers. Median CPI, which is compiled monthly by economists at the Federal Reserve Bank of Cleveland, is calculated by ranking the price changes of every good or service in the index from the largest price change to the smallest price change, and then choosing the price change in the middle. The idea is to eliminate the effect on measured inflation of any short-lived events that cause the prices of some goods and services to be particularly high or particularly low. Economists at the Cleveland Fed have conducted research that shows that, in their words, “the median CPI provides a better signal of the underlying inflation trend than either the all-items CPI or the CPI excluding food and energy. The median CPI is even better at forecasting [personal consumption expenditures] PCE inflation in the near and longer term than the core PCE price index.”
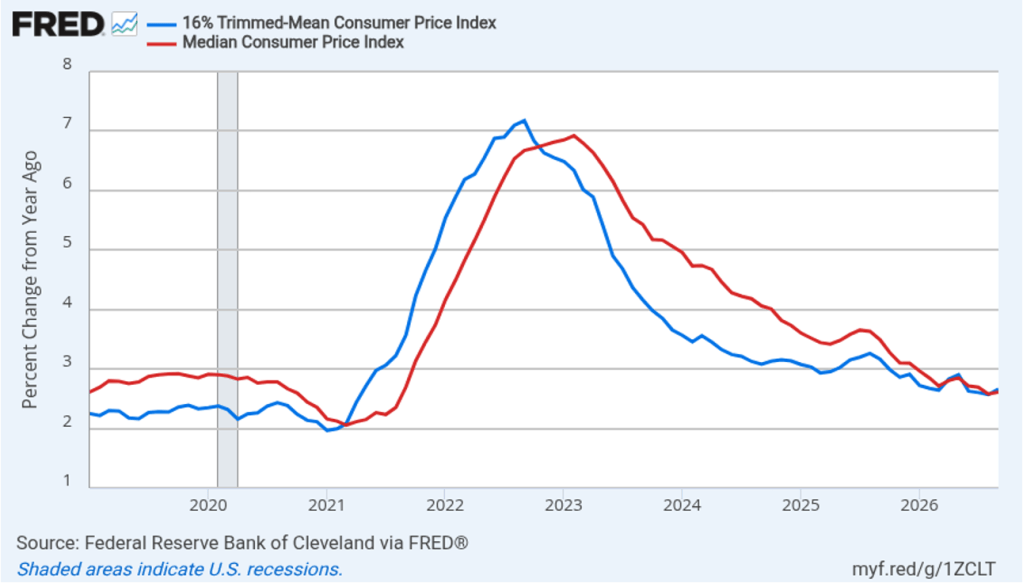
Trimmed-mean inflation, also compiled by economists at the Cleveland Fed, excludes the highest 8 percent of price changes and the lowest 8 percent. The following figure shows 12-month trimmed mean (the blue line) and median (the red line) CPI inflation. Trimmed-mean inflation was 2.7 percent in September, up from 2.6 percent in August. Median inflation was 2.6 percent in September, unchanged from August. So these measures of inflation are both lower than the conventional headline and core CPI inflation measures, which indicates that the acceleration in inflation during September was not affecting all sectors of the economy.
Note that the Fed uses the 12-month change in the personal consumption expenditures (PCE) price index, not the change in the CPI, when gauging whether it is hitting its 2 percent annual inflation target. Historically, PCE inflation has been about 0.4 percentage points to 0.5 percentage points lower than CPI inflation. The Bureau of Economic Analysis (BEA) won’t release its estimate of September PCE inflation until October 29, one day after the next FOMC meeting.
Today’s report showing that inflation remains persistently above the Fed’s 2 percent annual target has likely raised the chance that Federal Reserve policymakers will increase their target range for the federal funds rate from the current 3.75 percent to 4.00 percent by o.25 percentage points (or 25 basis points) at the next meeting of the FOMC on October 27–28. Trading in the federal funds futures market this afternoon indicates that investors assign a 33.8 percent probability to the FOMC raising its target range at that meeting, which is up from a 22.1 percent probability yesterday. Trading indicated that investors assign a 89.7 percent probability to the committee increasing its target range by at least 25 basis points at its last meeting of the year on December 8–9. Some analysts have speculated that the committee will postpone its next rate increase until December to avoid raising the rate before the midterm election on November 3.