No Sign of Cooling Inflation in September CPI Report

Image created by ChatGPT

Today’s report from the Bureau of Labor Statistics (BLS) on the consumer price index (CPI) for August was eagerly awaited by economists and policy analysts. As we discuss in Macroeconomics, Chapter 15 (Economics, Chapter 25), monetary policy affects the economy with, in the words of Nobel Laureate Milton Friedman, “long and variable lags.” As a result, most economists agree that the Federal Reserve should not attempt to “fine tune” the economy by responding to each government release of macroeconomic data.

There are some instances, however, including the present, when the Fed’s policymaking Federal Open Market Committee (FOMC) appears to be uncertain as to whether a change in policy is needed. As a result, there was a widespread expectation that if today’s report indicated that inflation is slowing, the FOMC would likely leave its target for the federal funds rate unchanged at its meeting on Tuesday and Wednesday of next week. But if the report didn’t indicate that inflation is slowing, the committee would likely raise its target. The report gave few indications that inflation is slowing.

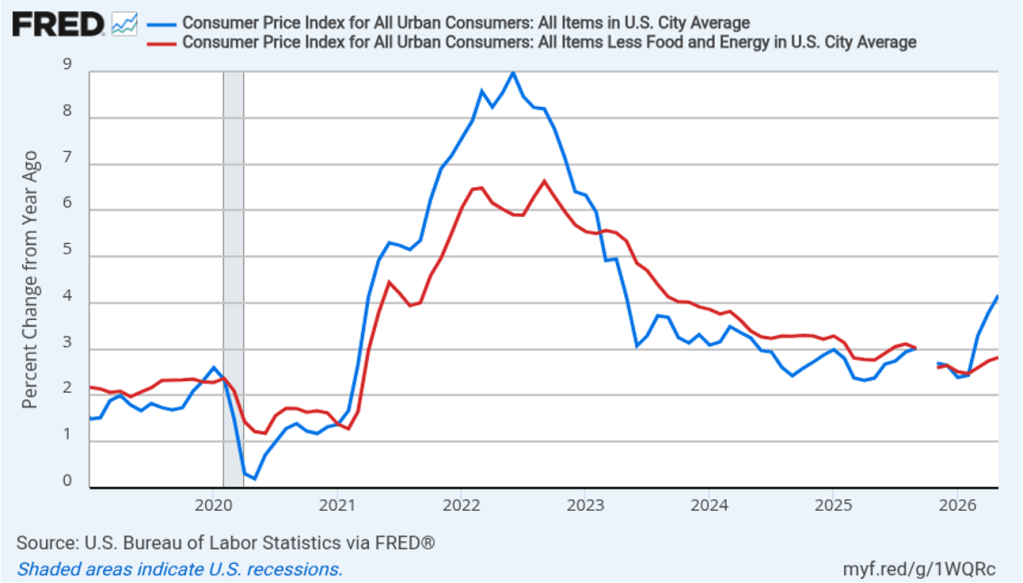
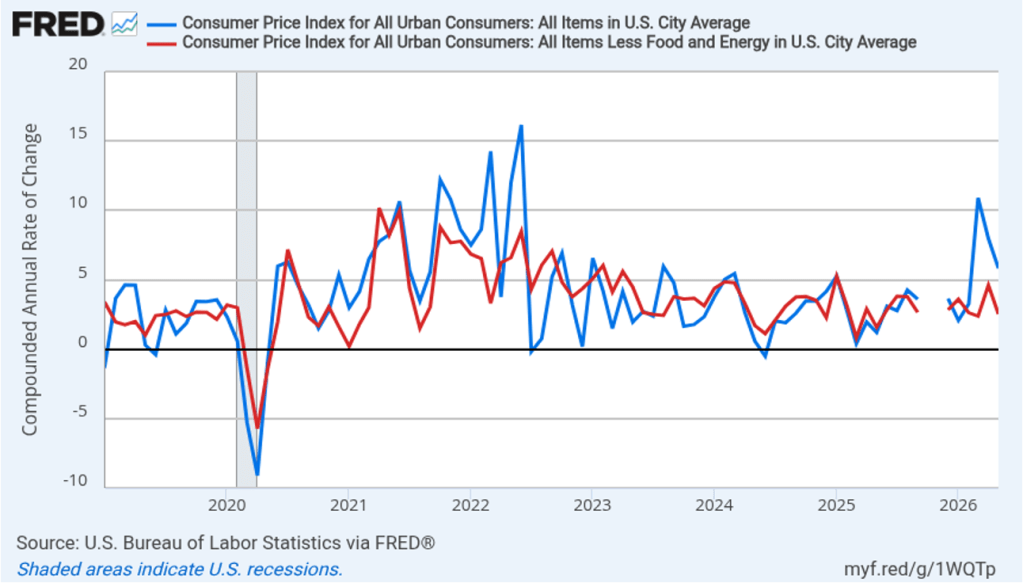
The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).

  • The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.4 percent in August, the same as in July. 
  • The core inflation rate, which excludes the prices of food and energy, was 2.4 percent in August, down from 2.5 in July.  

Headline inflation was slightly higher, and core inflation was equal, to the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)

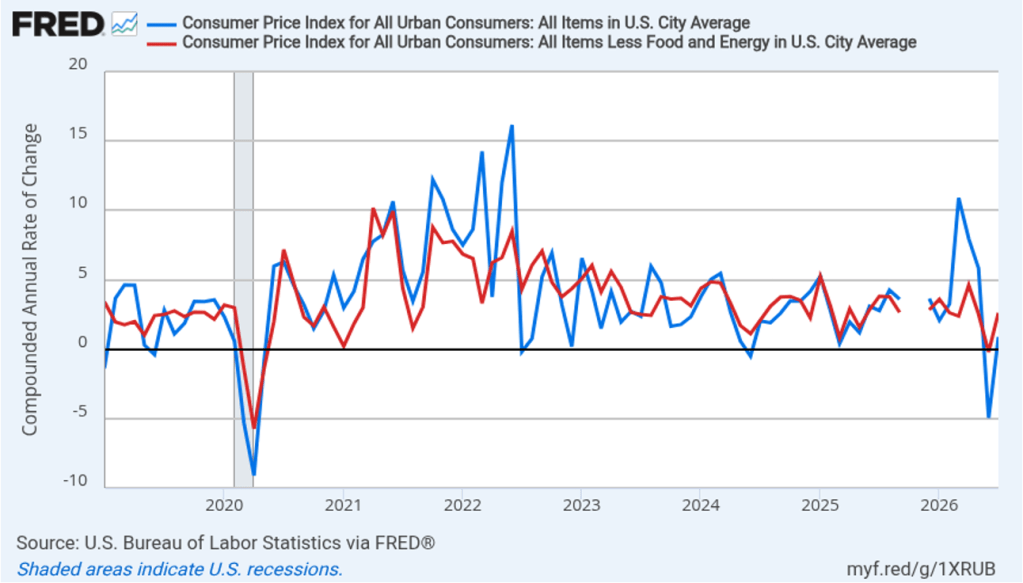
In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline (the blue line) was 4.6 percent In August, up from 0.9 percent in July. Core inflation (the red line) was 3.5 percent in August, up from 2.6 percent in July.

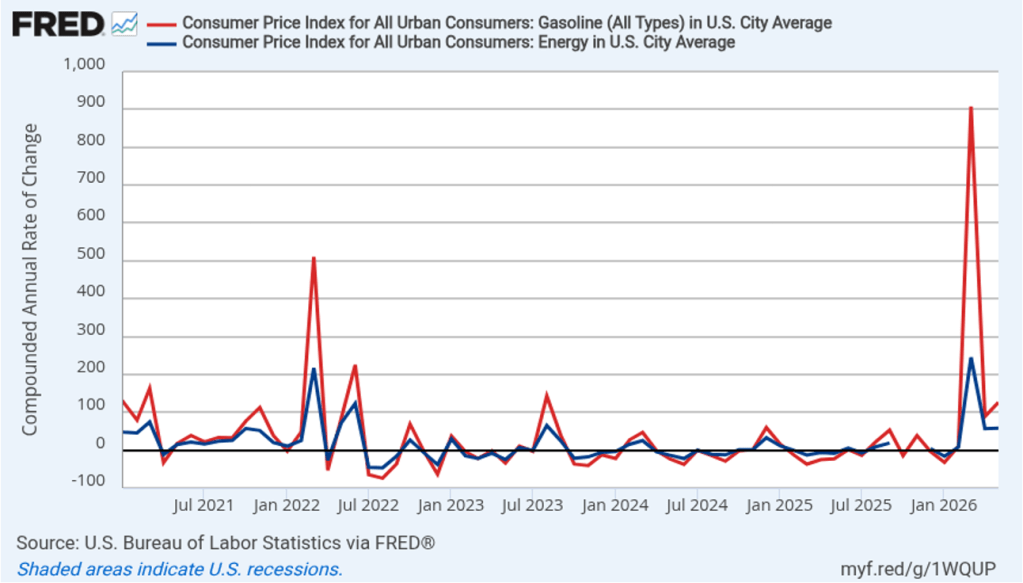
The following figure illustrates the role played by energy prices in contributing to the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had declined at an annual rate of 16.4 percent in July, increased at an annual rate of 28.3 percent in August. The blue line shows the 1-month inflation rate in gasoline prices, which had declined at an annual rate of 29.4 percent in July, increased at an annual rate of 58.3 percent in August.

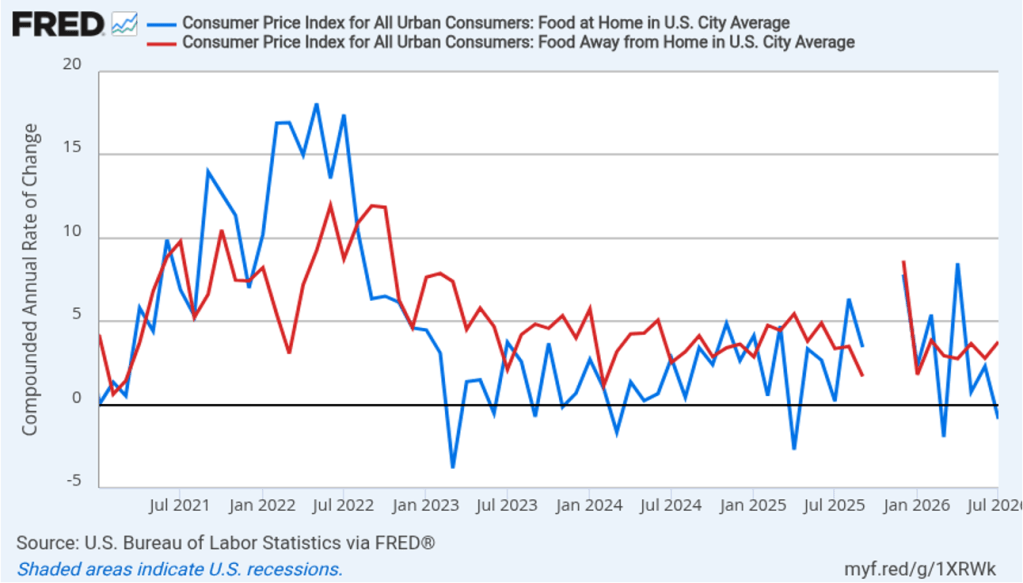
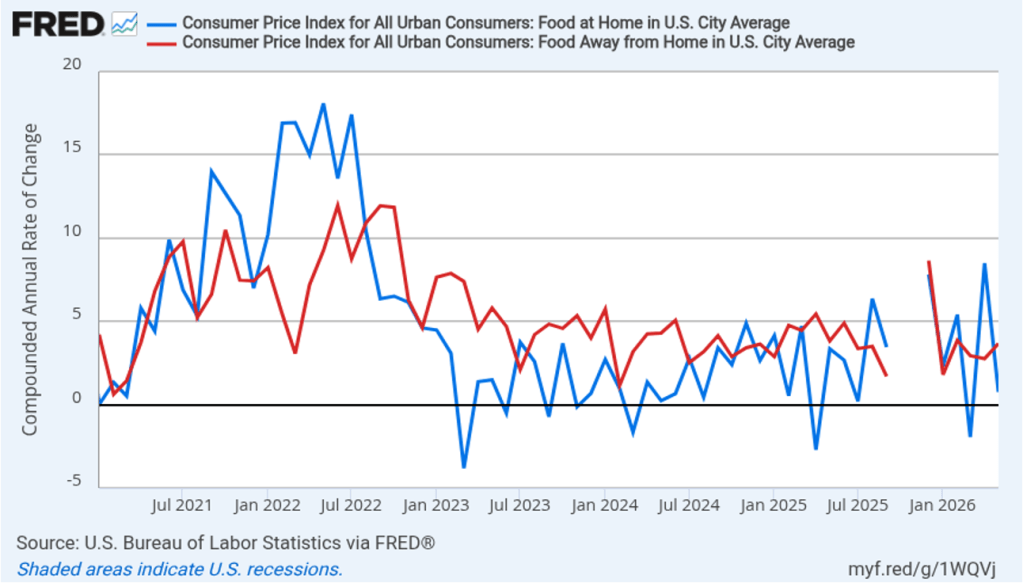
There had been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and in the category “food away from home” (the red bar)—primarily food purchased at restaurants. Grocery prices, which had declined at annual rate of 0.9 percent in July, increased at an annual rate of 0.4 percent in August. Food prices away from home increased 3.1 percent in August, down from 3.9 percent in July. To this point, increases in energy prices seem to have had some effect on grocery prices and restaurant prices, although the extent of the effect is unclear.

Fed Chair Kevin Warsh has indicated that he favors measures of the inflation rate that exclude particularly small or particularly large changes in the prices of some goods or services—so-called outliers. Median CPI, which is compiled monthly by economists at the Federal Reserve Bank of Cleveland, is calculated by ranking the price changes of every good or service in the index from the largest price change to the smallest price change, and then choosing the price change in the middle. The idea is to eliminate the effect on measured inflation of any short-lived events that cause the prices of some goods and services to be particularly high or particularly low. Economists at the Cleveland Fed have conducted research that shows that, in their words, “the median CPI provides a better signal of the underlying inflation trend than either the all-items CPI or the CPI excluding food and energy. The median CPI is even better at forecasting [personal consumption expenditures] PCE inflation in the near and longer term than the core PCE price index.”

Trimmed-mean inflation, also compiled by economists at the Cleveland Fed, excludes the highest 8 percent of price changes and the lowest 8 percent. The following figure shows 1-month trimmed mean (the blue line) and median (the red line) CPI inflation. Trimmed-mean inflation was 2.7 percent in August, unchanged from July. Median inflation was 2.1 percent in August, down from 3.1 percent in July. So these measures of inflation are both lower than the conventional headline and core CPI inflation measures, although as the figure shows, both measures are volatile.

Note that the Fed uses the 12-month change in the personal consumption expenditures (PCE) price index, not the change in the CPI, when gauging whether it is hitting its 2 percent annual inflation target. Historically, PCE inflation has been about 0.4 percentage points to 0.5 percentage points lower than CPI inflation. The Bureau of Economic Analysis (BEA) won’t release its estimate of August PCE inflation until September 30, after the next FOMC meeting.

Today’s report showing that inflation remains persistently above the Fed’s 2 percent annual target, following last week’s jobs report showing an unexpectedly large increase in employment, has likely raised the chance that Federal Reserve policymakers will increase their target range for the federal funds rate from the current 3.50 percent to 3.75 percent by o.25 percentage points (or 25 basis points) at the next meeting of the FOMC on September 15–16. Trading in the federal funds futures market this afternoon indicates that investors assign a 86.5 percent probability to the FOMC raising its target range at that meeting, which is up from a 72.4 probability yesterday. Trading indicated that investors assign a 74.5 percent probability to the committee increasing its target range by at least 50 basis points by the end of the year, up from 64.6 percent yesterday and from 44.7 percent one week ago.
As Expected, CPI Inflation Falls Slightly in July

Image created by ChatGPT

Today (August 12), the Bureau of Labor Statistics (BLS) released its report on the consumer price index (CPI) for July. Lower energy and grocery prices contributed to a slight decline in the inflation rate in July compared with June.

The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).

  • The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.4 percent in July, down from 3.5 percent in June. 
  • The core inflation rate, which excludes the prices of food and energy, was 2.5 percent in July, down from 2.6 in June.  

Headline inflation and core inflation were both equal to the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)

In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, both headline (the blue line) and core inflation (the red line) increased in July from the negative values in June. That is, the U.S. economy experienced deflation in June because the price level, measured by the CPI and by the CPI less food and energy prices, fell in that month.

In July, 1-month headline CPI inflation was 0.9 percent and 1-month core CPI inflation was 2.6 percent.

The following figure illustrates the role played by energy prices in contributing to the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had increased at annual rate of 245 percent in March, declined at an annual rate of 16.4 percent in July. The blue line shows the 1-month inflation rate in gasoline prices, which in March had spiked to more than 900 percent measured at an annual rate, declined at an annual rate of 29.4 percent in July. A return to full-scale hostilities in the Middle East would increase oil prices, which would likely lead to an increase in the U.S. inflation rate.

There had been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and the category “food away from home” (the red bar)—primarily food purchased at restaurants. Inflation in grocery prices, which increased 2.3 percent in June, declined 0.9 percent in July. Inflation in food prices away from home increased from 2.8 percent in June to 3.8 percent in July. To this point, increases in energy priced do not seem to have caused a significant increase in either grocery prices or restaurant prices.

Today’s relatively good inflation report, following last week’s report showing an unexpected decline in employment, has likely reduced the chance that Federal Reserve policymakers will increase their target for the federal funds rate at the next meeting of the Federal Open Market Committee (FOMC) on September 15–16. In trading in the federal funds futures market this afternoon, investors assigned a 62.1 percent probability to the FOMC keeping its target unchanged at that meeting, which was up from a 51.6 probability yesterday. Traders assign a 53.2 percent probability to the committee increasing its target at its October 27–28 meeting, down from 62.2 percent yesterday.

It’s worth noting, however, that inflation is still running above the Federal Reserve’s 2 percent annual inflation target. In testimony before Congress in a hearing on his nomination as Fed Chair, Kevin Warsh cautioned that good news in a single month’s inflation report should be treated with caution. Warsh has intentionally moved away from discussing the circumstances under which monetary policy might change in the future—so-called forward guidance. (We discuss forward guidance in Macroeconomics, Chapter 15 (Economics, Chapter 25)). Uncertainty about actions the FOMC may take during its three remaining meeting this year remains high.

CPI Inflation Comes in Below Expectations

Image created by ChatGPT

Today (July 14), the Bureau of Labor Statistics (BLS) released its report on the consumer price index (CPI) for June. In May, higher energy prices caused by the conflict in Iran contributed to inflation increasing to the highest rate in more than three years. In June, as energy prices decreased, inflation experienced the largest one-month decrease since April 2020.

The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).

  • The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.5 percent in June, down from 4.2 percent in May. 
  • The core inflation rate, which excludes the prices of food and energy, declined from 2.8 percent in May to 2.6 percent in June. 

Headline inflation and core inflation were both well below the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October and November 2025 are not available.)

In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, both headline (the blue line) and core inflation (the red line) were negative in June. That is, the U.S. economy experienced deflation last month because the price level, measures by the CPI and by the CPI less food and energy prices, fell in June.

The following figure illustrates the role played by energy prices in causing the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had increased at annual rate of 245 percent in March, fell at annual rate of 50.6 percent in June. The blue line shows the 1-month inflation rate in gasoline prices, which in March had spiked to more than 900 percent measured at an annual rate, fell at an annual rate of 70.6 percent in June. The recent escalation in the conflict in Iran has increased oil prices, which will likely lead to an increase in the inflation rate in July.

There has been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and the category “food away from home” (the red bar)—primarily food purchased at restaurants. Inflation in grocery prices increased from 0.8 percent in May to a still fairly low 2.3 percent in June. Inflation in food prices away from home fell from 3.7 percent in May to 2.8 percent in June. To this point, increases in energy priced do not seem to have had much effect on grocery prices or on restaurant prices.

The unexpectedly large decline in inflation in today’s report has likely reduced the chance that Federal Reserve policymakers will increase their target for the federal funds rate at the next meeting of the Federal Open Market Committee (FOMC) on July 28–29. In trading in the federal funds futures market this morning, investors assigned a 83.4 percent probability to the FOMC keeping its target unchanged, which was up sharply from a 58.3 probability yesterday. Traders assign a 61.3 percent probability to the committee increasing its target at its September 15–16 meeting, down from 75.1 percent yesterday.

In testimony before Congress today after the CPI report was released, Fed Chair Kevin Warsh cautioned that good news in a single month’s inflation report should be treated with caution: “There might be some who look at today’s data and say ‘mission accomplished.’ That is not my view.”

CPI Inflation Highest Since 2023, but Slightly Below Expectations

Image generated by ChatGPT

Today (June 10), the Bureau of Labor Statistics (BLS) released its report on the consumer price index (CPI) for May. As expected, higher energy prices caused by the conflict in Iran have continued to result in high rates of inflation. The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).

  • The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 4.2 percent in May, up from 3.8 in April. This was the highest inflation rate since April 2023.
  • The core inflation rate, which excludes the prices of food and energy, ticked up only slightly to 2.8 percent in May from 2.7 percent in April. 

Headline inflation was equal to and core inflation was slightly lower than economists surveyed by FactSet had forecast. (Note that because of last year’s federal government shutdown, inflation data for October and November 2025 are not available.)

In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline inflation (the blue line) was high at 5.8 percent in May, but down from a very high 8.0 percent in April and 10.9 percent in March. Core inflation (the red line) was 2.5 percent in May, down significantly from 4.6 percent in April.

The following figure emphasizes the role played by energy prices in causing the jump in inflation. The blue line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices increased from a very high 56.6 percent in April to a slightly higher 58.8 percent in May. The red line shows the 1-month inflation rate in gasoline prices, which rose from a very high 88.8 percent in April to an even higher 126.4 percent in May.

Did the jump in energy prices pass through to increases in food prices, which are a key concern for many consumers? The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and the category “food away from home” (the red bar)—primarily food purchased at restaurants. Inflation in grocery prices slowed markedly to 0.8 percent in May from 8.5 percent in April. Inflation in food prices away from home was 3.7 percent in May, up from 2.8 percent in April. April’s very high rate of increase in grocery prices was due to rising energy prices, but also to sharp increases in beef and fruit and vegetable prices, which had risen for reasons largely unrelated to higher energy costs. Consumers enjoyed some relief in May from the sharp decrease in the rate of increase in grocery prices.

This inflation report is unlikely to have much effect on Fed policymakers as they prepare for the next meeting of the Federal Open Market Committee (FOMC) on June 16–17—Kevin Warsh’s first meeting as Fed chair. Persistently high inflation rates combined with relatively strong data on economic growth and employment make it more likely that the FOMC will increase, rather than cut, its target for the federal funds rate later in the year.

At this point, trading in the federal funds futures market indicates that investors believe that its unlikely that the committee will raise or lower its target for the federal funds rate at its June, July, or September meetings. This morning, investors assigned a 48.6 percent probability of the FOMC raising its target for the federal funds rate at its October 27–28 meeting and a 66.2 percent of doing so at its meeting on December 8–9.