Solved Problem: Anthropic Is Losing Money So How Can It Be Worth $1.5 Trillion?

Supports: Microeconomics, Chapter 8, Macroeconomics, Chapter 6, and Money, Banking, and the Financial System, Chapter 6
Image created by ChatGPT

A firm’s initial public offering (IPO) is the first time it sell stock to the public. The total value of a firm’s outstanding shares of stock is called the firm’s market capitalization, or market cap. According to an article in the Wall Street Journal, the AI firm Anthropic was expecting that the price of the stock in its IPO would result in the firm having a market cap of $1.5 trillion. Before a firm can undertake an IPO it must file an S1 form with the Securities and Exchange Commission, disclosing all the information that would be relevant to investors who are considering buying the firm’s stock. In its S1, Anthropic noted that, although in the previous quarter it had revenue of $17.0 billion, it had suffered a net loss of $23.3 billion.

Explain how a firm that is losing billions of dollars can have a market cap of $1.5 trillion.

Solving the Problem

Step 1: Review the chapter material. This problem is about how investors value a firm’s stock, so you may want to review Microeconomics, Chapter 8, “The Fluctuating Stock Market,” (Macroeconomics, Chapter 6) or the more complete discussion in Money, Banking, and the Financial System, Chapter 6, “The Fundamental Value of Stock.”

Step 2: Answer the question by explaining how investors value a firm’s stock. Ownership of a firm’s stock represents a claim on the firm’s profits. So we would expect that the larger a firm’s profits are, the higher the firm’s stock price (and market cap) will be. But a key point is that investors’ demand for a firm’s stock is based less on the current profitability of a firm than on the firm’s expected future profitability. If you own a stock in a profitable firm, the firm will pay you dividends. Therefore, the fundamental value of a share of stock is equal to the present value of the dividends to be received from owning that share. (We show the arithmetic of valuing stocks in Chapter 6 of Money, Banking, and the Financial System.)

Anthropic was expecting to be able to price its IPO to give the firm a market cap of $1.5 trillion despite currently experiencing billions of dollars in losses. We can conclude that investors must be expecting the firm to earn enough profits in the future to justify that high valuation. Of course, investors’ expectations could be wrong (they frequently are!) and Anthropic may never earn profits high enough to justify its IPO price.
Are Worker Income Gains Being Eaten Up by Medical Expenses?

Image created by ChatGPT

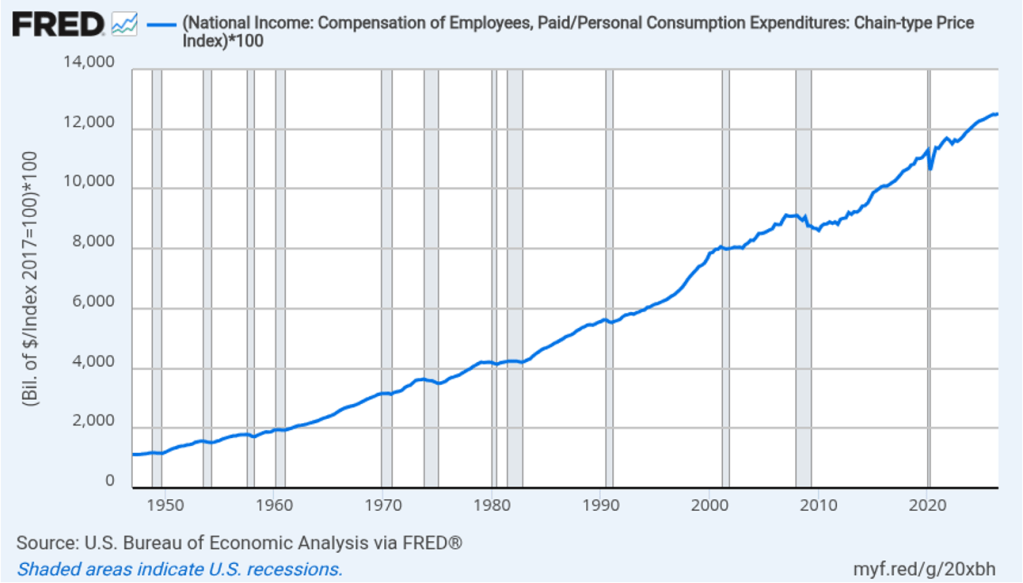
The real incomes of U.S. workers can fluctuate in the short run, but over the long run, incomes have steadily increased. We usually think of income as the wages and salaries that people receive, but as we discuss in Microeconomics, Chapter 7, Section 7.4, when workers choose among jobs, they take into account not just the wages they will receive but also other compensation, such as employer contributions to retirement accounts and employer-provided health insurance.

The following figure shows total compensation paid by employers as presented in the National Income and Product Accounts, corrected for inflation using the personal consumption expenditures (PCE) price index. (The result using the consumer price index (CPI) rather than the PCE is very similar.)

The BEA also compiles data on “supplements to wages and salaries,” which is the part of employee compensation comprised of “employer contributions for employee pension and insurance funds and of employer contributions for government social insurance.” These supplements are sometimes called fringe benefits, although the BEA includes some benefits, such as paid holidays, vacations, sick leave, in wages and salaries. Employer contributions for government social insurance are payments firms make on behalf of employees to mandatory government programs, the most important of which are Social Security and Medicare.

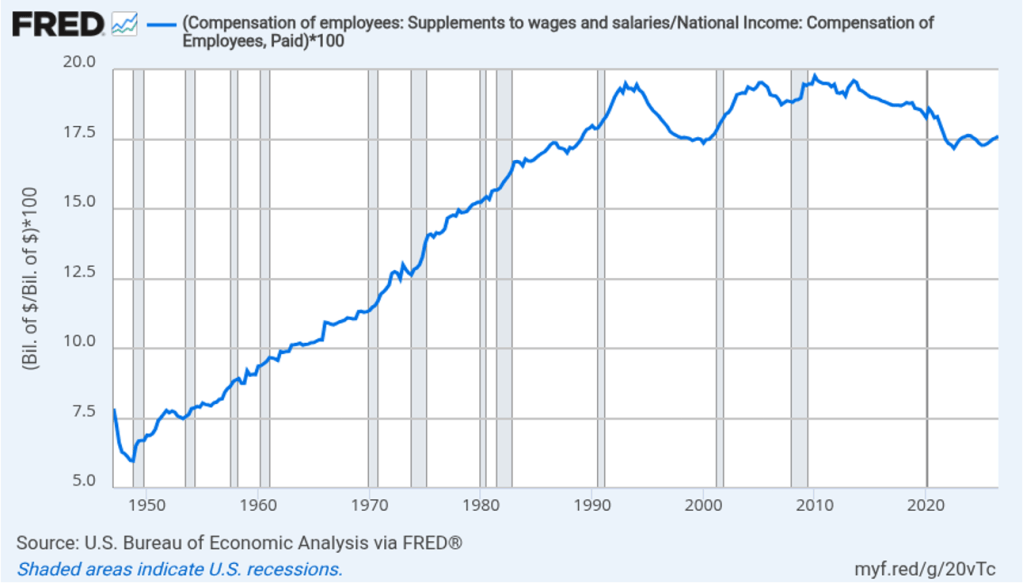
As the following figure shows, supplements to wages and salaries increased as percentage of compensation from 1949 to 1993, rising from 6 percent of total compensation in 1949 to over 19 percent in 1993. There were several factors causing this increase, including: 1. The increase in the Social Security tax rate that employers pay on behalf of employees from 1.5 percent of wages and salaries in 1950 to 6.2 percent in 1990; 2. the imposition beginning in 1966 of an employer-paid tax of 1.45 percent of wages and salaries to fund the Medicare system; 3. the increase in employer contributions to worker pension plans; and 4. the increase in employer contributions to employee health insurance from 0.51 percent of wages and salaries in 1950 to 6.14 percent in 1993.

The growth in employer contributions to health insurance plans for their employees was facilitated by a decision by the U.S. Treasury in 1943 during World War II. That ruling excluded the payments firms made to health insurance plans from the taxable income of employees. At that time, the federal government had put a legal ceiling on wages, which caused employers to search for an alternative way to increase employee compensation. In 1956, Congress amended the Internal Revenue Code to ratify the Treasury’s earlier decision. As a result, the total tax that employees pay on their compensation is reduced when the compensation takes the form of non-taxable employer contributions to health insurance plans. That fact helps explain why the majority of people in the United States with private health insurance receive the insurance through their employers.

The above figure shows that fringe benefits as percentage of total compensation fluctuated between 1993 and 2013 and have trended gradually down in the years since. The gradual decrease since 2013 has been mainly due to small decreases in employer contributions to employee pension and health insurance plans.

Image created by ChatGPT

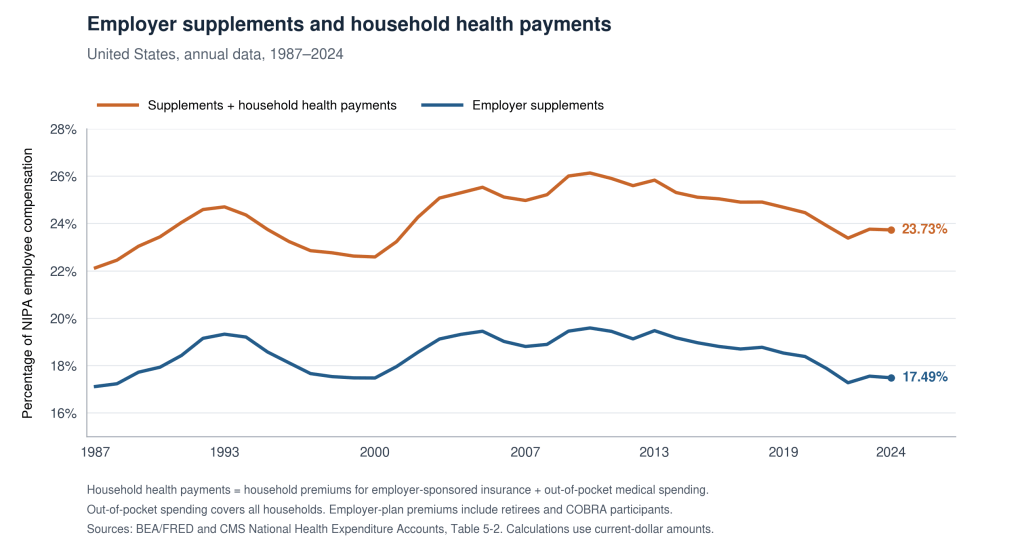
As employer contributions to employee health insurance plans have declined somewhat, the amount that employees have to contribute to those plans and the amount of medical expenses that they have to pay for themselves, so-called out-of-pocket spending, have increased. Has this increased spending on health care offset the increases in wages and salaries employees receive from firms? The Centers for Medicare and Medicaid Services (CMS) provide data for the period from 1987 to 2024 on spending by households on employer-provided health insurance and household out-of-pocket medical spending. The following figure shows the BEA measure of supplements (or fringe benefits) to wages and salaries (the blue line) and supplements plus the CMS measure of household health spending (the brown line) as percentages of the compensation of employees.

During the period from 1987 to 2024, real employee compensation increased about 130 percent. Employer supplements increased only from 17.1 percent of compensation in 1987 to 17.4 percent in 2024, while supplements plus household health spending increased from 22.1 percent of compensation to 23.7 percent.

Medical expenses haven’t increased as a percentage of employee compensation. So in that sense, employees’ significant real income gains weren’t eaten up by increasing medical expenses. It’s important to note, however, that this observation does not mean that there aren’t reforms that would increase the efficiency of the U.S. health care system. We discuss the debate over health care reforms in Microeconomics, Chapter 7.

Is Video Streaming Going Back to the Future?

Image created by ChatGPT

By the early 1950s, a majority of American households owned television sets.  For many years, the only way you could view an episode of a series or a movie was to watch it at the time it was broadcast. Television networks typically broadcast only one episode of a series per week and broadcast new episodes only during the prime-time hours from 7:30 pm to 11:00 pm. (There were a few exceptions, such as the Batman series that the ABC network broadcast twice per week 1960s and the Who Wants to Be a Millionaire quiz show that ABC broadcast multiple times per week in the early 2000s.)

Image created by ChatGPT

In the late 1970s, first Sony and then other firms began selling videocassette recorders (VCRs), which for the first time allowed people to both buy prerecorded movies and to record TV shows that they could play back whenever they chose to. In the late 1990s, first Toshiba, followed by Panasonic and Sony began to selling DVD players in the United States. The release of entire seasons of TV series on DVDs made it possible to binge watch by viewing multiple episodes in one sitting.

Image created by ChatGPT of a 1980s VCR

As we discuss in Microeconomics, Chapter 14, in 1997, Reed Hastings and Marc Randolph founded Netflix. For a subscription fee of $15.95 per month, a customer could rent four DVDs at a time, receiving and returning them through the mail. There was no limit on how long a customer could keep a DVD. This was an important contrast with Blockbuster and other bricks-and-mortar video rental stores, which charged a significant late fee if a video wasn’t returned within the three-day rental window.

In 2007, the spread of high-speed home Wi-Fi led Hastings to begin offering streaming as well as DVDs. By 2010, Netflix’s main subscription plan was streaming only and the company stopped renting DVDs in 2023. Netflix also pioneered in creating its own series, beginning in 2012 with Lilyhammer, a comedy drama about mobsters. Over the next few years, Netflix typically released an entire season’s worth of episodes at the same time, thereby facilitating binge viewing. As Hulu, HBO Max, Disney+, Apple TV+, and other streaming services entered the market, most followed the Netflix model of having no paid advertising and releasing a entire season’s worth of episodes at the same time. As more streaming services became available, sales of DVDs declined sharply. Between 2005 and 2018, DVD sales declined by 86 percent.

Photo of Netflix’s headquarters in Los Gatos, California in 2018 from Wikipedia.

Over time, though, the Netflix model has run into two problems. First, originally Netflix’s streaming plan, which included no advertising, was priced at $7.99 per month. Currently, Netflix charges $19.99 per month or $26.99 per month if you want to stream programs in 4K and on multiple devices. Other streaming services were charging similar prices. There are some consumers who are unwilling to pay those fees in addition to what they may paying for cable television or for other subscription services.

Second, releasing a season’s worth of episodes at one time increased the likelihood that some consumers would sign up for a service, watch all the episodes of that series, cancel their subscription, and then resubscribe only when another series they were interested in was released.

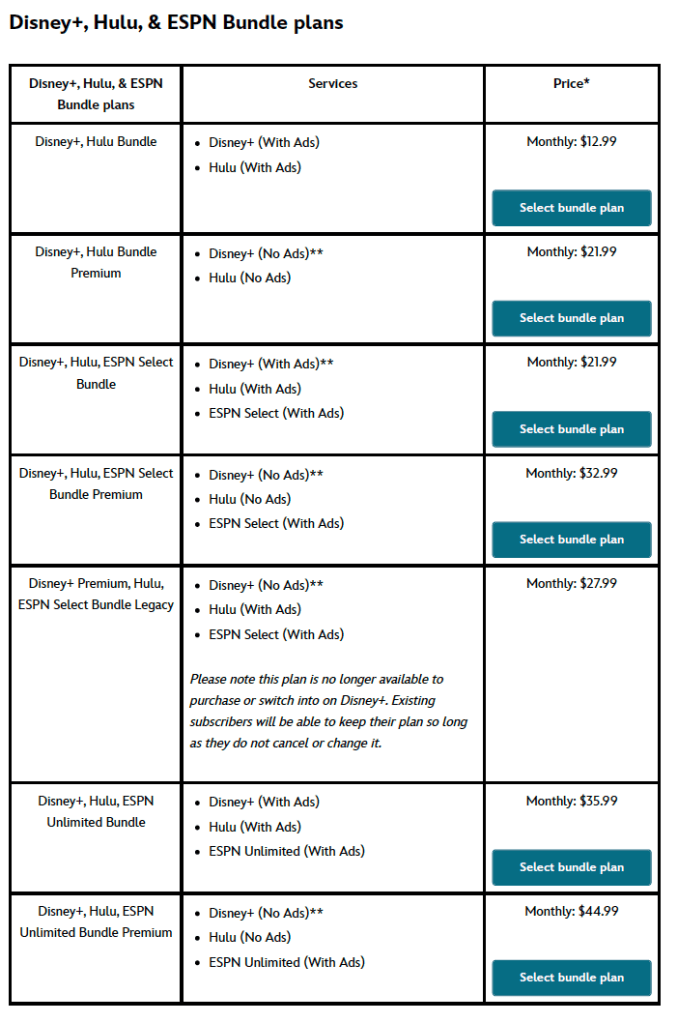
In June 2021, HBO Max was the first paid streaming service to offer an ad-supported tier at a lower subscription price. At that time, its ad-free plan had a price of $14.99 per month and its plan with ads had a price of $9.99 per month. In 2022, Netflix and Disney+ also began offering lower-priced plans with ads. Today, all the major streaming services other than Apple TV offer lower-priced plans with ads. Most streaming services now have a variety of plans. Because Disney also owns Hulu and ESPN, as the following chart shows, it may have the largest number of plans.
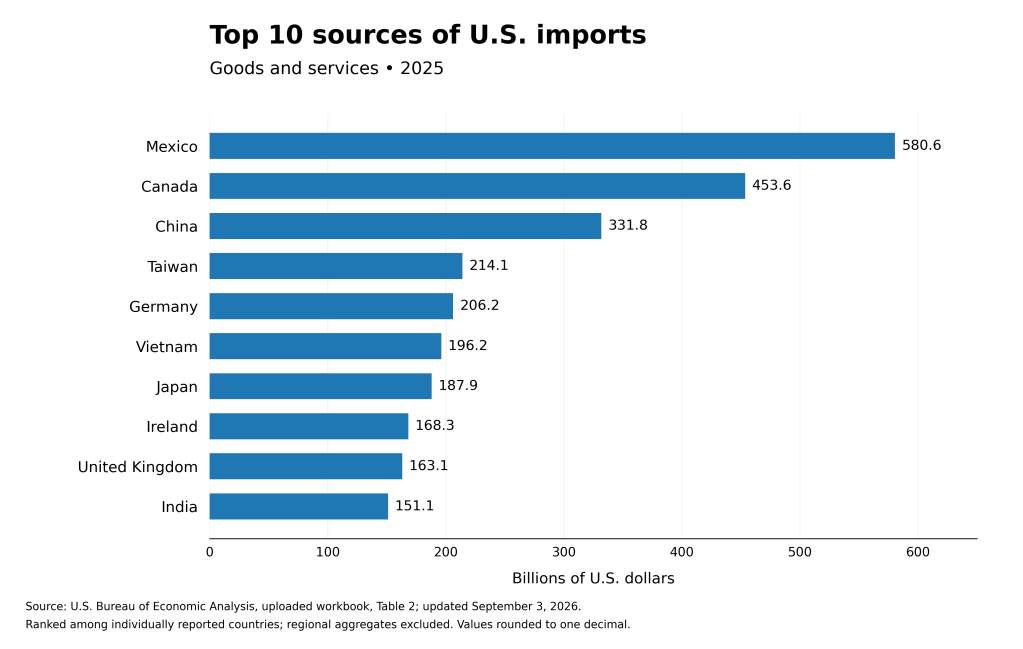
Table from disney+.com

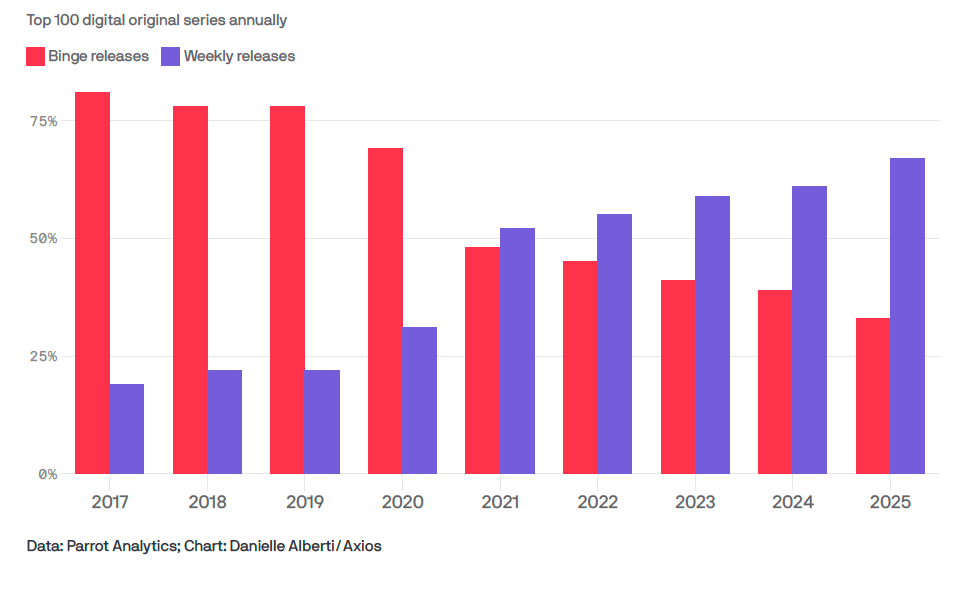
Streaming services have also moved away from releasing all of a season’s episodes at once—binge releases—in favor of releasing one episode per week. The following chart from an article on axios.com shows a dramatic shift towards weekly releases and away from binge releases. In addition to reducing the number of people who subscribe for only a month, some industry analysts argue that weekly releases enhance the social aspect to watching streaming series. Many people like to talk with friends and family or online about a new series. Those interactions are improved if everyone involved has seen the same number of episodes rather than some people having binged the series while others are watching episodes over a longer period of time.

Graph from axios.com

Note that as firms offering video streaming have begun offering plans that include advertising and as they have moved away from binge releasing episodes, they have moved much closer to the approach that television networks have used since the early days of broadcast television. This development may be unsurprising because watching programing the traditional way remains popular with many consumers. According to data from the Nielsen company, broadcast television and cable television currently have about a 36 percent share of viewers and produce more than 60 percent of all new programs.

The evolution of the market for video steaming illustrates several points that we discuss in the text.

  1. As an industry evolves, firms learn more about their customers. As we saw in Microeconomics, Chapter 6, Tesla and other sellers of electric vehicles (EVs) were initially uncertain about how price elastic the demand for EVs is. In a similar way, streaming firms have discovered that they could reduce the number of series they binge release, thereby reducing the number of people who subscribe only for one or two months, without losing significant numbers of long-term subscribers.
  2. As we saw in Microeconomics, Chapter 15, firms attempt to price discriminate by segmenting the market for their products in order to charge higher prices to consumers who have a lower price elasticity of demand. The multiple plans that streaming firms offer are a type of price discrimination.
  3. As we saw in Microeconomics, Chapters 13 and 14, to succeed, firms have to differentiate their products from those sold by competing firms. Netflix pioneered in streaming video and had an initial advantage over competitors by having a large base of consumers who were already familiar with the firm from using their DVD rental service. But over time multiple competitors have entered the market for streaming video, which has slowed Netflix’s growth. The company responded by expanding its offerings beyond movies and series to include video games, live sports, and podcasts. But recently, Ted Sarandos, the firm’s co-CEO, announced layoffs to reduce costs and replaced the executive responsible for streaming content. According to an article in the Wall Street Journal, Sarandos has “emphasized that the streaming giant is mainly focused on its ‘core’ offerings—TV shows and movies—to grow its business.”

Glenn Signs Letter to Congress Backing Legislation on Permitting Reform

Image created by ChatGPT

As we discuss, in Macroeconomics, Chapter 16 (Economics, Chapter 26), fiscal policy actions that increase aggregate supply will both expand output and reduce upward pressure on the price level. A key problem that faces attempts to expand infrastructure, particularly by increasing energy production and transmission, is the difficulty of obtaining government permits and meeting government regulations. These regulatory hurdles can delay projects for years, greatly raising the cost of constructing them.

Glenn joined officials from both Democratic and Republican administrations to urge Congress to pass the Bipartisan American Affordability and Jobs Act, which is intended to lower the regulatory barriers to constructing new energy infrastructure projects.

Below are some extracts from the letter. The full text of the letter can be found here. An article in the Wall Street Journal discusses the letter and the issues involved in permitting reform.

“Critical industries across our economy—from semiconductors to critical minerals to artificial intelligence—are built in the physical world and powered by energy infrastructure that must be built as well. Unfortunately, we are not building this infrastructure fast enough to remain globally competitive.”

“While American infrastructure development—and the economic growth it enables—flounders, our competitors invest and build. China, our principal strategic competitor, has made energy infrastructure central to its industrial strategy. China has built more high-voltage transmission in the last fifteen years than the U.S. has built in all of its history. China’s abundant, affordable energy has enabled its strategic industries from critical minerals processing to automobile manufacturing.”

“Consider the Cardinal-Hickory Creek transmission line: the 102-mile project was approved by the regional grid operator as part of a larger transmission buildout in 2011 but did not become fully operational until September 2024.
Along the way, it faced years of federal review and litigation, including two federal court injunctions, even as 160 generation projects representing over 24 gigawatts were waiting for its completion.”

“These delays are especially concerning given the growth of artificial intelligence. Artificial intelligence is a transformational technology, but it must be developed in a manner beneficial for all Americans. Our current permitting structure makes that impossible. To avoid long lead times in connecting to the grid, U.S. hyperscalers [firms such as Amazon, Google, and Microsoft that are building large data centers and related infrastructure] have turned to on-site power generation solutions. By generating power ‘behind the meter,’ they can bypass strained grid infrastructure and the years-long interconnection queue.”

Image created by ChatGPT

“With a more rational permitting process, hyperscalers would invest in new energy infrastructure that could connect speedily to the grid, which, together with sound regulatory policies, would increase electricity supply for all
consumers and ultimately reduce residential bills. Alleviating our permitting
bottlenecks can help ensure that America retains its competitive edge in a critical technology while delivering benefits to the American people.”

“The Bipartisan American Affordability and Jobs Act is the most significant
bipartisan legislative effort that Congress has undertaken in decades to tackle
these challenges. It addresses key constraints stifling American industry by
requiring interregional transmission planning, strengthening the federal backstop for nationally significant transmission lines, and creating a faster, more predictable process for connecting new generation to the grid. It also makes permits more durable by imposing tighter timelines for litigation and limiting frivolous lawsuits that can halt projects indefinitely, while preserving community input and judicial review of substantive agency decisions. Among many other important reforms, the Act also requires data centers to pay for the new transmission built to serve them, as well as their fair share of existing system costs, which would reduce costs for other customers.”

Did Seattle Succeed in Raising the Monthly Pay of Gig Drivers?

Supports: Microeconomics and Economics, Chapter 16, Section 16.4.

Image created by ChatGPT

Regulations don’t always have the effect that policymakers hope they will. In 2022, the Seattle City Council unanimously passed the App-Based Worker Minimum Payment (ABWMP) ordinance, which took effect in January 2024. Most app-based (or gig) workers who deliver for DoorDash, Uber Eats, or Grubhub are independent contractors rather than employees of those companies. The ordinance was intended to raise the compensation of these workers by requiring that they receive a minimum payment for each delivery based on the time they worked and the distance they traveled. The intention was for gig workers to receive compensation similar to the minimum wage that hourly workers receive.

In December 2025, a research paper by Yuan An, Andrew Garin, and Brian Kovak of Carnegie Mellon University concluded that the ordinance was not having its intended effect. They found that for experienced (or “highly attached”) drivers, “the ordinance increased pay per delivery, but decreased the number of delivery tasks completed per month” and, as a result, there was “
no effect on total delivery earnings among highly attached workers after the first month.” The authors note that “free entry [of drivers in the gig delivery market] plays an important role” in their results and that “the equilibrium value of doing delivery work must always remain equal to the fixed, constant outside option available to all workers.”

a. What effect would we expect Seattle enacting a regulation increasing the pay per delivery for gig delivery drivers to have on the number of gig delivery drivers working in Seattle?

b. Explain the reasoning behind the authors’ statement that “the equilibrium value of doing delivery work must always remain equal to the fixed, constant outside option available to all workers.”

c. Use your answers to parts (a) and (b) to explain why the authors found that the Seattle ordinance increasing pay per delivery did not increase the monthly pay of gig delivery drivers in the city.

Solving the Problem

Step 1: Review the chapter material. This problem is about compensating differentials, so you may want to review the section “Compensating Differentials.”

Step 2: Answer part (a) by explaining what effect a regulation increasing the pay per delivery for gig delivery drivers will have on the number of gig delivery drivers working in Seattle. There is free entry into being a gig delivery driver. Anyone who has a car (although a bike, motorcycle, or scooter is also acceptable) and a good driving record can become a gig delivery driver. As a result, we would expect that a Seattle regulation increasing the pay per delivery will increase the number of gig delivery drivers by making gig delivery more attractive in comparison with other jobs.

Step 3: Answer part (b) by explaining the reasoning behind the authors’ statement that: “the equilibrium value of doing delivery work must always remain equal to the fixed, constant outside option available to all workers.” Although stated in technical terms, the authors are making the basic point that the compensation a worker receives in a job must be at least equal to the worker’s opportunity cost—the compensation the worker would receive in his or her next best available job. In this case, the next best available job might be working in a warehouse for Amazon, being a server in a restaurant, or some other job that has free entry and doesn’t require significant training. At any given time, workers in Seattle will have chosen jobs with compensation packages that fit their particular preferences, which include the wages received, as well as some of the other job characteristics—such as health insurance—that we’ve mentioned in this section. Holding the level of compensation in other occupations constant, raising pay for gig delivery drivers will make those jobs more attractive and therefore cause more workers to switch to gig delivery from other jobs. We would expect that the supply of gig delivery drivers will increase until the compensation from being one of those drivers falls back to the “fixed, constant outside options” available to drivers.

Step 4: Answer part (c) by explaining why your answers to parts (a) and (b) will lead to the authors’ conclusion that the ordinance increasing gig delivery drivers’ pay per delivery did not increase their monthly pay. We’ve seen in the first two parts of this problem that raising the pay of gig delivery drivers will increase the supply of these drivers and that the supply will continue to increase until their compensation is competed back down to the compensation they can receive from similar alternative jobs. As a consequence, drivers earn more per delivery because of the ordinance—but they make fewer deliveries because the higher pay attracts additional drivers. As An, Garin, and Kovak found, the result is drivers’ monthly pay was no higher after the Seattle City Council passed the ordinance than it was before.

Hall and Woodford Win 2026 Nobel Prize in Economics

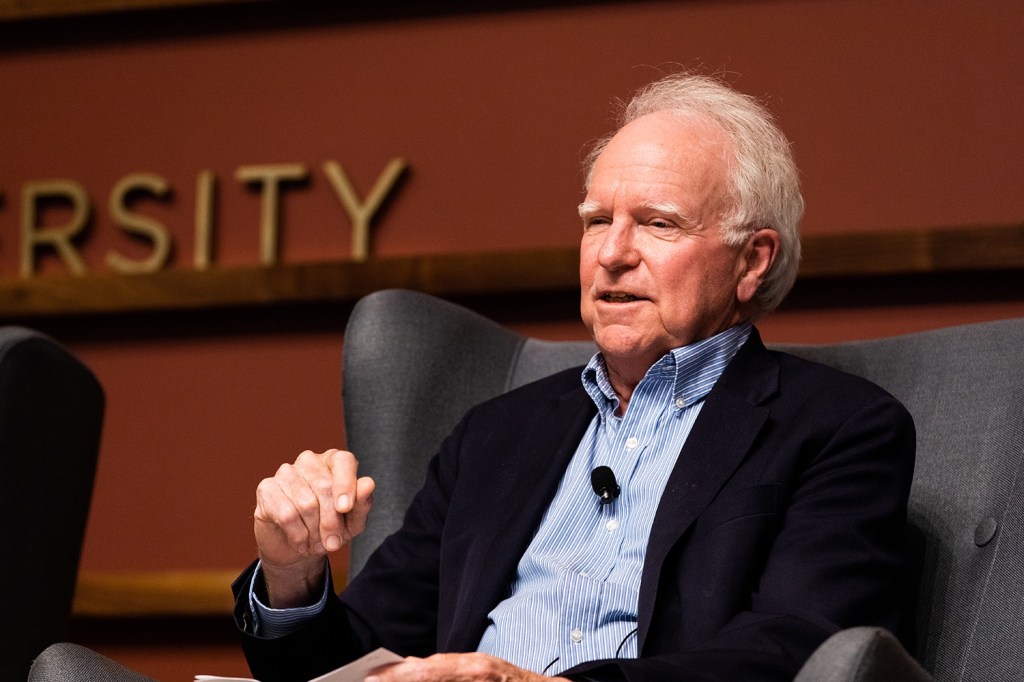
Photo of Robert Hall from news.stanford.edu

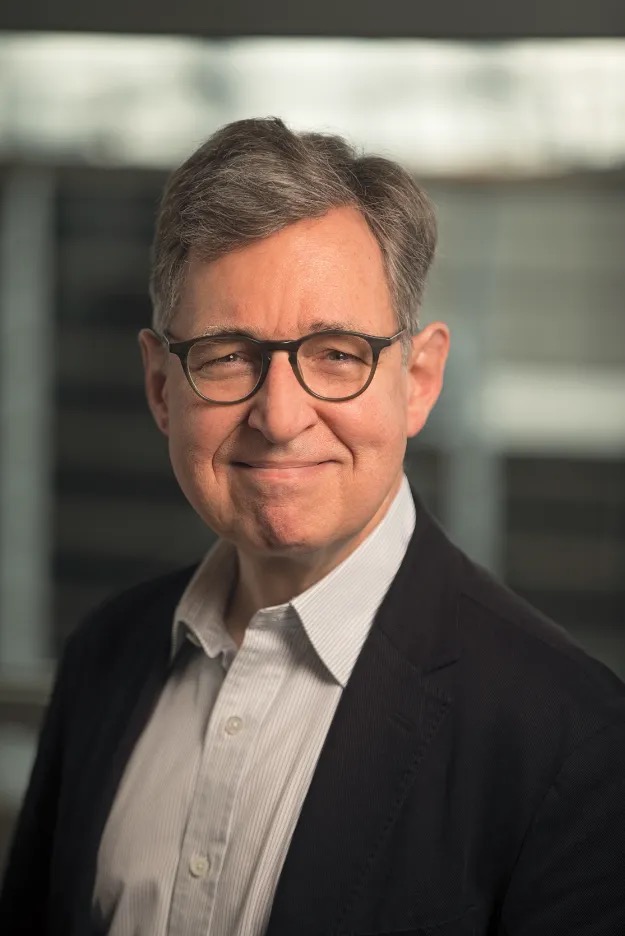
Photo of Michael Woodford from politicaleconomy.columbia.edu

Robert Hall of Stanford and Michael Woodford of Columbia have been awarded the 2026 Nobel Prize in Economics. Their careers have helped define the evolution of macroeconomics during the past 50 years.

Principles of economics is often taught as one semester of microeconomics and one semester of macroeconomics. In microeconomics we focus on analyzing the households’ decisions about which products to buy and on firms’ decisions about which products to sell and what prices to charge. In macroeconomics we switch the focus to the economy as a whole, analyzing what determines total production in the economy, as measured by GDP, and what determines the price level, as measured by the consumer price index (CPI) or the personal consumption expenditures (PCE) price index. An important part of macroeconomics is analyzing the effects of the federal government’s monetary and fiscal policies on production, employment, and prices.

Microeconomics and macroeconomics are connected because macroeconomic aggregates (like GDP, the unemployment rate, and the price level) ultimately depend on the decisions of households and firms. Similarly, the effects of fiscal and monetary policies on the economy depend on how households and firms react to the policies.

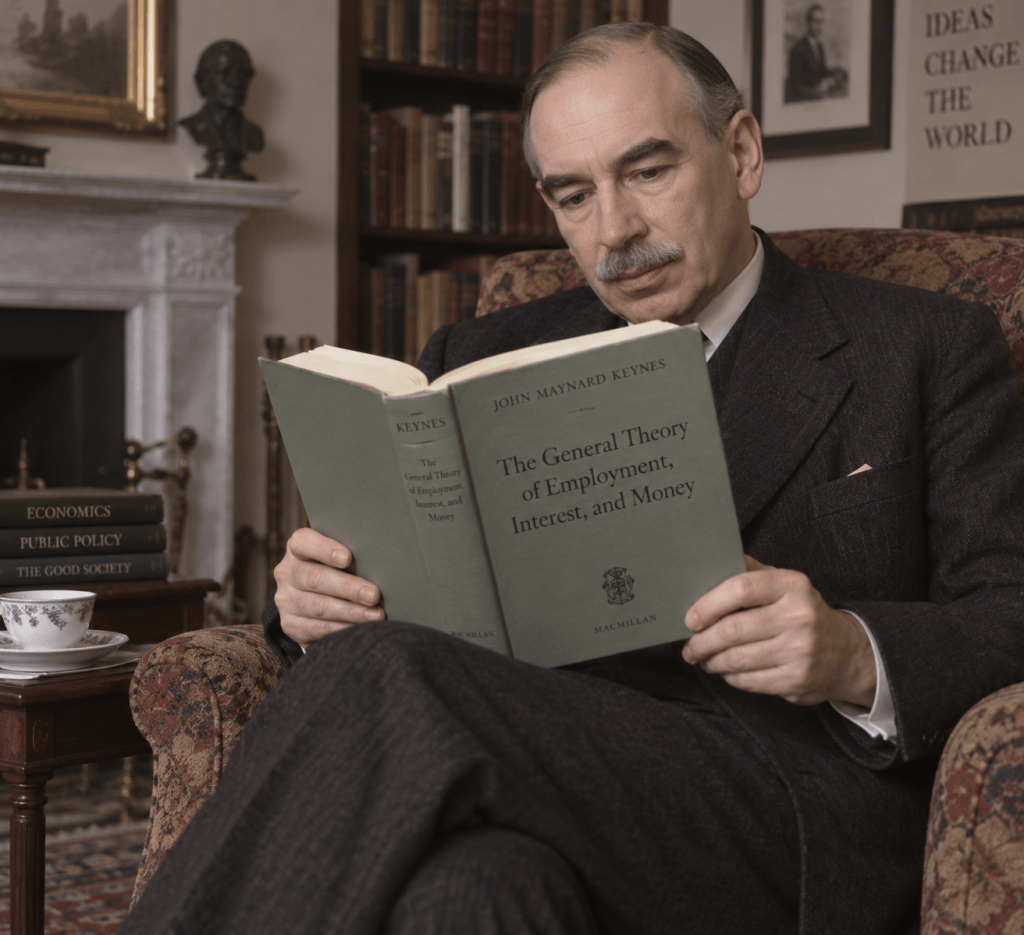
Image of John Maynard Keynes created by ChatGPT

The focus on economic aggregates in macroeconomics dates back to the publication of John Maynard Keynes’s General Theory of Employment, Interest, and Money in 1936. Keynes’s book was long and complicated, which led shorter, more straightforward, interpretations of his ideas by Nobel laureate John Hicks of Oxford and Alvin Hansen of Harvard to become widely accepted. The Hicks-Hansen interpretation was embodied in the IS-LM model, which focused on the relationships among a few macroeconomic variables. (We discuss the IS-LM model in the appendix to Chapter 18 of Money, Banking, and the Financial System.)

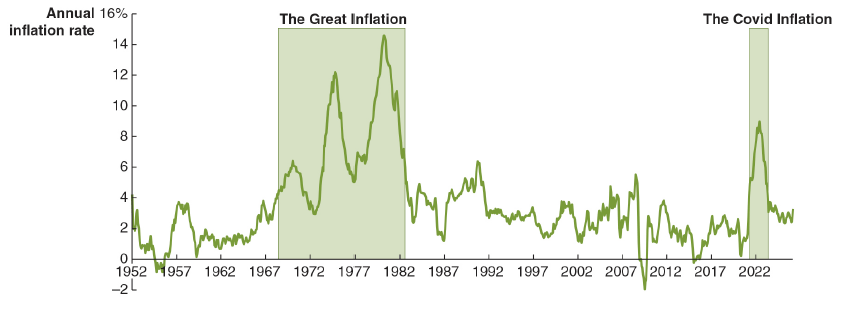
During the Great Inflation of the 1970s of the 1970s and early 1980s, many economists concluded that the basic IS-LM model was no longer a good guide to understanding events in the U.S. economy. That conclusion increased the interest in grounding macroeconomics in the basic decision making of households and firms. This approach became known as the microfoundations of macroeconomics.

This new focus on microeconomics led some economists to reject the idea that discretionary monetary and fiscal policy was able to stabilize the economy by reducing fluctuations in aggregate output and employment. This approach is called the New Classical Macroeconomics. (We discuss the New Classical Macroeconomics in the appendix to Macroeconomics, Chapter 13.) Other economists argue that discretionary policy can play a role in stabilizing the economy, which is a key argument advanced by Keynesians since the 1930s, but believe that policymakers need to take into account how households and firms react to policy. This approach is called the New Keynesian economics. The work of Hall and Woodford contributed to the development of New Keynesian economics.

Early in his career, Hall published an academic article making a major contribution to understanding the microfoundations of consumption spending. Hall’s work elaborated Milton Friedman’s permanent income hypothesis. As we discuss in Macroeconomics, Chapter 12, Section 12.2 and Chapter 16, Section 16.5, consumers are forward looking, which means their consumption decisions take into account not just their current income but also their expected future income—which Friedman called permanent income. For example, a real estate agent might have a high income in a year when she earns a commission on the sale of 15 houses and a much lower income in a year when the local housing market is weak and she earns a commission on only 2 houses. Most people like to smooth out their consumption over time, so the agent is likely to spend less of her current income in good sales years and more of her current income in the bad sales years.

Image created by ChatGPT

Hall formalized Friedman’s insight using the tools of dynamic optimization and also showed that the model fit the macroeconomic data well. One important implication of Hall’s work is that households are unlikely to significantly adjust their spending in response to temporary policy changes, such as a temporary cut in personal income taxes. Hall made a number of additional contributions to macroeconomics, including by analyzing why prices and wages don’t always respond quickly to changes in total spending. As we discuss in Macroeconomics, Chapter 10, Section 10.3, the federal government produces many statistics that make it possible to monitor the state of the economy, but the federal government does not officially decide when a recession begins or when it ends. Instead, most economists and policymakers accept the decisions of the Business Cycle Dating Committee of the National Bureau of Economic Research (NBER), a private research group located in Cambridge, Massachusetts. Hall served as chair of the committee for 46 years, from 1978 to 2024.

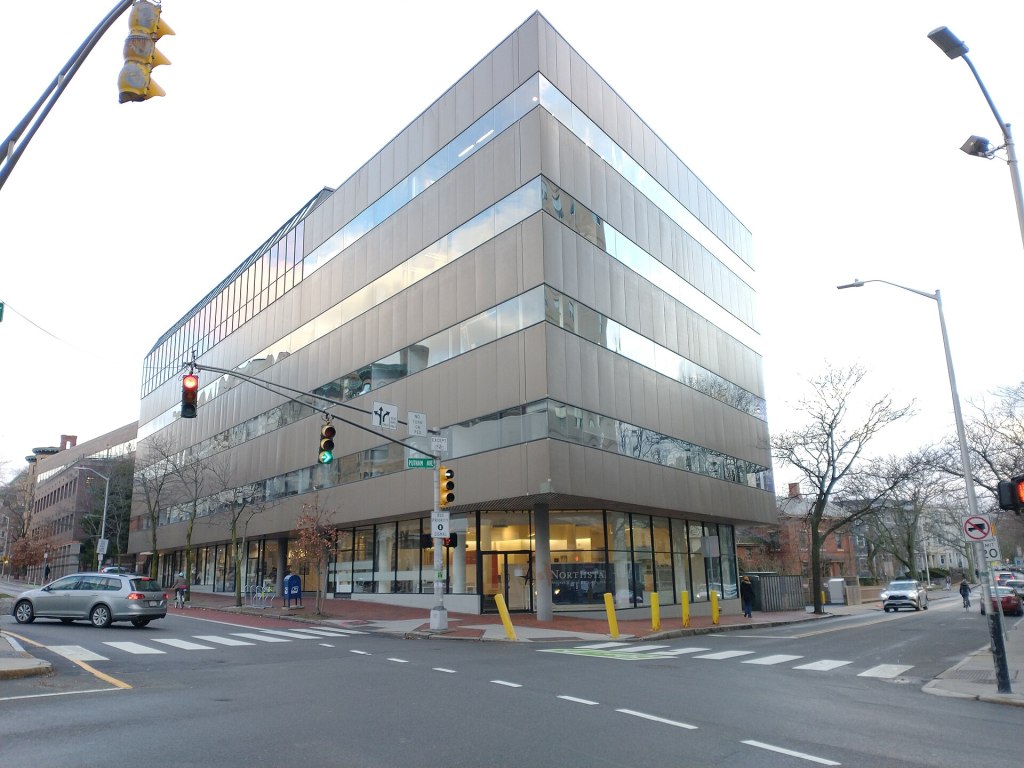
Image of the NBER building from the Wikipedia Commons

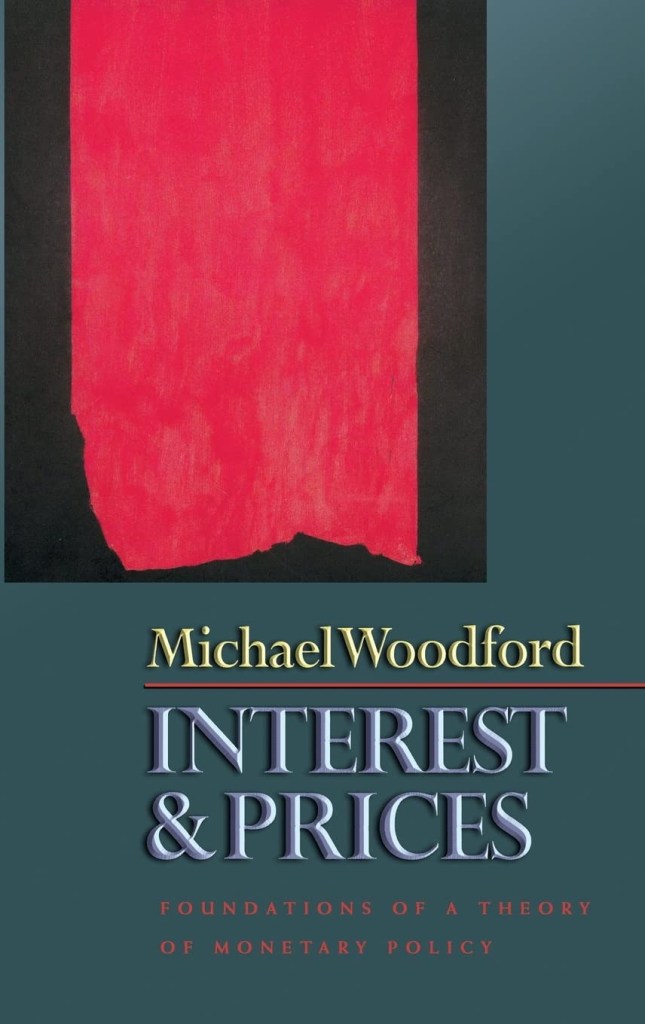
Woodford has made wide-ranging contributions to the development of New Keynesian economics. In particular, he developed a model that synthesized the contributions of a number of other economists to provide a general framework for understanding macroeconomics and for evaluating the effects of monetary policy. His 2003 book, Interest and Prices: Foundations of a Theory of Monetary Policy, has been particularly influential.

Image from amazon.com

The Nobel Committee’s announcement of the prize can be found here. A longer discussion of the Hall and Woodford’s work can be found here. The scope of their research can be seen by reviewing their curricula vitae, which can be found here and here. The amount of the prize this year is 12 million Swedish kronor (about $1.2 million).

How Good Were the Deals during Amazon’s Prime Big Deal Days?

Image created by ChatGPT

Amazon concluded its fall Prime Big Deal Days yesterday. Amazon also has a Prime Day in the summer. The company generally reports that its Prime Days result in higher sales and that the lower prices Amazon charges during these periods result in substantial savings to consumers. For example, in October 2024, Amazon announced that, “Globally, Prime members saved more than $1 billion across millions of deals, including on seasonal merchandise and gifts.”

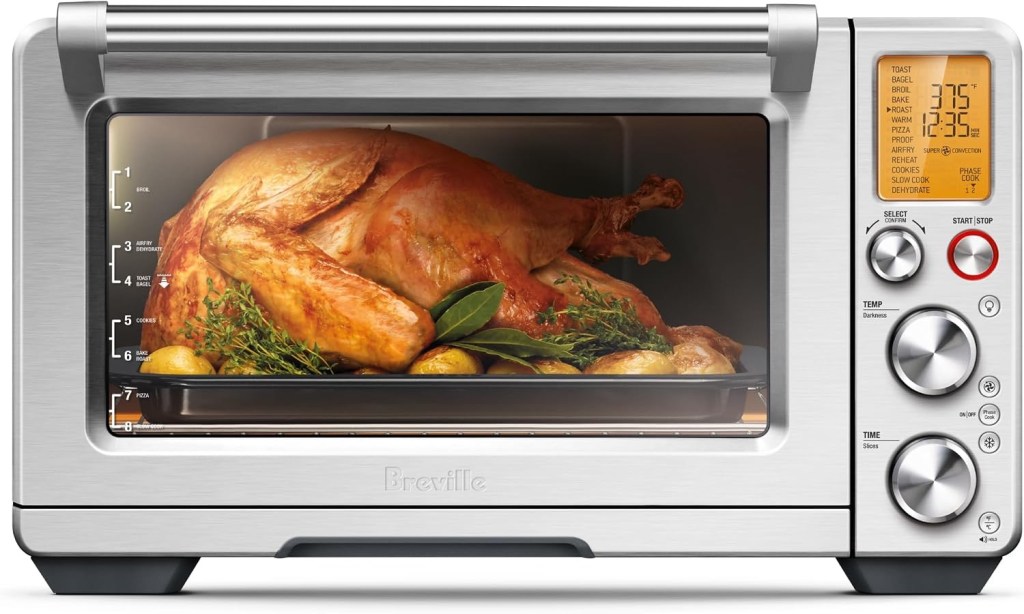
Most consumers likely expect that on Prime Days they can buy goods more cheaply on Amazon than on competing sites. That assumption isn’t always accurate, however. For example, Wirecutter is a product-review website owned by the New York Times. Yesterday, it recommended as one of several “best deals from Amazon’s Prime Big Deal Days” Breville’s Smart Oven Air Fryer Pro. Amazon was selling the oven at a price of $320, 20 percent less than its regular price of $400.

Image from amazon.com

Was that price unusually low? Not in comparison with Amazon’s competitors. Target, Best Buy, and Macy’s were also charging $320 for the same oven. Walmart was charging only $280. This price matching is unsurprising. Amazon’s Prime Days are widely publicized and Amazon’s competitors have an incentive to respond with sales of their own rather than lose business to Amazon. For instance, during Prime Days, Walmart was also advertising that on their site “Deals Are Heating Up in a Major Way.”

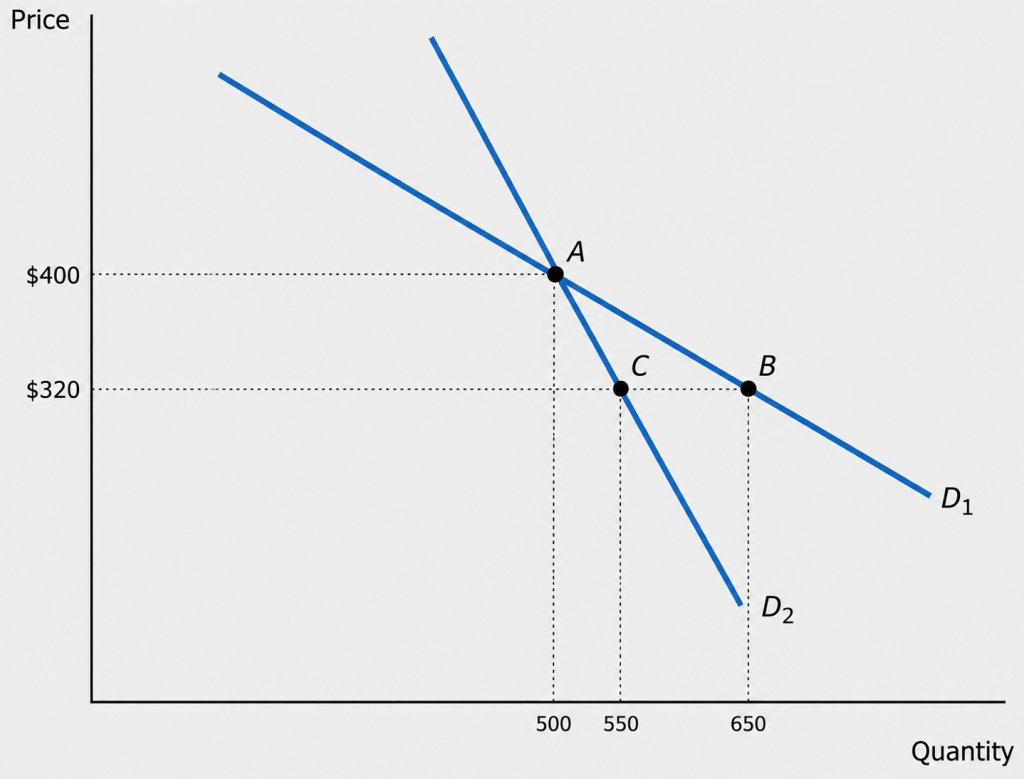
The price matching by competitors is, of course, not good news for Amazon. The following figure shows the demand for Breville ovens on amazon.com. For Amazon to experience an increase in the revenue it earns on the ovens from cutting the price by 20 percent, the quantity of ovens it sells would need to increase by more than 20 percent. Suppose that, hypothetically, Amazon would have sold 500 ovens per day at a price of $400 (point A).

If Amazon cuts the price of the ovens to $320 and its competitors keep their prices at $400, the demand curve for the ovens on amazon.com is D1, so the quantity of ovens Amazon sells increases to 650 per day (point B). In this case, Amazon’s revenue increases from $400 × 500 = $200,000 to $320 × 650 = $208,000. But if Amazon’s competitors match Amazon’s price cut—as we know that they did—then the demand curve for the ovens is D2, so the quantity of ovens Amazon sells increases only to 550 (point C). In this case, Amazon’s revenue decreases from $400 × 500 = $200,000 to $320 × 550 = $176,000.

(In Microeconomics, Chapter 6, we note that when two demand curves intersect, the flatter demand curve, D1—the one with the smaller slope in absolute value—is more price elastic than is the steeper demand curve, D2. In other words, a firm faces a more elastic demand curve when competitors match the firm’s price cuts than when they don’t.)

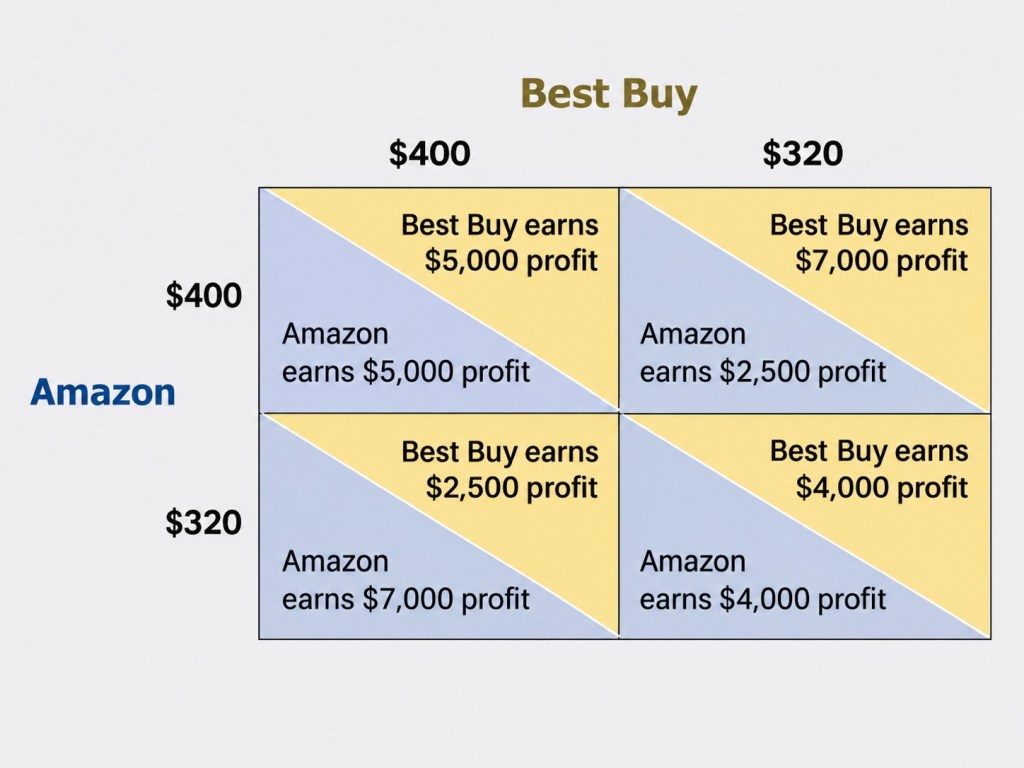
One way to think about the pricing of these ovens is that with Prime Day price cuts, Amazon pushed itself and its competitors into a prisoner’s dilemma. If we simplify the situation by including just Amazon and Best Buy, we can construct the following payoff matrix. (We discuss payoff matrices and the prisoner’s dilemma in Microeconomics, Chapter 14, Section 14.2.)

In this payoff matrix, Amazon and Best Buy are better off if they both charge $400 and earn a profit of $5,000 per day from selling the ovens (the upper left-hand quadrant). But if Amazon knows that Best Buy will charge $400, Amazon is better off gaining sales by charging $320 and earning a profit of $7,000 rather than a profit of $5,000 (the lower left-hand quadrant). If Amazon knows that Best Buy will charge $320, Amazon is better off also charging $320 and earning a profit of $4,000 rather than a profit of $2,500 (the lower right-hand quadrant).

Because the payoffs are symmetrical, we can conclude that both firms will charge $320, ending up with the smaller profit shown in the lower right-hand quadrant rather than the larger profit shown in the upper left-hand quadrant. The two firms are in a prisoner’s dilemma.

As we discuss in Chapter 14, in practice, firms can escape the prisoner’s dilemma in situations like this one because the firms are in a repeated game. In that situation, firms are better off cooperating by implicitly colluding and both charging $400. But we wouldn’t expect implicit collision here because during Prime Days, Amazon is publicly announcing that it will charge the lower price. In that case, Amazon’s competitors have an incentive to also charge a lower price, which they did. (Walmart, as we mentioned, decided to charge a price that was even below Amazon’s Prime Day price.)
So, can you get good deals during Amazon’s Prime Days? Yes, not only on their site, but on competitors’ sites as well.

Is It Fine to Bring an Iced Coffee to a Job Interview? Jadrian Wooten Provides an Economic Analysis

Image created by ChatGPT

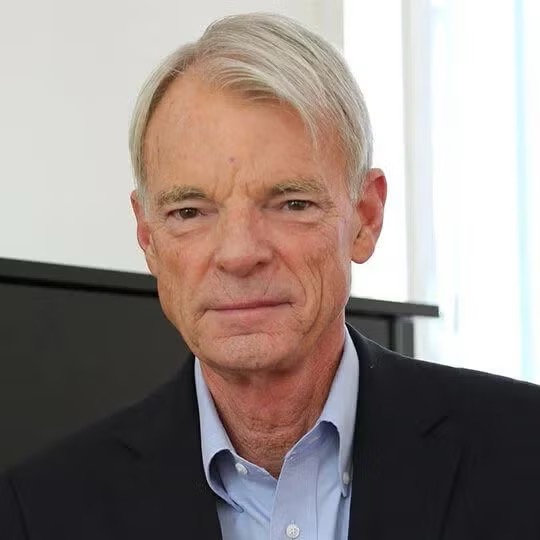
There’s a vigorous debate on social media over whether it’s acceptable for a job candidate to bring an iced coffee to an interview. In his always interesting “Monday Morning Economist” Substack, Jadrian Wooten provides an economic analysis based on the signaling theory of Nobel laureate Michael Spence of New York University and Stanford. 

Photo of Michael Spence from gsb.stanford.edu

Signaling can be important in markets affected by the problem of asymmetric information, which occurs when one party to an economic attraction has less information than the other party. As we discuss in Microeconomics, Chapter 7, George Akerlof—who was awarded the Nobel Prize in Economics in the same year as Spence—provided a classic early analysis of asymmetric information in the used car market. The seller of a used car will know whether a failure to maintain the car by, for instance, regularly changing its oil, has caused the car’s engine to suffer damage that even an auto mechanic may have difficulty detecting.

Image created by ChatGPT

Asymmetric information in a market can lead to adverse selection in which one party to a transaction—in this case, a car seller—takes advantage of knowing more than the other party—in this case, a car buyer. For example, suppose you intend to buy a car, and you contact people who have listed cars on Facebook Marketplace or Craigslist. You have no good way of determining whether a car listed has been well maintained, a “creampuff,” or poorly maintained, a “lemon.” If you had full information on the car you would offer to pay $25,000 to buy a creampuff, but only $15,000 to buy a lemon. Because of this uncertainty, you might offer to pay $20,000 for a car of unknown quality. Your offer seems reasonable to you, given your uncertainty about the quality of the car. However, a seller who knows the quality of the car will be reluctant to accept your offer if the car is a creampuff, but happy to accept your offer if the car is a lemon. The result is that cars offered for sale are more likely to be lemons than creampuffs. Or, in other words, because of asymmetric information, the market has adversely selected the cars that will be offered for sale.
Asymmetric information also exists in the job market. When you apply for a job, you know much more about how hard you will work and how developed your relevant skills are than does the company you are applying to. Suppose that the company would pay you a salary of $60,000 per year if the company was sure that you would turn out to be a hard worker, but only $40,000 if the company believed that you would turn out be a slacker. Because of this uncertainty, the company might offer a starting salary of $50,000. That salary would be attractive to slackers but unattractive to hard workers. As a result, the company might find that most of the people applying to work for them are slackers.
Michael Spence argues that in markets in which asymmetric information is important, economic agents will have an incentive to signal that the good or service they are selling is of higher quality than buyers might otherwise think. For example, a firm selling used cars may invest in making their dealership clean and attractive or by offering warranties on the cars they sell. The firms are attempting to signal buyers that the cars they are selling are creampuffs rather than lemons.

One strong signal you can send to employers when you apply for jobs is that you have earned a college degree. There has been a long debate among economists over whether a college degree indicates to potential employers that you have accumulated knowledge and skills in college—in other words, your human capital is higher than for non-college graduates—or whether a college degree is mainly a signal to potential employers that you are likely to be a hard worker because you have completed a task as difficult as obtaining a college degree.

Image created by ChatGPT

The sheepskin effect is often raised by economists arguing that for potential employers your having college degree is more about signaling than about the human capital you have accumulated in college. If you complete three years of college but drop out in your fourth year before earning your degree, you have likely learned almost as much, and have nearly the same level of human capital, as someone who has taken the few additional classes needed to earn a degree. In the job market, though, you are likely to earn significantly less than someone who has a college degree. This result makes it seem that a college degree is primarily a signal to employers that you have the characteristics of a good employee. Note: The sheepskin effect gets its name from the fact that years ago college diplomas were often printed on material derived from animal skins.

This older blog post by Noah Smith, including the responses from Bryan Kaplan of George Mason University, covers the main points raised in the debate over whether the value of a college degree is mainly the signal it sends to potential employers.

So, what signal are you sending when you bring an iced coffee to a job interview? Jadrian Wooten’s Substack post explains.

Canadian Prime Minster Mark Carney, Meet Canadian Prime Minister R. B. Bennett

Image created by ChatGPT

The United States and Canada have a long history of friendly relations and, famously, share the longest undefended border in the world. Trade in goods and services has also linked the two countries with substantial economic benefits to both. By and large, trade flows reflect each country’s comparative advantage in producing goods and services. (We discuss the important role of comparative advantage in international trade in Microeconomics, Chapter 9 (Economics, Chapter 9 and Macroeconomics, Chapter 7).)

Image created by ChatGPT

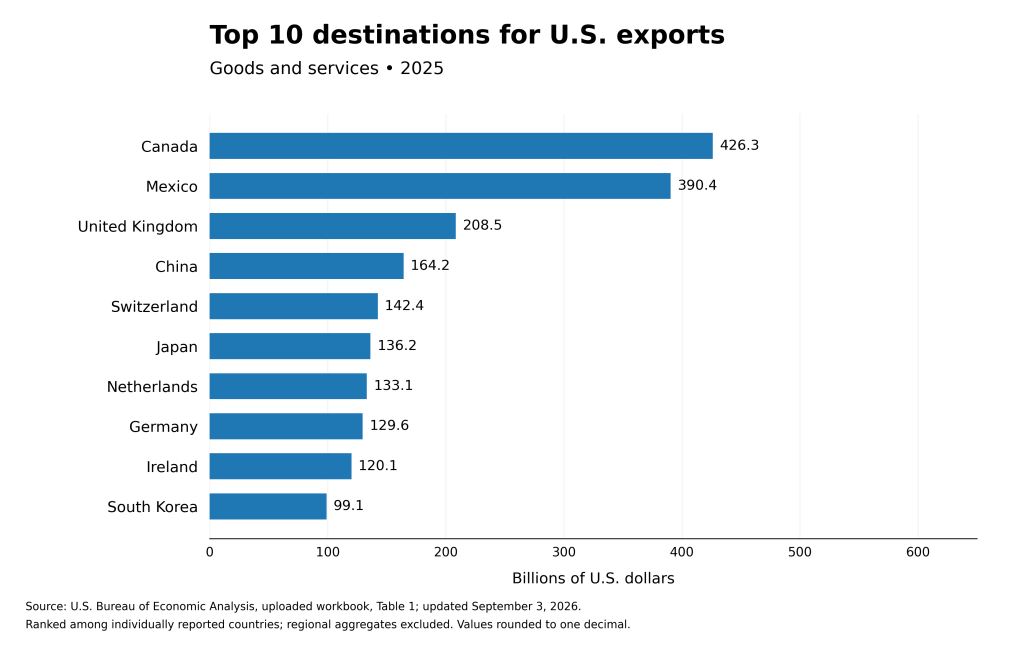
The following figures show that in 2025, Canada was the leading market for U.S. exports and the second leading source of U.S. imports, behind only Mexico.

The two figures were prepared by ChatGPT using data from the U.S. Bureau of Economic Analysis.

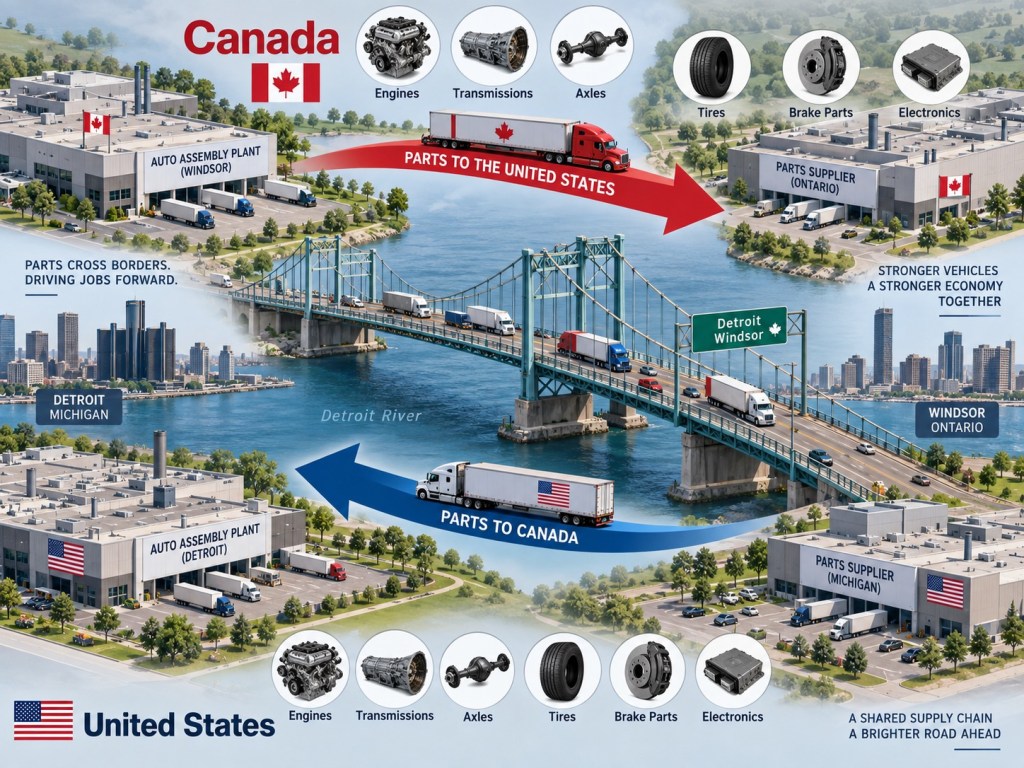
Beyond trade in final goods and services, a number of U.S. and Canadian firms rely on capital goods and intermediate goods produced in the other country. For instance, in 2025, U.S. automobile manufacturers imported auto parts worth $19.5 billion from Canada. In other words, the supply chains of these firms rely on Canadian-produced parts.

Image created by ChatGPT

Economic relations between the United States and Canada have not always been smooth, however. In particular, the substantial increases in U.S. tariff rates in 1930 and during the second Trump administration resulted in sharp reactions from the Canadian government.

In 1930, Congress passed and President Herbert Hoover signed into law the Smoot-Hawley Tariff. In retaliation, Canadian Prime Minister William Lyon Mackenzie King and the Liberal Party significantly raised tariffs on U.S. imports. (We discussed the Smoot-Hawley Tariff in this blog post last year.) In the July 1930 Canadian elections, as the effects of the Great Depression began to be felt, Richard Bedford Bennett, the leader of the Conservative Party campaigned on using tariff increases to increase production and reduce unemployment. In a campaign speech, Bennett argued, “You have
been taught to mock at tariffs and applaud free trade. Tell me, when did free
trade fight for you? You say our tariffs are only for the manufacturers; I will
make them fight for you as well. I will use them to blast a way into the markets
that have been closed to you.”

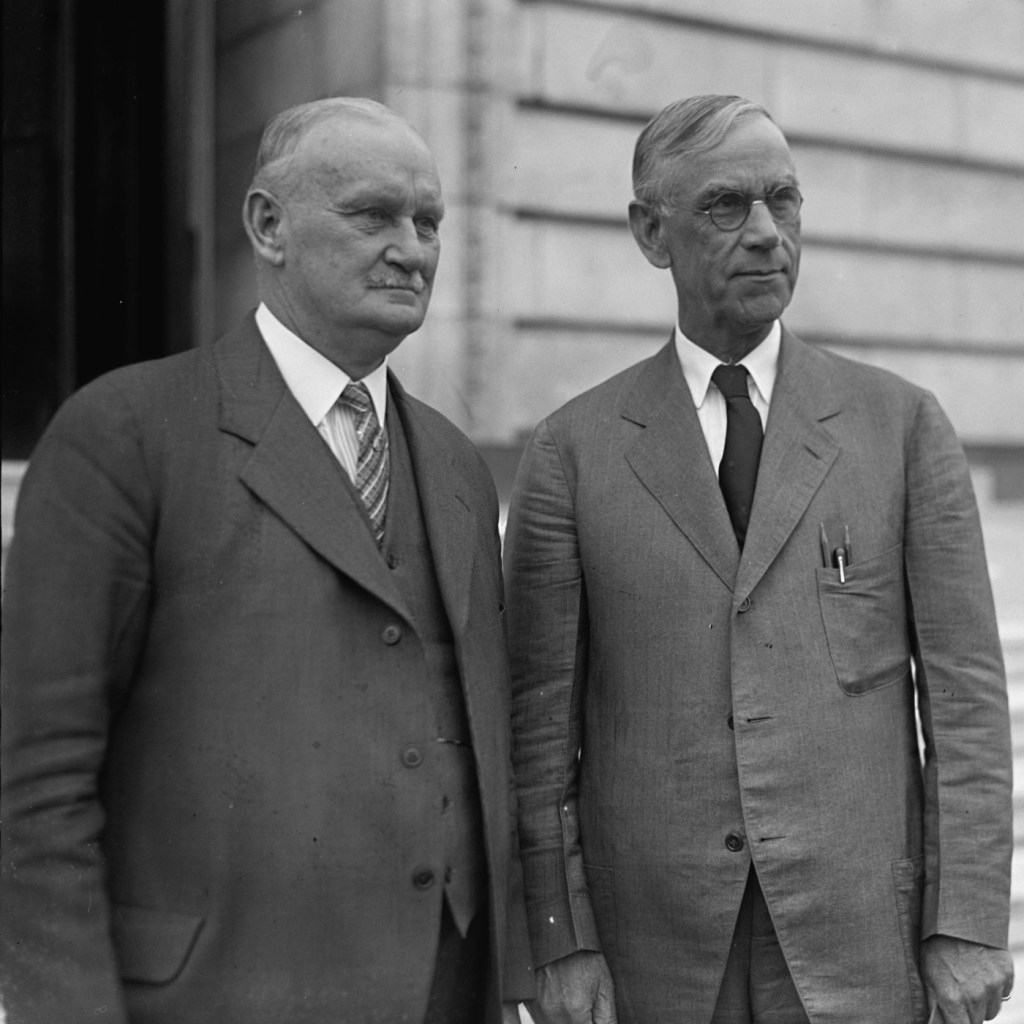
Photo of Congressman Willis Hawley of Oregon and Senator Reed Smoot from the U.S. Library of Congress via the Wall Street Journal.

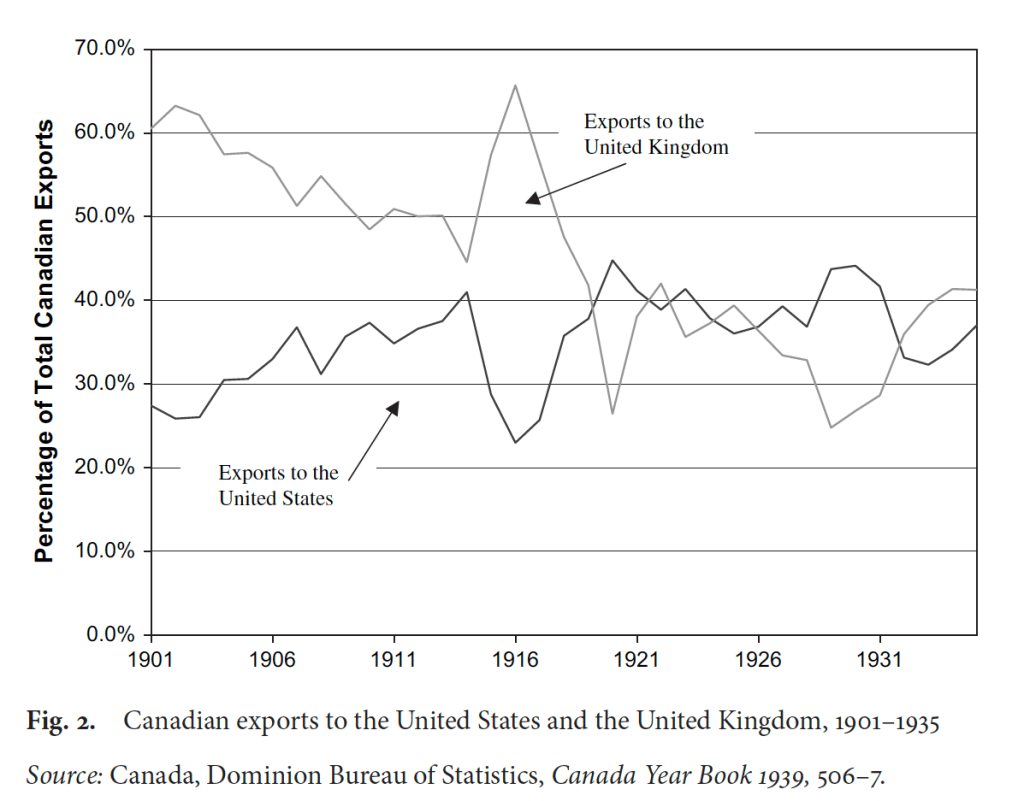
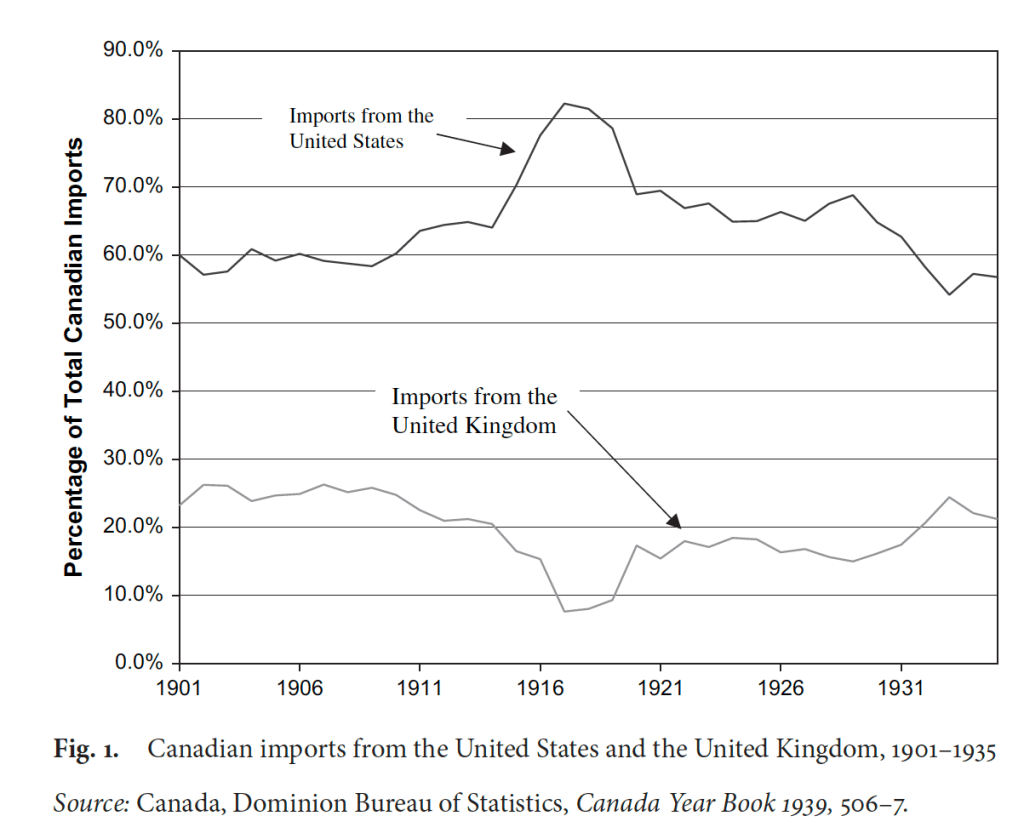
The Conservatives won an overwhelming victory in the 1930 election, and the Canadian Parliament passed legislation that raised Canadian tariff rates on U.S. imports to the highest levels in history. Bennett hoped that Canada could replace the decline in exports to the United States with an increase in exports to the United Kingdom. The following two figures, from an academic paper Tony published with his Lehigh colleague Judith MacDonald, indicate the unlikelihood of Bennett’s plan succeeding. For most of the twentieth century up to 1930 (with the exception of the World War I period), the share of Canadian exports that went to the United Kingdom had been declining, while the share that went to the United States had been increasing. In addition, in 1930, more than 60 percent of Canadian imports came from the United States as opposed to less than 20 percent coming from the United Kingdom.

For reasons of geography and the long-established trading relations between U.S. and Canadian firms, a major reorienting of Canada’s trade away from the United States and toward the United Kingdom wasn’t feasible. By 1935, near the end of his five-term, Bennett pivoted to attempting to negotiate a reciprocal trade agreement with the United States that would result in both countries reducing their tariffs on each other’s products. An agreement was reached in November 1935, but that was too late for Bennett who had been voted out of office in July.

The higher tariffs that the Trump administration has imposed on Canadian imports has placed Canadian Prime Minister Mark Carney in a situation similar to that Bennett faced in 1930. Like Bennett, Carney has responded to the higher tariffs by increasing tariffs on imports from the United States. And like Bennett, Carney has tried to find new markets outside of the United States for Canadian exports. According to an article in the Wall Street Journal:

“Carney has instructed his special envoy to Europe to scope out the most ambitious possibilities short of full membership in the [European Union] or its common market, according to people familiar with the matter. The details are still being sketched by technical working groups for what the prime minister has told his aides will be the reorienting of an economy and a society that for half a century has been dominated by the U.S.”

ChatGPT generated this image of the European Parliament building in Brussels, Belgium.

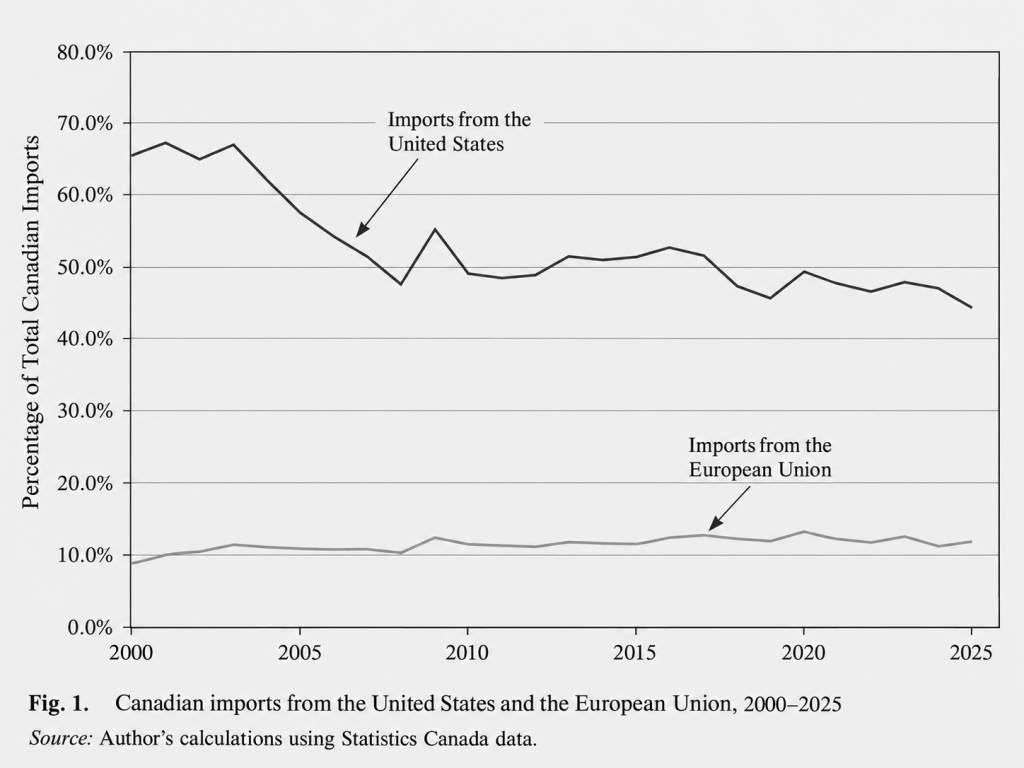
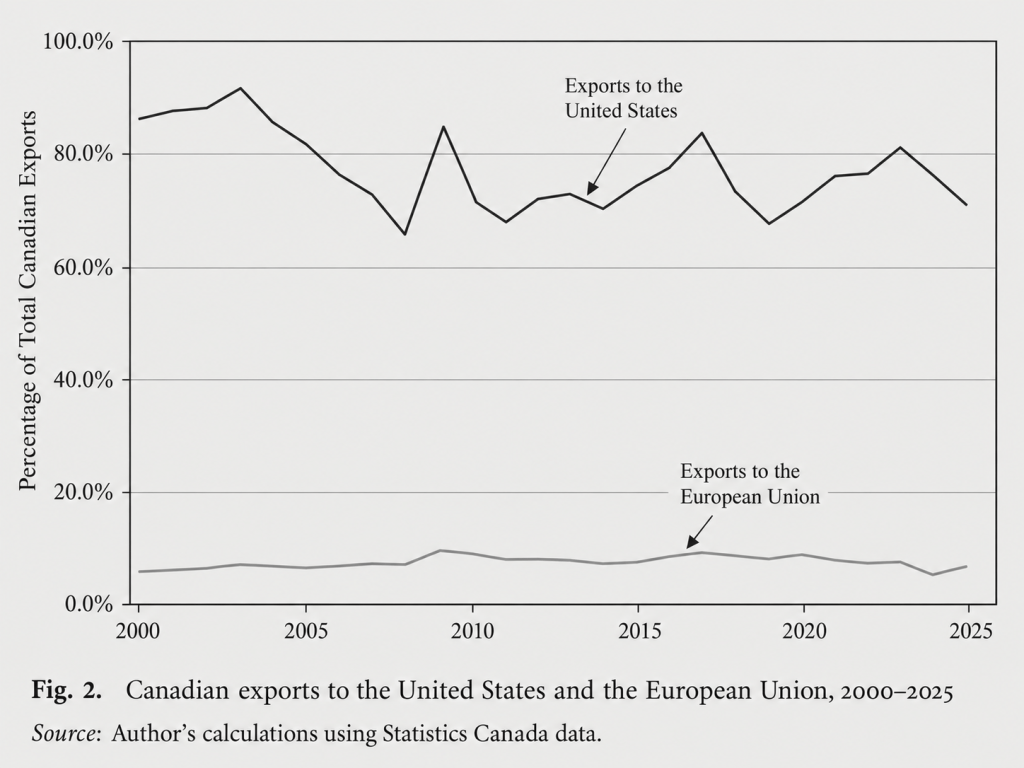
Carney’s plan of shifting Canadian exports from the United States to the European Union (EU) faces obstacles similar to those faced by Bennett as he attempted to substitute markets in the United Kingdom for markets in the United States. As the following figures show, in 2025, more than 70 percent of Canadian exports of goods went to the United States, while less than 6 percent went to the EU. Similarly, about 45 percent of the Canadian imports of goods were from the United States, while less than 12 percent were from the EU.

It may well be that Carney’s negotiations with officials in the EU are an attempt to push the United States into agreeing to reduce tariffs on Canadian imports. As a practical matter, though, it seems unlikely that Canada can reorient its trading relationships from the United Sates to the EU to any significant degree.

No Sign of Cooling Inflation in September CPI Report

Image created by ChatGPT

Today’s report from the Bureau of Labor Statistics (BLS) on the consumer price index (CPI) for August was eagerly awaited by economists and policy analysts. As we discuss in Macroeconomics, Chapter 15 (Economics, Chapter 25), monetary policy affects the economy with, in the words of Nobel Laureate Milton Friedman, “long and variable lags.” As a result, most economists agree that the Federal Reserve should not attempt to “fine tune” the economy by responding to each government release of macroeconomic data.

There are some instances, however, including the present, when the Fed’s policymaking Federal Open Market Committee (FOMC) appears to be uncertain as to whether a change in policy is needed. As a result, there was a widespread expectation that if today’s report indicated that inflation is slowing, the FOMC would likely leave its target for the federal funds rate unchanged at its meeting on Tuesday and Wednesday of next week. But if the report didn’t indicate that inflation is slowing, the committee would likely raise its target. The report gave few indications that inflation is slowing.

The following figure compares headline CPI inflation (the blue line) and core CPI inflation (the red line).

  • The headline inflation rate, which is measured by the percentage change in the CPI from the same month in the previous year, was 3.4 percent in August, the same as in July. 
  • The core inflation rate, which excludes the prices of food and energy, was 2.4 percent in August, down from 2.5 in July.  

Headline inflation was slightly higher, and core inflation was equal, to the forecasts of economists surveyed by FactSet. (Note that because of last year’s federal government shutdown, inflation data for October 2025 are not available.)

In the following figure, we look at the 1-month inflation rate for headline and core inflation—that is the annual inflation rate calculated by compounding the current month’s rate over an entire year. Calculated as the 1-month inflation rate, headline (the blue line) was 4.6 percent In August, up from 0.9 percent in July. Core inflation (the red line) was 3.5 percent in August, up from 2.6 percent in July.

The following figure illustrates the role played by energy prices in contributing to the large swings in the monthly inflation rate since the conflict in Iran began at the end of February. The red line shows the 1-month inflation rate in all energy prices included in the CPI. Inflation in energy prices, which had declined at an annual rate of 16.4 percent in July, increased at an annual rate of 28.3 percent in August. The blue line shows the 1-month inflation rate in gasoline prices, which had declined at an annual rate of 29.4 percent in July, increased at an annual rate of 58.3 percent in August.

There had been a fear that the rise in energy prices that began in March would pass through to increases in food prices, which are a key concern for many consumers. The following figure shows 1-month inflation in the CPI category “food at home” (the blue bar)—primarily food purchased at grocery stores—and in the category “food away from home” (the red bar)—primarily food purchased at restaurants. Grocery prices, which had declined at annual rate of 0.9 percent in July, increased at an annual rate of 0.4 percent in August. Food prices away from home increased 3.1 percent in August, down from 3.9 percent in July. To this point, increases in energy prices seem to have had some effect on grocery prices and restaurant prices, although the extent of the effect is unclear.

Fed Chair Kevin Warsh has indicated that he favors measures of the inflation rate that exclude particularly small or particularly large changes in the prices of some goods or services—so-called outliers. Median CPI, which is compiled monthly by economists at the Federal Reserve Bank of Cleveland, is calculated by ranking the price changes of every good or service in the index from the largest price change to the smallest price change, and then choosing the price change in the middle. The idea is to eliminate the effect on measured inflation of any short-lived events that cause the prices of some goods and services to be particularly high or particularly low. Economists at the Cleveland Fed have conducted research that shows that, in their words, “the median CPI provides a better signal of the underlying inflation trend than either the all-items CPI or the CPI excluding food and energy. The median CPI is even better at forecasting [personal consumption expenditures] PCE inflation in the near and longer term than the core PCE price index.”

Trimmed-mean inflation, also compiled by economists at the Cleveland Fed, excludes the highest 8 percent of price changes and the lowest 8 percent. The following figure shows 1-month trimmed mean (the blue line) and median (the red line) CPI inflation. Trimmed-mean inflation was 2.7 percent in August, unchanged from July. Median inflation was 2.1 percent in August, down from 3.1 percent in July. So these measures of inflation are both lower than the conventional headline and core CPI inflation measures, although as the figure shows, both measures are volatile.

Note that the Fed uses the 12-month change in the personal consumption expenditures (PCE) price index, not the change in the CPI, when gauging whether it is hitting its 2 percent annual inflation target. Historically, PCE inflation has been about 0.4 percentage points to 0.5 percentage points lower than CPI inflation. The Bureau of Economic Analysis (BEA) won’t release its estimate of August PCE inflation until September 30, after the next FOMC meeting.

Today’s report showing that inflation remains persistently above the Fed’s 2 percent annual target, following last week’s jobs report showing an unexpectedly large increase in employment, has likely raised the chance that Federal Reserve policymakers will increase their target range for the federal funds rate from the current 3.50 percent to 3.75 percent by o.25 percentage points (or 25 basis points) at the next meeting of the FOMC on September 15–16. Trading in the federal funds futures market this afternoon indicates that investors assign a 86.5 percent probability to the FOMC raising its target range at that meeting, which is up from a 72.4 probability yesterday. Trading indicated that investors assign a 74.5 percent probability to the committee increasing its target range by at least 50 basis points by the end of the year, up from 64.6 percent yesterday and from 44.7 percent one week ago.