Image created by ChatGPT
This morning (October 29), the Bureau of Economic Analysis (BEA) released two reports that show economic growth increased in the third quarter of 2026 compared with the second quarter and that inflation in September as measured by the percentage increase in personal consumption expenditures (PCE) price index also increased.
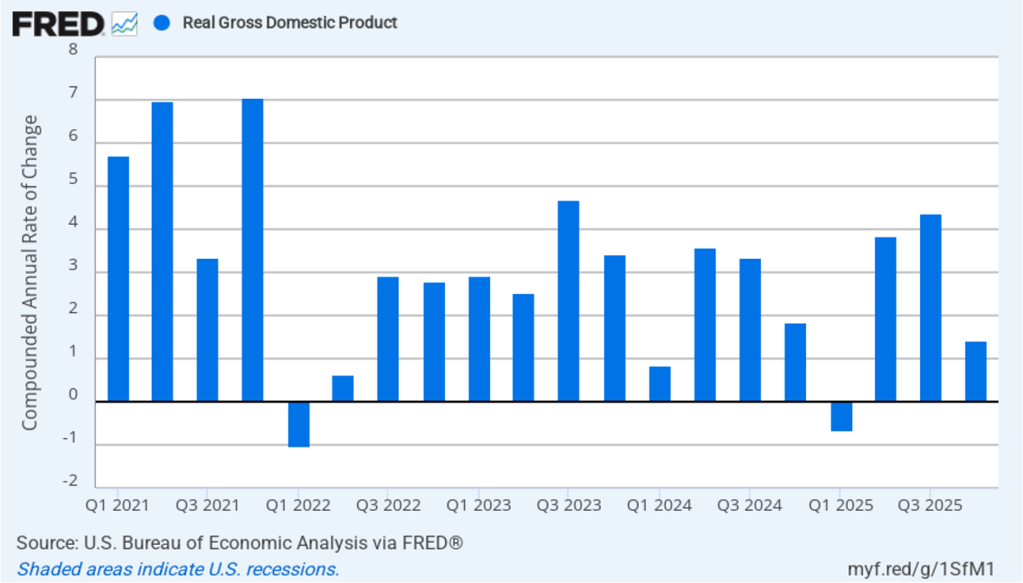
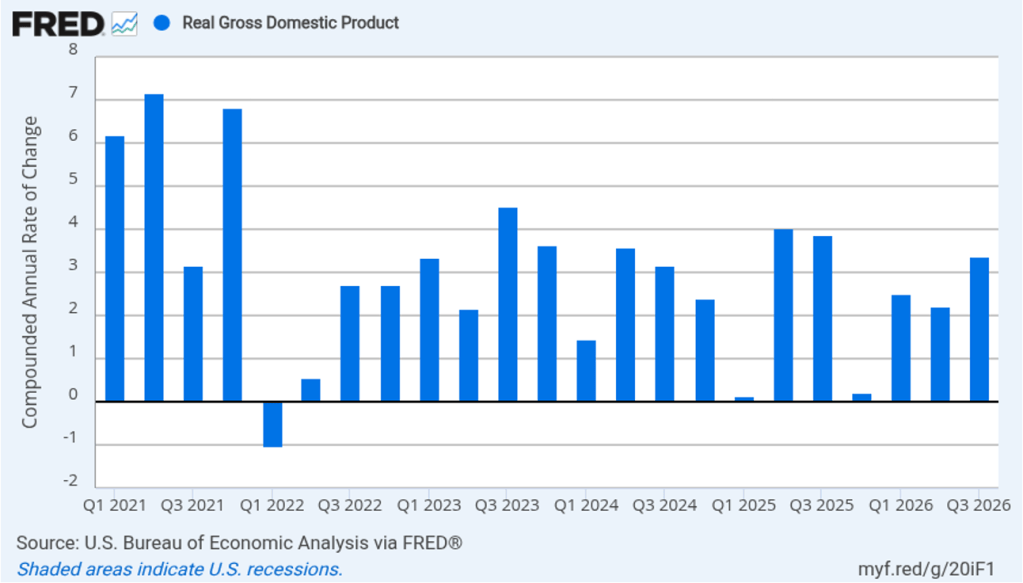
The BEA estimates that real GDP increased at an annual rate of 3.4 percent in the third quarter (July, August and September) of 2026, which is an increase from a 2.2 percent annual growth rate in the second quarter. As the following figure shows, real GDP grew at the fastest rate since the third quarter of 2025. Economists surveyed by the Wall Street Journal had expected real GDP to grow at a slower 3.1 percent rate in the third quarter.
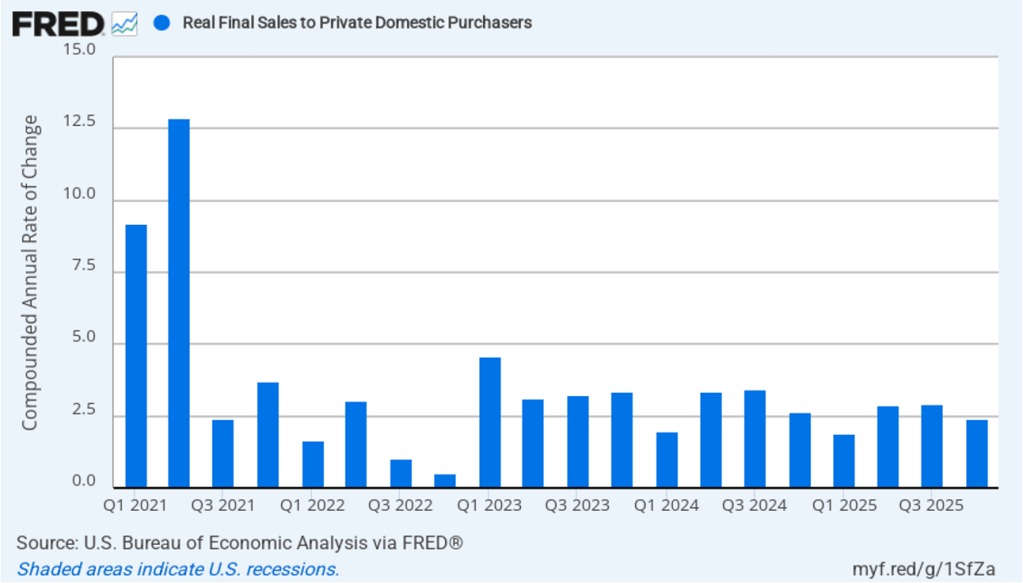
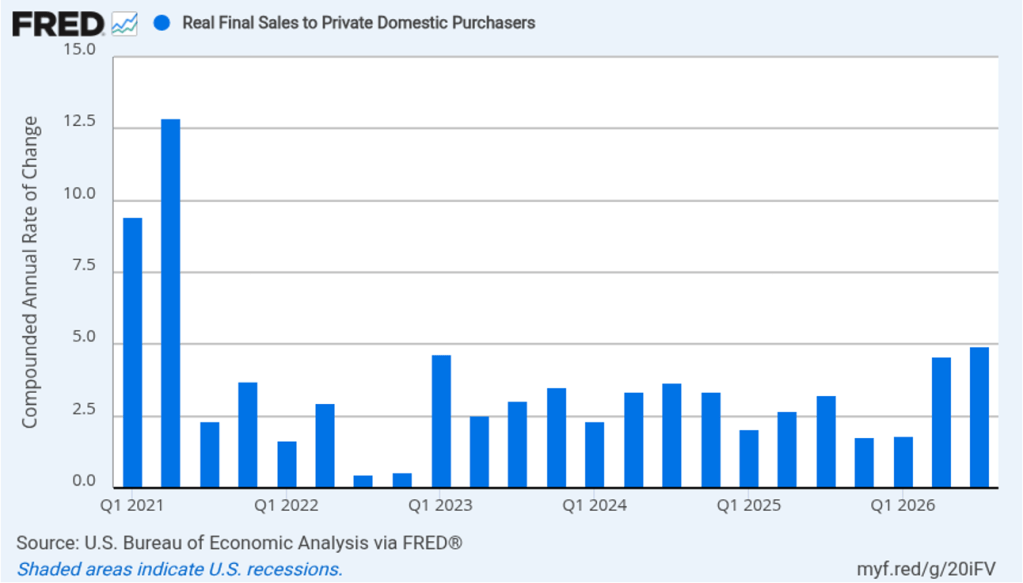
As we’ve discussed in previous blog posts, to better gauge the state of the economy, Federal Reserve policymakers often prefer to strip out the effects of imports, inventory investment, and government expenditures—which can be volatile—by looking at real final sales to private domestic purchasers, which includes only spending by U.S. households and firms on domestic production. As the following figure shows, real final sales to domestic purchasers increased at an annual rate of 4.9 percent in the third quarter, up from 4.6 percent in the second quarter. The growth rate in real final sales to domestic purchasers was well above the growth rate of real GDP, as well as more than twice the U.S. economy’s expected long-run annual real growth rate of 1.8 percent. So estimated growth in real final sales to domestic purchasers indicates that the U.S. economy is expanding more rapidly than is indicated by estimated growth in real GDP. Typically, growth in real final sales to domestic purchasers is steadier than growth in real GDP and is likely a better indicator of the underlying growth rate in the economy.
Today’s BEA “Personal Income and Outlays” report included monthly data on the personal consumption expenditures (PCE) price index. The Fed relies on annual changes in the PCE price index to evaluate whether it’s meeting its 2 percent annual inflation target. As we noted in an earlier blog post, Fed Chair Kevin Warsh indicated in his press conference following the July meeting of the Federal Open Market Committee (FOMC) that the committee intended to continue using the PCE price index as its gauge of inflation, although that decision would be revisited early next year. Some analysts have interpreted Warsh’s statement as an indication that he favored moving to a measure that would show lower rates of inflation than those shown by the PCE.
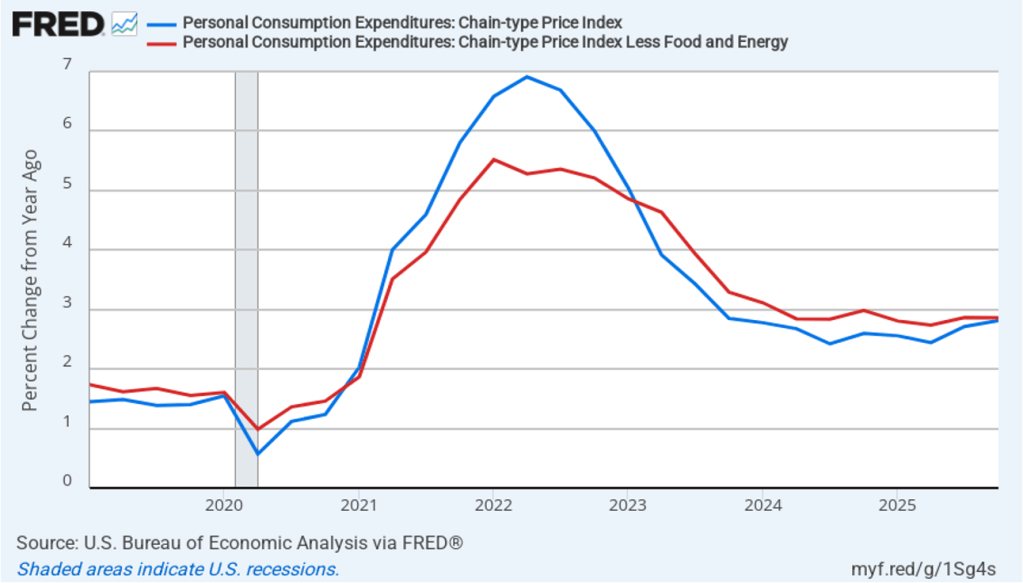
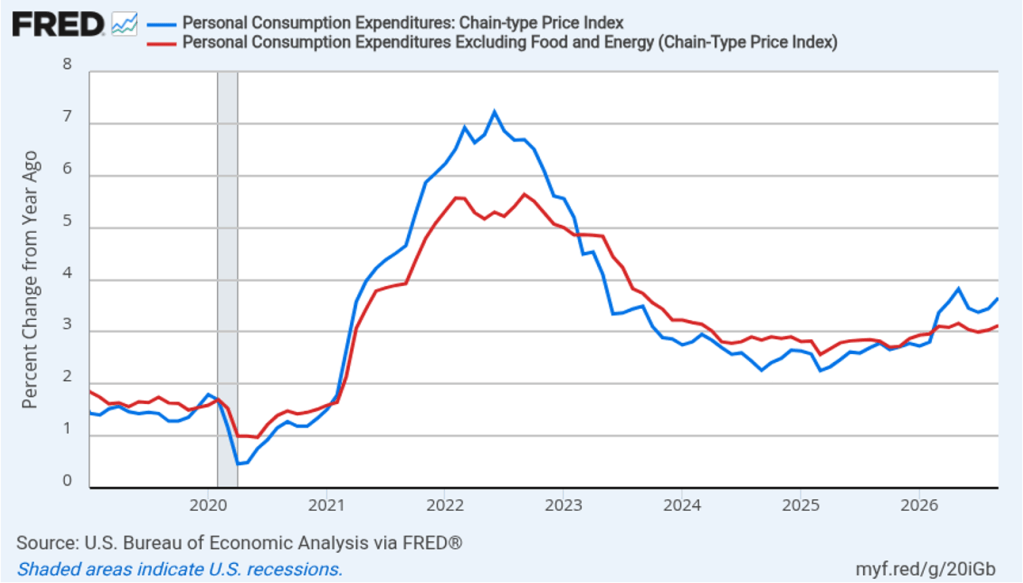
The following figure shows headline PCE inflation (the blue line) and core PCE inflation (the red line)—which excludes energy and food prices—for the period since January 2019, with inflation measured as the percentage change in the PCE from the same month in the previous year. In September, headline PCE inflation was 3.6 percent, up from 3.4 percent in August. Core PCE inflation in September was 3.1 percent, up form 3.0 percent in August. Headline PCE inflation was slightly below and core PCE inflation was equal to the forecast of economists surveyed by FactSet. Both headline PCE inflation and core PCE inflation remain well above the Fed’s 2 percent annual inflation target.
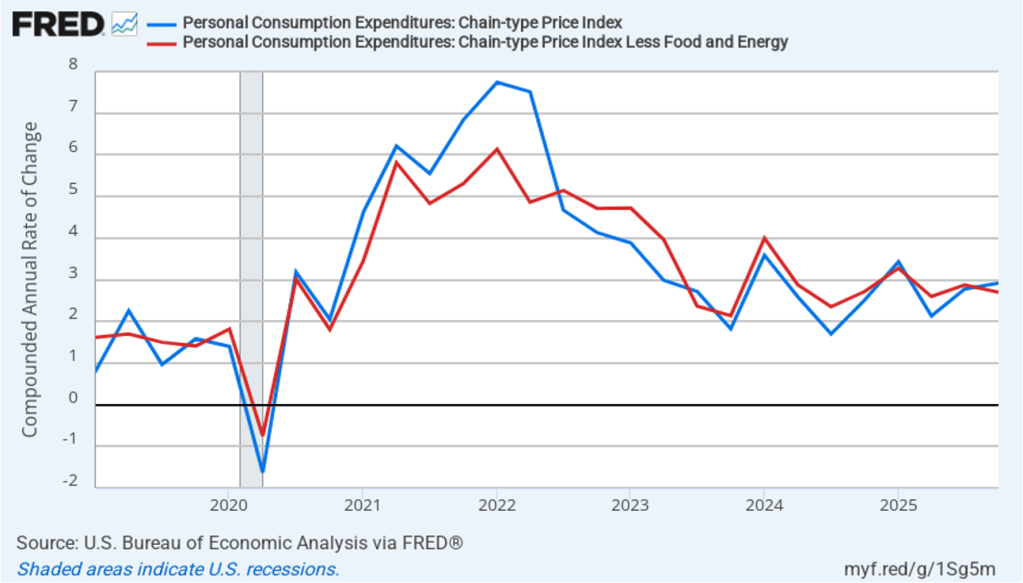
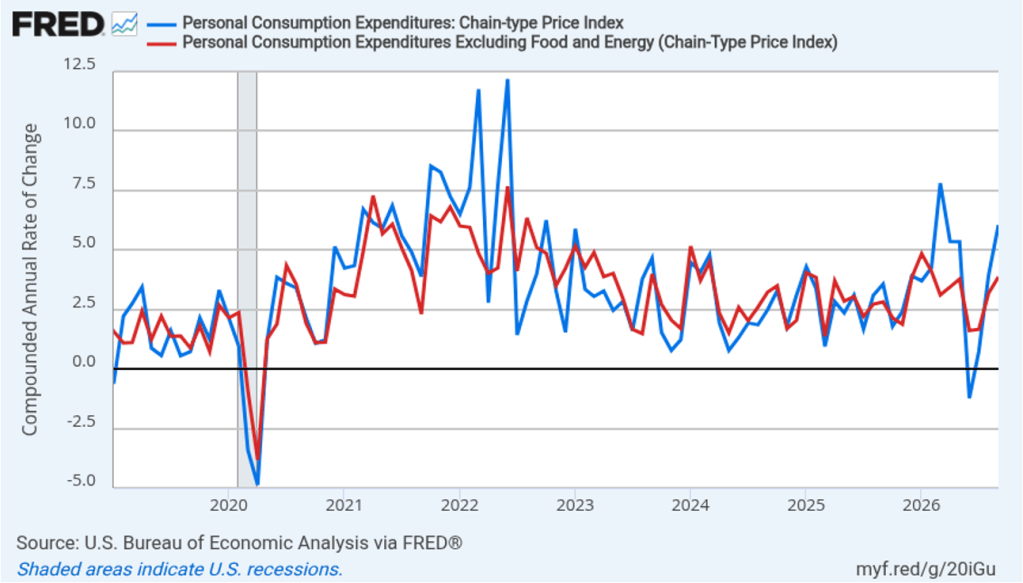
The following figure shows headline PCE inflation and core PCE inflation calculated by compounding the current month’s rate over an entire year. (Often referred to as 1-month inflation.) Measured this way, headline PCE inflation increased 6.1 percent in September from 3.9 percent in August. Core PCE inflation increased to 3.9 percent in September from 3.2 percent in August. The very high 1-month headline PCE inflation rate reflects the sharp increase in energy prices, particularly gasoline prices, during September. One-month core inflation shows a smaller, although still substantial, acceleration in inflation during September.
Fed policymakers believe that inflation in non-market services can skew PCE inflation. Non-market services are services whose prices the BEA imputes rather than measures directly. For instance, the BEA assumes that prices of financial services—such as brokerage fees—vary with the prices of financial assets. So that if stock prices rise, the prices of financial services included in the PCE price index also rise. Former Fed Chair Jerome Powell has argued that these imputed prices “don’t really tell us much about … tightness in the economy. They don’t really reflect that.” The following figure shows 12-month headline inflation (the blue line) and 12-month core inflation (the red line) for market-based PCE. (The BEA explains the market-based PCE measure here.)
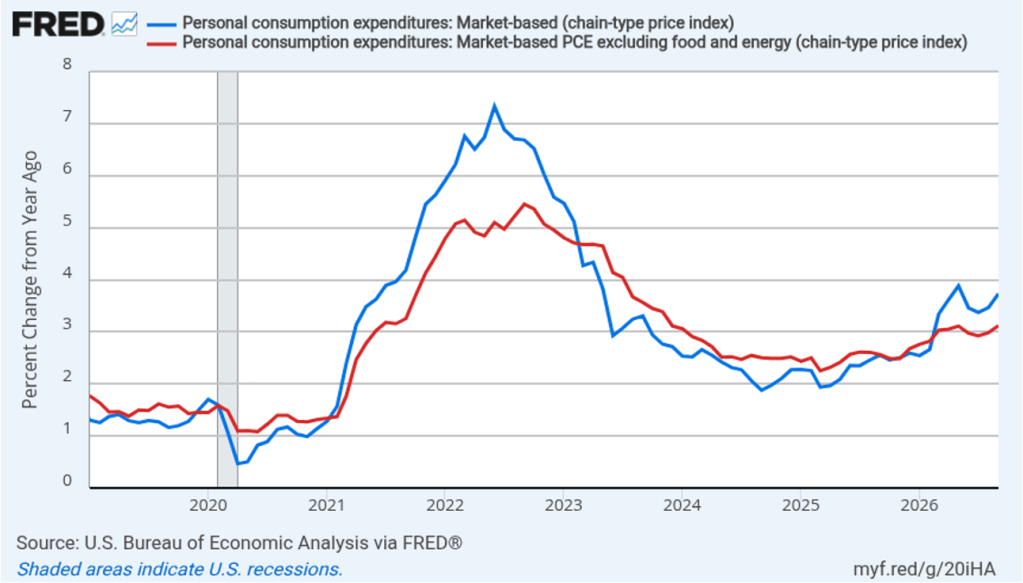
Headline market-based PCE inflation was 3.7 percent in September, up from 3.5 percent in August. Core market-based PCE inflation was 3.1 percent in September, up from 3.0 percent in August. So both market-based measures show inflation in September remaining well above the Fed’s 2 percent target.
Fed Chair Kevin Warsh argued in testimony at his confirmation hearing before the Senate that the Fed should stop relying on headline PCE inflation: “The measures [of inflation] I prefer are looking at things that are called trimmed averages. We take out all of the tail-risks, all of the one-off items, and we ask ourselves whether the generalized change in prices is having second-order effects on the economy.”
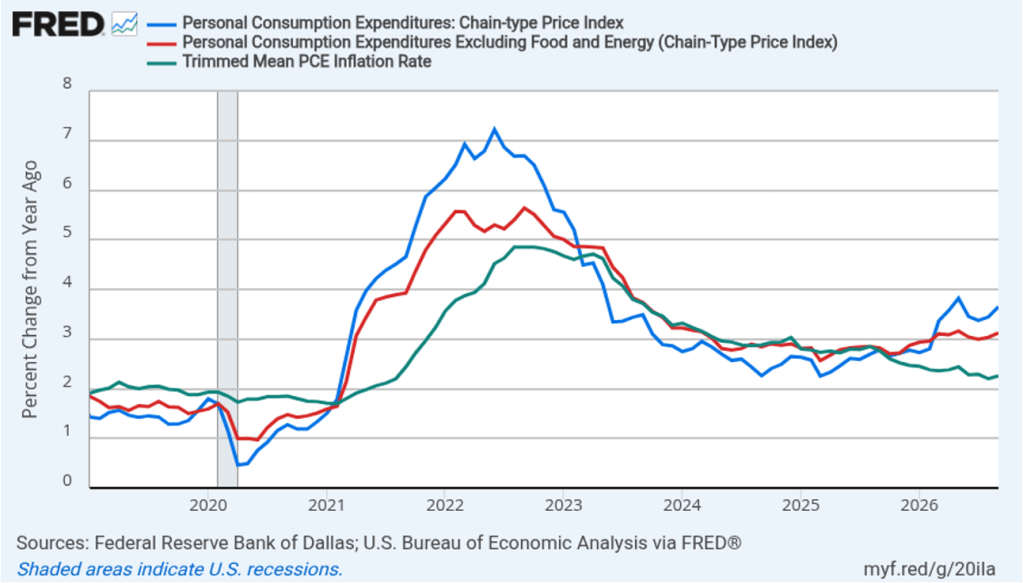
Trimmed-mean PCE inflation drops the 31 percent of goods and services with the highest inflation rates and the 24 percent of goods and services with the lowest inflation rates. A closely related measure, median PCE inflation, is calculated by listing the inflation rate in each individual good or service included in the PCE and identifying the inflation rate of the good or service that is in the middle of the list—that is, the inflation rate in the price of the good or service that has an equal number of higher and lower inflation rates.
The following figure shows 12-month headline PCE inflation the (blue line), core PCE inflation (the red line) and trimmed-mean PCE inflation (the green line). Trimmed-mean PCE inflation in September was 2.3 percent, well below both headline and core PCE inflation.
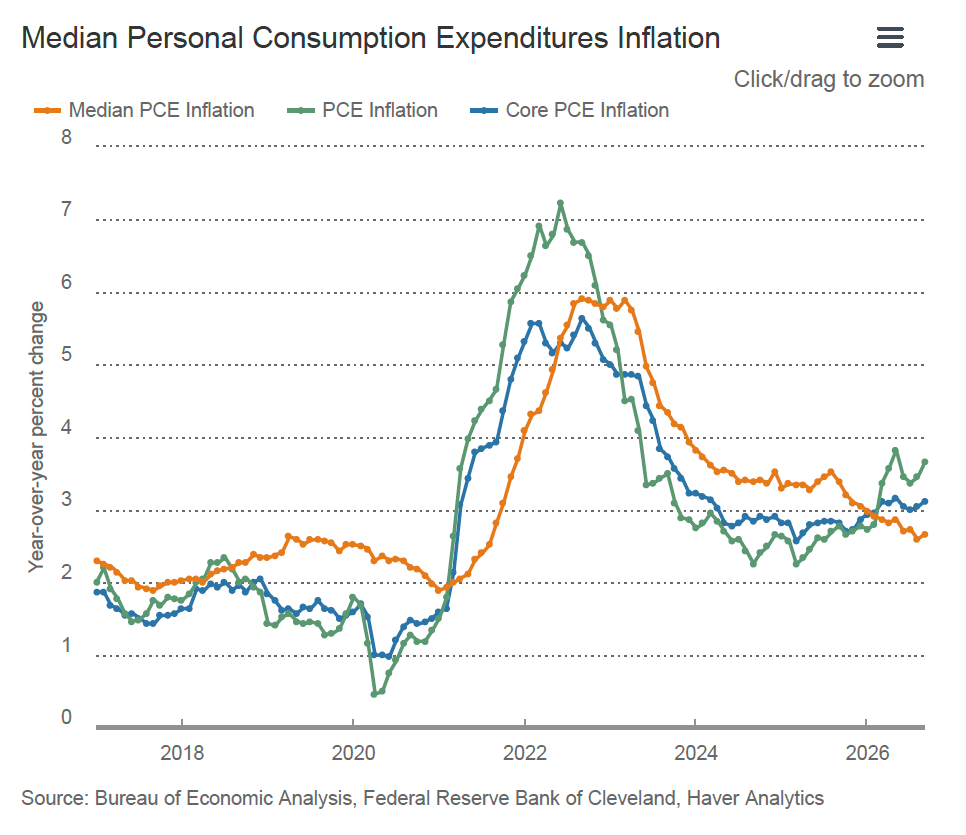
The following figure from the website of the Federal Reserve Bank of Cleveland shows headline PCE inflation (the green line), core PCE inflation (the blue line), and median PCE inflation (the brown line). In September, median PCE inflation was 2.7 percent, which was up from 2.6 percent in August. So Warsh has a point that these two measures of inflation, which are less affected by particularly high or low rates of inflation in some goods and services, indicate that inflation has been running below the Fed’s currently preferred measure of 12-month headline PCE inflation. But these measures also show inflation still running well above the Fed’s 2 percent annual inflation target.
Today’s macro data releases appear to have caused investors who buy and sell federal funds futures contracts to believe that the Federal Open Market Committee (FOMC) is now somewhat less likely to raise its target for the federal funds rate at the committee’s next meeting on December 8–9. Trading on the federal funds futures market today implies that the probability of a target rate increase at that meeting is 74.9 percent, down from a probability of 84.2 percent yesterday.