As Expected, the FOMC Raises Its Federal Funds Rate Target

Photo from federalreserve.gov

Today, the Federal Open Market Committee (FOMC) met expectation by raising its target range for the federal funds rate by 0.25 percentage points (25 basis points) from the range of 3.50 percent to 3.75 percent that had prevailed since December 10 of last year. As of yesterday, trading in the federal funds rate futures market had implied a 93.5 percent probability of a 25 basis point increase. Financial markets had been convinced that a rate increase was coming since Fed Chair Kevin Warsh’s speech at the Federal Reserve Bank of Kansas City’s economic policy symposium in Jackson Hole, Wyoming in late August. (We discussed Warsh’s speech in this blog post.) There had been some speculation in the business press that one or more committee members would dissent from a rate increase, but the vote turned out to be unanimous. Today was the first time the committee had increased the target range since July 2023.

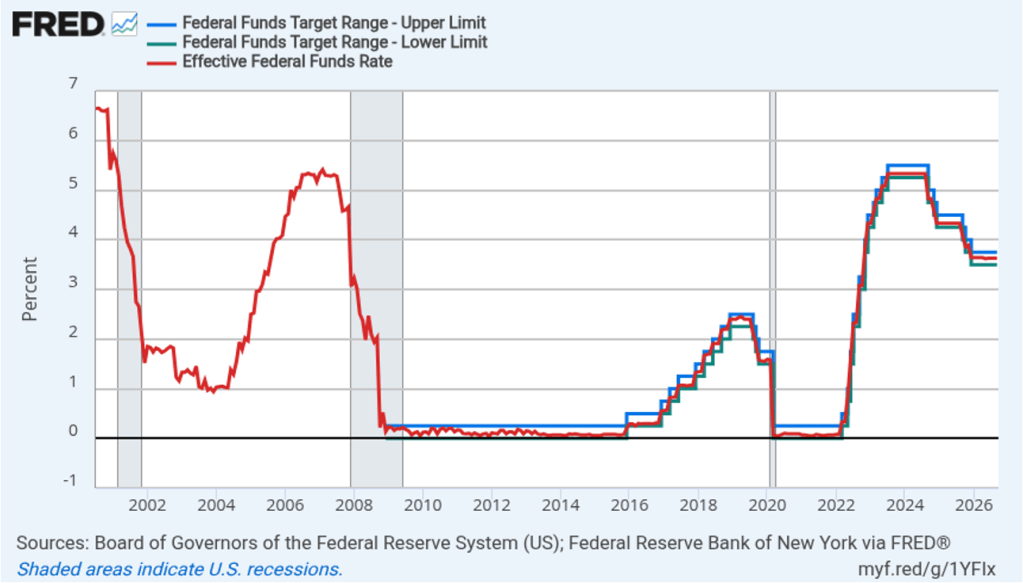
The following figure shows for the period from 2001 through yesterday, the upper bound (the blue line) and the lower bound (the green line) for the FOMC’s target range for the federal funds rate, as well as the actual values for the federal funds rate (the red line). Before December 2008, the Fed announced a single numerical target for the federal funds rate, rather than a target range. Note that the Fed has been successful in keeping the value of the federal funds rate in its target range. (We discuss the monetary policy tools the FOMC uses to maintain the federal funds rate within its target range in Macroeconomics, Chapter 15, Section 15.2 (Economics, Chapter 25, Section 25.2).)
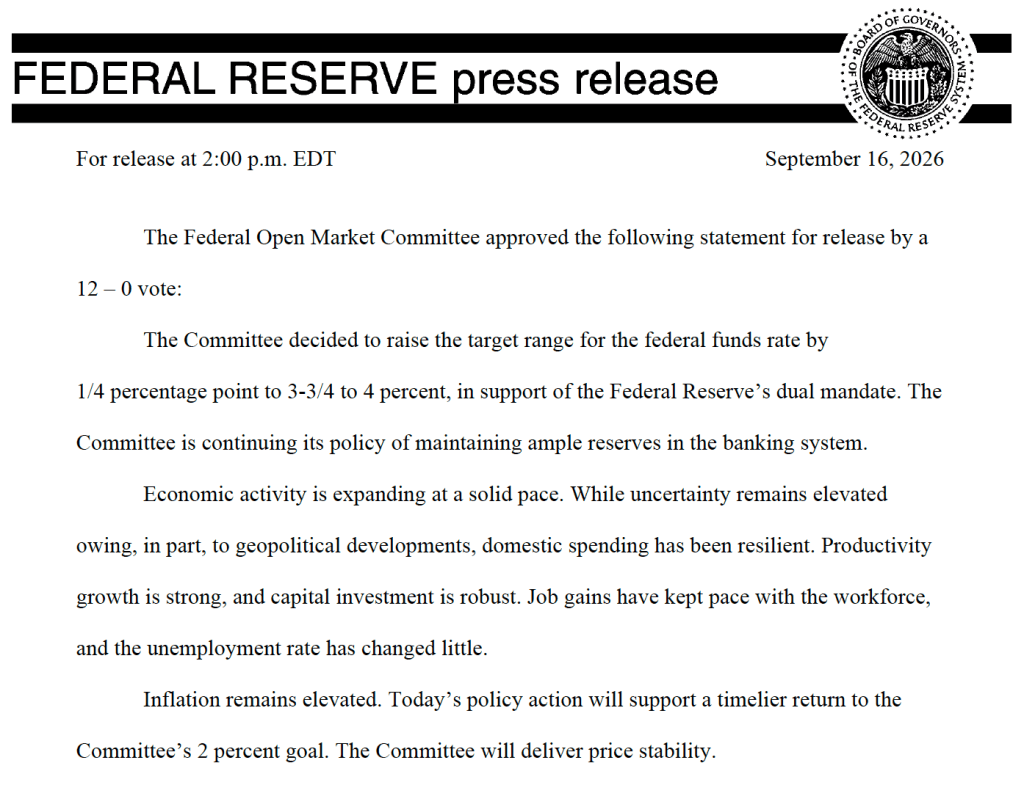
As with the policy statements issued following Warsh’s previous two FOMC meetings, today’s policy statement was short and did not include any discussion of the circumstances under which further target rate increases might occur—so-called forward guidance. We discuss forward guidance in Macroeconomics, Chapter 15 (Economics, Chapter 25).
After the meeting, the committee also released a “Summary of Economic Projections” (SEP)—as it typically does at its March, June, September, and December meetings. The SEP presents median values of the, typically, 19 committee members’ forecasts of key economic variables. In a press conference following the meeting, Warsh indicated that he didn’t submit forecasts, just as he hadn’t submitted forecasts for the SEP released after the June meeting. He indicated that the future of the SEP is one of the issues to be considered by his new committee on Fed communications.

The forecasts of key economic variables from the SEP are summarized in the following table, reproduced from the release. (Note that only 5 of the district bank presidents vote at FOMC meetings, although all 12 presidents participate in the discussions and prepare forecasts for the SEP.)
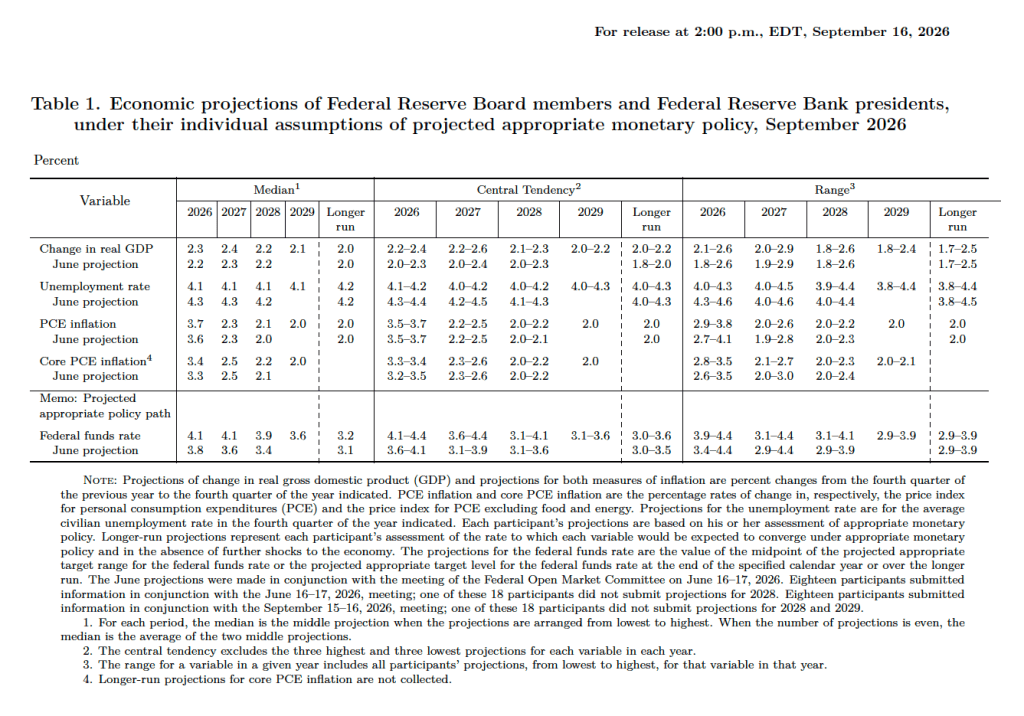
There are several aspects of these forecasts worth noting:

  1. Compared with the previous SEP in June, the committee members raised their forecast of real GDP growth in 2026 slightly from 2.2 percent to 2.3 percent. The committee members left unchanged their forecast of long-run growth in real GDP at 2.0 percent. The unchanged long-range forecast indicates that the committee members are not anticipating a large, sustained increase in economic growth caused by increased use of artificial intelligence (AI). Consistent with raising their forecast of real GDP growth in 2026, the committee lowered its forecast of the unemployment rate in the fourth quarter of 2026 from 4.3 percent to 4.1 percent. The committee members left their forecast of the long-run rate of unemployment, often called the natural rate of unemployment, unchanged at 4.2 percent. 
  2. Committee members raised their forecast of personal consumption expenditures (PCE) price inflation in 2026 to 3.7 percent from 3.6 percent in June. They left their forecast of inflation in 2027 unchanged at 2.3 percent and forecast that PCE inflation would not decline to the Fed’s 2.0 percent annual target until 2029.
  3. The committee’s forecasts of the federal funds rate at the end of each year from 2026 through 2028 were increased, indicating that the committee sees the federal funds rate as likely to be “higher for longer.” The forecast for the long-run federal funds rate was raised from 3.1 percent to 3.2 percent.

There is always much discussion in the business press and among investment analysts about the dot plot, shown below. Each dot in the plot represents the projection of an individual committee member. (The committee doesn’t disclose which member is associated with which dot.) Note that there are 18 dots, representing the 6 members of the Fed’s Board of Governors who provided forecasts and all 12 presidents of the Fed’s district banks.
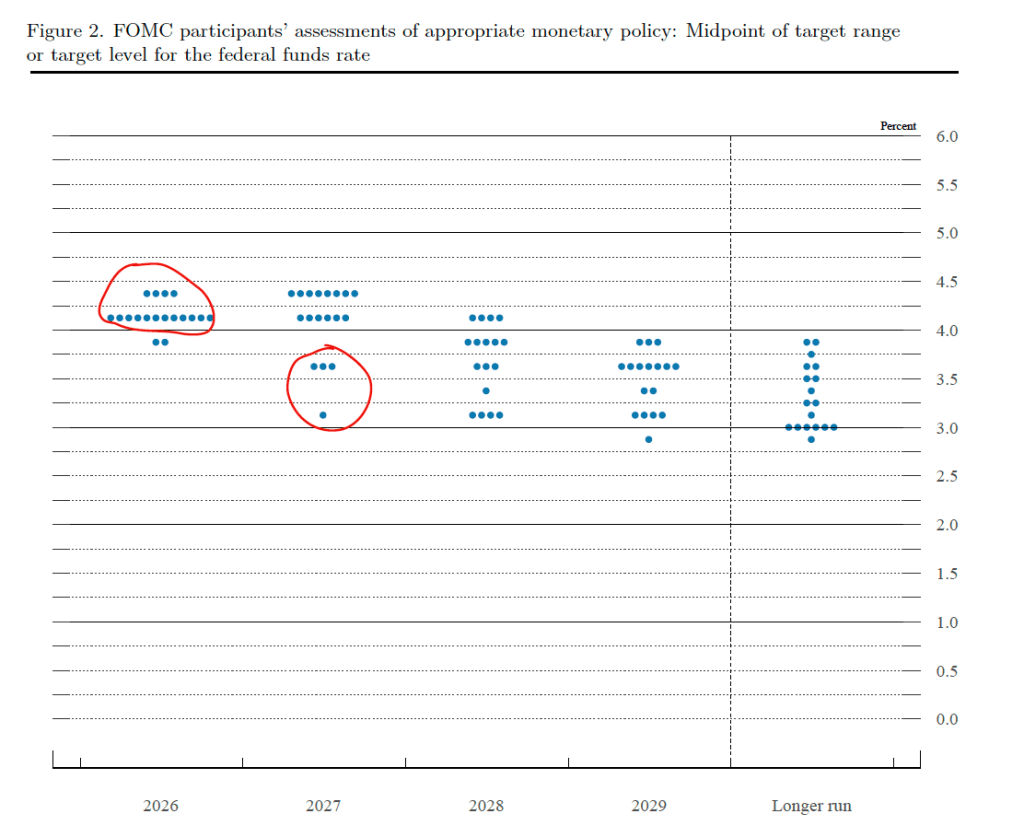
The dots plotted on the far left of the figure represent the projections by the 18 members of the value of the federal funds rate at the end of 2026. The plots indicate that, at this point, 16 members of the committee (circled in red) forecast at least one additional 25 basis point increase in the target range for the federal funds rate before the end of the year, with only 2 members expecting that there will be no further increases this year. For 2027, four members (circled in red) expect that the target range will be cut during the year, with the rest expecting either that the rate increases made this year will be maintained or that there will be one additional 25 basis point increase. The dots plotted on the far right of the figure indicate that there is substantial disagreement among committee members as to what the long-run value of the federal funds rate—the so-called neutral rate—should be. Of course, the plots only represent the forecasts of the committee members and individual committee members are likely to adjust their forecasts as additional macroeconomic data become available in the coming months.

At his press conference following the meeting, Warsh resisted attempts by reporters to get him to expand on the circumstances under which the committee might implement further increases in the target range. He characterized today’s rate increase as removing “a dose of accommodation” from the economy, which reflected the committee’s belief that the economy was experiencing full employment with persistently high inflation. The closest he came to engaging in forward guidance was the statement that “We must be confident that underlying inflation is moving towards our objective. This has not been satisfied.”

Warsh was asked what had changed since the July meeting at which the committee had kept the target range unchanged. in reply, he indicated that the committee believed that since July the economy had strengthened, inflation had continued to above target, and “geopolitical” factors had contributed to higher prices.
FOMC Holds Target Rate Constant as Warsh Promises Procedural Changes after First Meeting as Chair

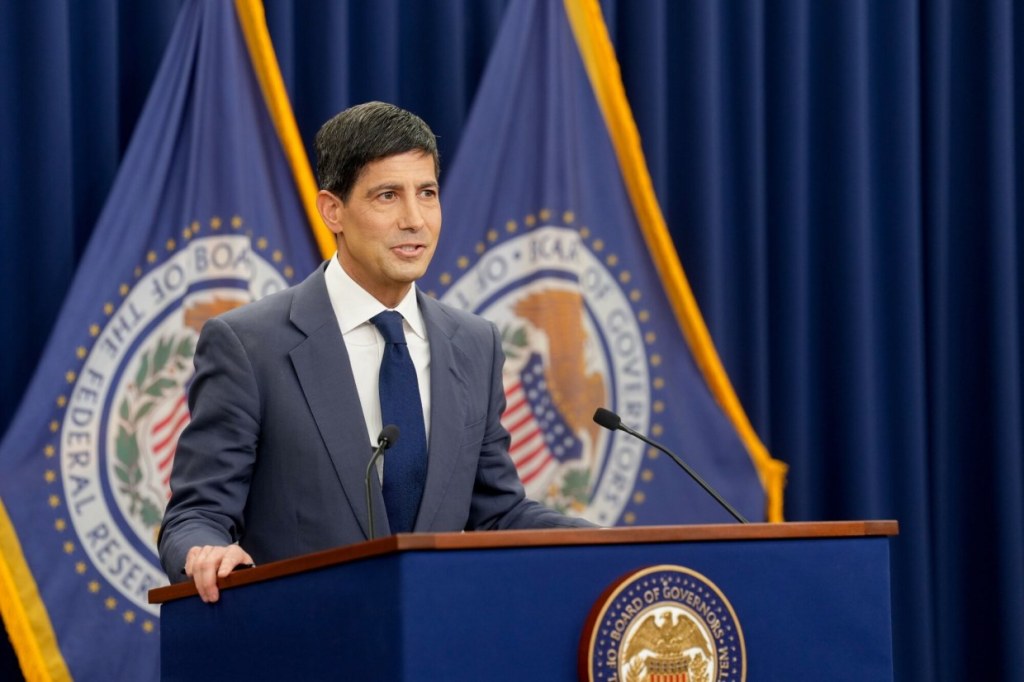
Photo of Kevin Warsh from bloomberg.com via the Wall Street Journal

It was a foregone conclusion that at its meeting that ended today, the Federal Open Market Committee (FOMC) would leave unchanged its target range for the federal funds rate at 3.50 percent to 3.75 percent. There was great interest, however, about whether at his first meeting as chair of the committee, Kevin Warsh might indicate changes he would push for in the committee’s procedures.

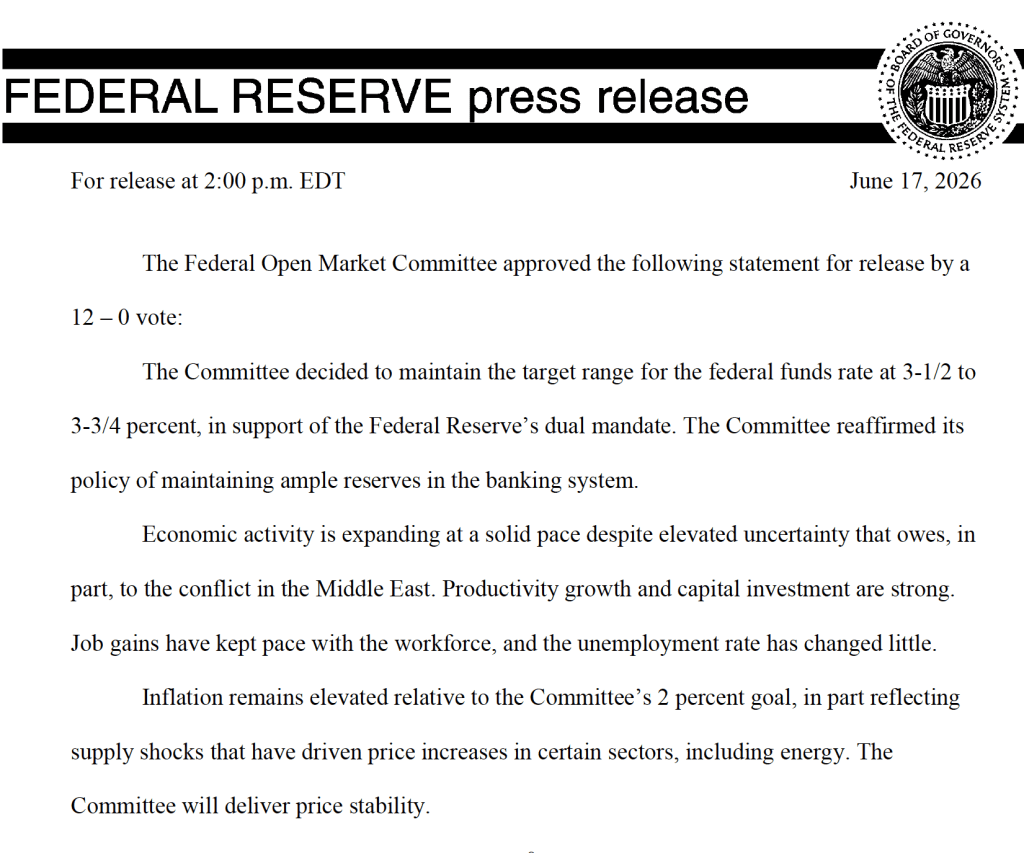
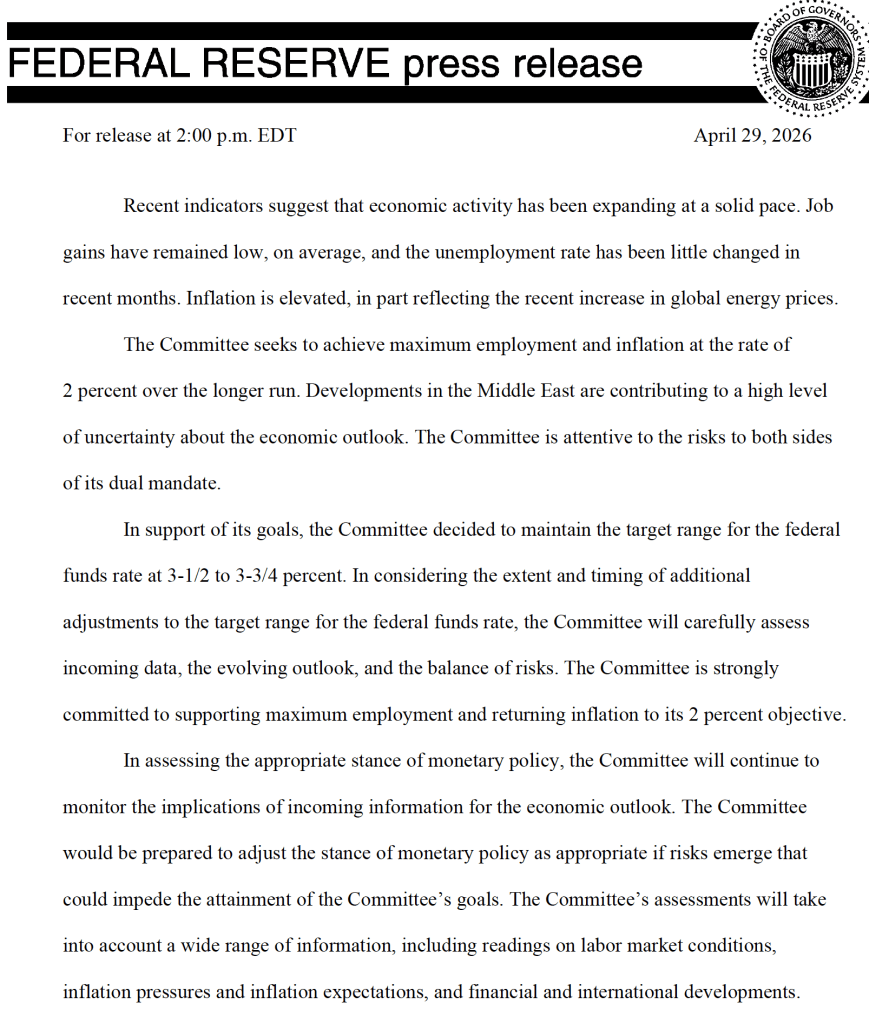
One immediate change was evident in the statement that the committee released at the end of its meeting. The first statement reproduced below is from April 29, the last meeting Jerome Powell presided over as chair. The second statement is the statement that the committee released today.

The statement released today is much shorter and omits any mention of how the committee might respond in the future to new economic data, other than the simple statement that, “The Committee will deliver price stability.”

The brevity of the statement reflects the skepticism Warsh had voiced in his Senate confirmation hearings on the usefulness of forward guidance, or statements by the FOMC about how it will conduct monetary policy in the future. We discuss forward guidance in Macroeconomics, Chapter 15 (Economics, Chapter 25).

In his press conference following the meeting, Warsh announced that he was forming five new committees to look at: 1) Fed communications, 2) the Fed’s balance sheet, 3) the Fed’s use of data, 4) the effects of technological change and productivity, particularly with respect to artificial intelligence, and 5) the inflation process, with the aim of identifying key drivers of inflation. He indicated that the committees would include members from outside the Fed and were expected to report their findings by the end of the year.

After the meeting, the committee also released a “Summary of Economic Projections” (SEP)—as it typically does after its March, June, September, and December meetings. The SEP presents median values of the, typically, 19 committee members’ forecasts of key economic variables. Notably, Warsh indicated that, although he encouraged his colleagues on the committee to continue submitting their forecasts to be compiled in the SEP, he didn’t submit forecasts. He indicated that the future of the SEP is one of the issues to be considered by his new committee on Fed communications.

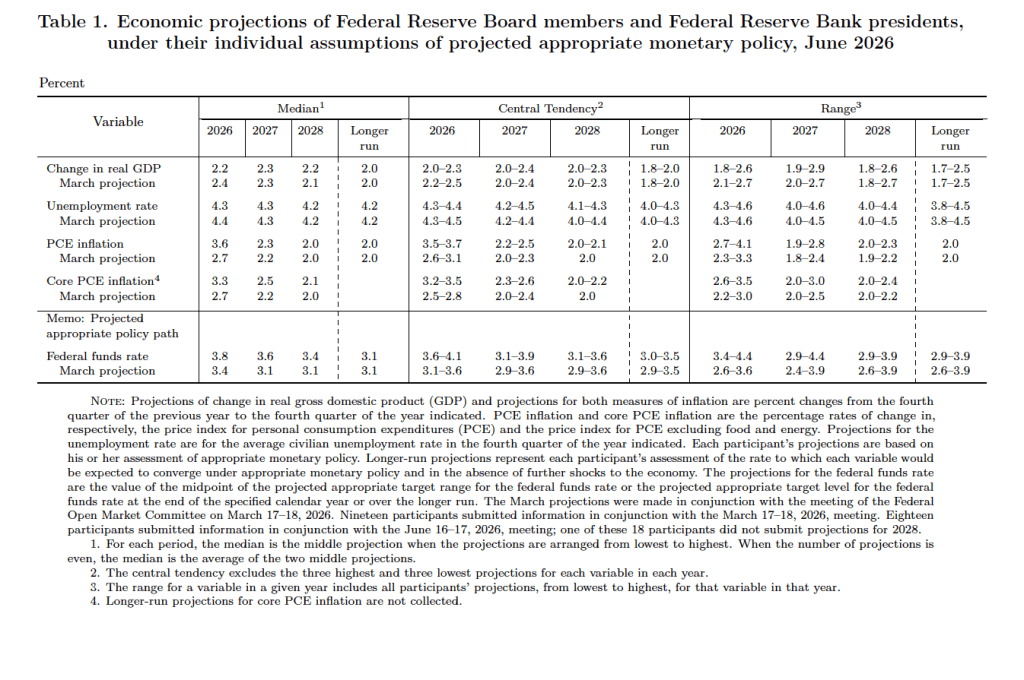
The forecasts of key economic variables from the SEP are summarized in the following table, reproduced from the release. (Note that only 5 of the district bank presidents vote at FOMC meetings, although all 12 presidents participate in the discussions and prepare forecasts for the SEP.)

There are several aspects of these forecasts worth noting:

  1. Compared with the previous SEP in March, the committee members reduced their forecast of real GDP growth in 2026 from 2.4 percent to 2.2 percent. The committee members left unchanged their forecast of long-run growth in real GDP at 2.0 percent. Despite reducing their forecast of real GDP growth in 2026, the committee lowered their forecast of the unemployment rate in 2026 from 4.4 percent to 4.3 percent. The committee members left their forecast of the long-run rate of unemployment, often called the natural rate of unemployment, unchanged at 4.2 percent. 
  2. Committee members significantly raised their forecast of personal consumption expenditures (PCE) price inflation in 2026 to 3.6 percent from 2.7 percent in March. They raised their forecast of inflation in 2027 slightly and continued to forecast that PCE inflation will decline to the Fed’s 2.0 percent annual target in 2028.
  3. The committee’s forecasts of the federal funds rate at the end of each year from 2026 through 2028 were increased, indicating that the committee sees the federal funds rate as likely to be “higher for longer.” The forecast for the long-run federal funds rate was left unchanged at 3.1 percent.

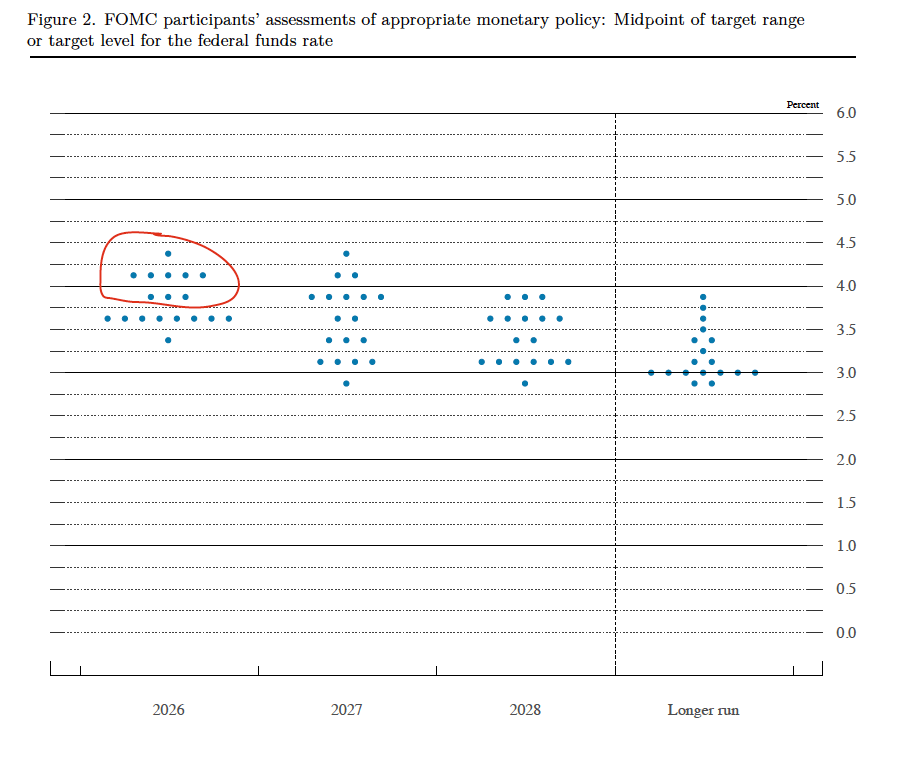
Prior to the meeting, there was much discussion in the business press and among investment analysts about the dot plot, shown below. Each dot in the plot represents the projection of an individual committee member. (The committee doesn’t disclose which member is associated with which dot.) Note that there are 18 dots, representing the 6 members of the Fed’s Board of Governors who provided forecasts and all 12 presidents of the Fed’s district banks. 

The dots plotted on the far left of the figure represent the projections by the 18 members of the value of the federal funds rate at the end of 2026. The plots indicate that at this point eight members of the committee forecast no change in the federal funds rate this year, nine members (circled in red) expect at least one increase in the federal funds rate by the end of the year, and only one member expected that there would be a cut in the federal funds by year’s end. The dots plotted on the far right of the figure indicate that there is substantial disagreement among committee members as to what the long-run value of the federal funds rate—the so-called neutral rate—should be. Of course, the plots only represent the forecasts of the committee members and individual committee members are likely to adjust their forecasts as additional macroeconomic data become available in the coming months.

Warsh indicated at his press conference that it was unlikely that he would hold a press conference after each meeting of the committee as Jerome Powell had been doing beginning with the January 2019 meeting.

Warsh made several other notable points at the press conference. He reiterated that the Fed’s inflation target would remain an annual increase of 2.0 percent in the PCE. He noted that he saw the current level of the federal funds rate as having a restrictive effect on only the housing market. And he expressed dissatisfaction with how the economic statistics the FOMC relies upon when setting policy were being compiled. He indicated that the new committee on the Fed’s use of data might formulate suggestions to other federal government agencies, such as the Bureau of Economic Analysis and the Bureau of Labor Statistics, on changes in how they collect data.

FOMC Holds Its Target for the Federal Funds Rate Steady at Powell’s Next-to-Last Meeting

Photo from federalreserve.gov

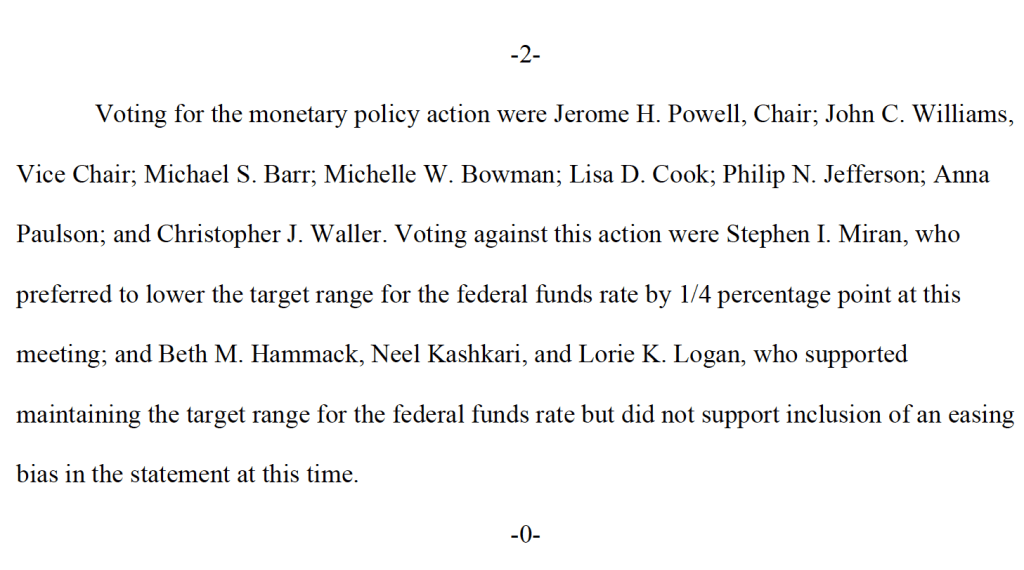
Today’s meeting of the Federal Reserve’s policymaking Federal Open Market Committee (FOMC) had the expected result with the committee deciding to leave unchanged its target for the federal funds rate at its current range of 3.50 percent to 3.75 percent. The members of the committee voted 11 to in favor of the decision. Fed Governor Stephen Miran voted against the decision, preferring to lower the target range for the federal funds rate by 0.25 percentage point (25 basis points).

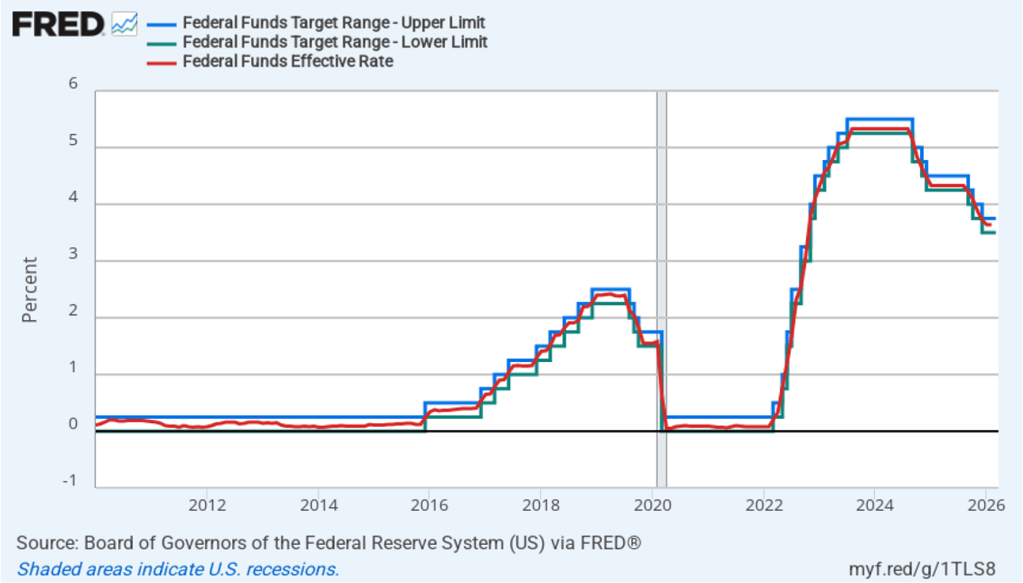
The following figure shows for the period since January 2010, the upper bound (the blue line) and the lower bound (the green line) for the FOMC’s target range for the federal funds rate, as well as the actual values for the federal funds rate (the red line). Note that the Fed has been successful in keeping the value of the federal funds rate in its target range. (We discuss the monetary policy tools the FOMC uses to maintain the federal funds rate within its target range in Macroeconomics, Chapter 15, Section 15.2 (Economics, Chapter 25, Section 25.2).)

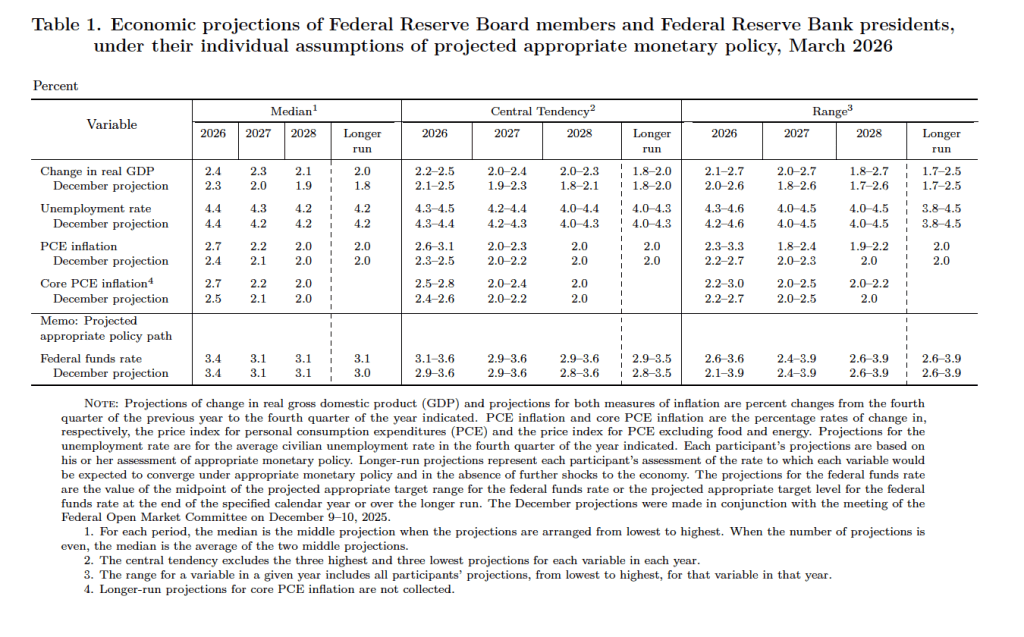
After the meeting, the committee also released a “Summary of Economic Projections” (SEP)—as it typically does after its March, June, September, and December meetings. The SEP presents median values of the 19 committee members’ forecasts of key economic variables. The values are summarized in the following table, reproduced from the release. (Note that only 5 of the district bank presidents vote at FOMC meetings, although all 12 presidents participate in the discussions and prepare forecasts for the SEP.)

There are several aspects of these forecasts worth noting:

  1. Compared with December, the committee members increased their forecasts of real GDP growth for each year from 2025 through 2027. The committee members also increased their forecast of long-run growth in real GDP to 2.0 percent from 1.8 percent in December. Although that increase may seem small, as we discuss in Macroeconomics, Chapter 10, Section 10.1 (Economics, Chapter 20, Section 20.1), over time, small increases in growth rates in real GDP can result in substantial increases in the standard of living. Despite increasing their forecast of growth in real GDP, committee members left their forecasts of the unemployment rate unchanged. 
  2. Committee members reduced their forecast for 2026 of personal consumption expenditures (PCE) price inflation significantly to 2.7 percent from 2.4 percent in December. They raised their forecast for inflation in 2027 slightly and continued to forecast that PCE inflation will decline to the Fed’s 2.0 percent annual target in 2028.
  3. The committee’s forecasts of the federal funds rate at the end of each year from 2026 through 2028 were unchanged but the forecast for the long-run federal funds rate was increased to 3.1 percent from 3.0 percent in December.

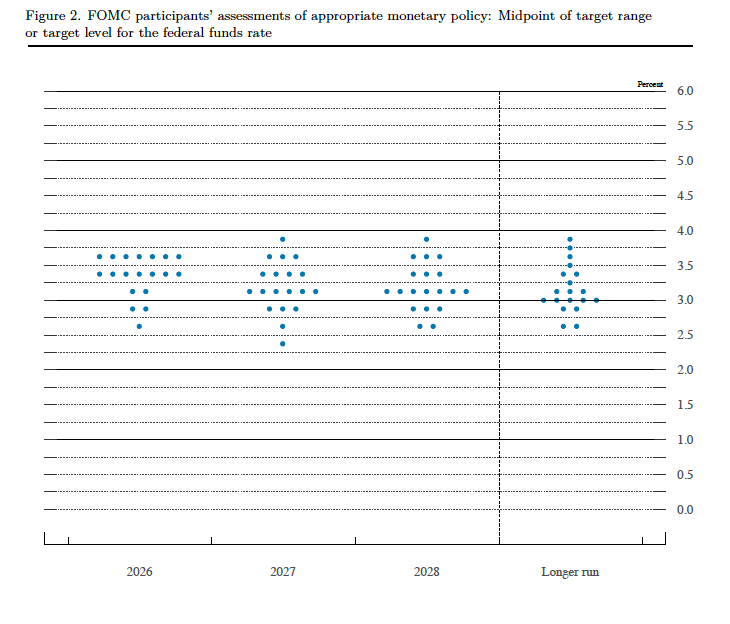
Prior to the meeting there was much discussion in the business press and among investment analysts about the dot plot, shown below. Each dot in the plot represents the projection of an individual committee member. (The committee doesn’t disclose which member is associated with which dot.) Note that there are 19 dots, representing the 7 members of the Fed’s Board of Governors and all 12 presidents of the Fed’s district banks. 

The plots on the far left of the figure represent the projections by the 19 members of the value of the federal funds rate at the end of 2026. The plots indicate that at this point there is majority support on the committee for one 25 basis point cut by the end of the year in the federal funds rate from its current range of 3.50 percent to 3.25 percent to a range of 3.25 percent to 3.00 percent. The plots on the far right of the figure indicate that there is substantial disagreement among committee members as to what the long-run value of the federal funds rate—the so-called neutral rate—should be. Of course, the plots only represent the forecasts of the committee members and individual committee members are likely to adjust their forecasts as additional macroeconomic data become available in the coming months.

During his press conference following the meeting, Powell indicated that the effects of the conflict in Iran on the U.S. economy were uncertain. He noted that traditionally central banks “look through” increases in oil prices because they result in only a one-time increase in the price level rather than in sustained inflation. He noted, though, that the committee might take steps to offset the effect of higher oil prices if there were an indication that the price increases were affecting long-run expectations of inflation.

He noted that the increase in inflation in recent months was largely due to the effects of the increase in tariffs on goods prices. Powell indicated that committee members expect that the tariff increases will have largely passed through the economy by the middle of the year. Powell attributed committee members increasing their forecast of long-run growth in real GDP to their expectation that recent increases in productivity growth would be sustained.

Finally, Powell discussed the end of his term as chair on May 15. (Powell will be chair for one more meeting of the FOMC on April 28–29.) He stated that if the Senate doesn’t confirm Kevin Warsh as his replacement as chair by May 15, he would follow the law and Fed tradition by continuing to serve as chair in a temporary capacity. Powell’s term as a member of the Board of Governors doesn’t end until January 31, 2028. He indicated that he will only step down from his position on the Board if the legal case the Department of Justice has opened against him for having given allegedly false testimony to Congress is “well and truly over, with transparency and finality.”