In Chapter 12 of the textbook, we discuss developments over the years in the intensely competitive egg market. Many of the 65,000 egg farmers in the United States have continued to produce eggs using traditional methods. But some egg farmers have adopted cage-free methods that allow chickens to have sufficient room to move around. Using cage-free methods increases a farmer’s costs but some consumers are willing to pay more for these eggs. More recently, some egg farmers have turned to selling “pastured eggs” laid by chickens that are allowed to roam freely outside. Raising pastured eggs has even higher costs than raising eggs using cage-free methods, but pastured eggs also sell for higher prices.
As consumer willingness to spend on eggs produced in ways that involve more humane treatment of chickens increases, we’d expect that egg farmers will adapt by embracing these methods. But in 2021, a development occurred in the egg market that was much more difficult for egg farmers to respond to. Some consumers have been moving away from animal products to plant-based replacements. These consumers have a variety of concerns about animal products: Some consumers have ethical concerns about consuming any animal products, others believes consuming these products may have negative health effects, while others are concerned by what they believe to be the negative effects of farming on the environment.
Many people are familiar with the Impossible company’s “impossible burger,” a hamburger made from soy and potatoes rather than from beef. But it’s less well known that several companies have begun selling eggs made from plants. San Francisco-based Eat Just, Inc. has begun selling in the United States eggs made from mung beans and in October 2021 was authorized to begin selling these eggs in Europe. The Swiss firm Nestlé under its Garden Gourmet brand has also begun selling in Europe eggs made from soy. Nestlé’s eggs are sold in liquid form and are primarily intended as a substitute for natural eggs in cooking.
As of late 2021, plant-based eggs have captured only a tiny slice of the egg market. But if their popularity should increase significantly, it will be bad news for egg farmers. While many egg farmers have been able to adapt to changes in how they produce eggs, they lack the specialized equipment to produce plant-based eggs or access to the distribution and marketing resources necessary to sell them.
The market for eggs may be about to be disrupted in a way that will force many egg farmers out of the industry.
Sources: Corinne Gretler and Thomas Buckley, “Nestlé Tests Plant-Based Frontier With Vegan Eggs and Shrimp,” bloomberg.com, October 6, 2021; Aine Quinn, “Fake Eggs From Mung Beans Get Closer to Reality in Europe,” bloomberg.com, October 20, 2021; Jon Swartz, “Eat Just’s Plant-Based Egg Products to Come to Another 5,000 Retail Outlets,” marketwatch.com, September 2, 2020; Deena Shanker, “Faux-Egg Maker Eat Just Raises $200 Million More in Latest Round,” bloomberg.com, March 3, 2021; and Jon Emont, “Real Meat That Vegetarians Can Eat,” wsj.com, March 6 2021.
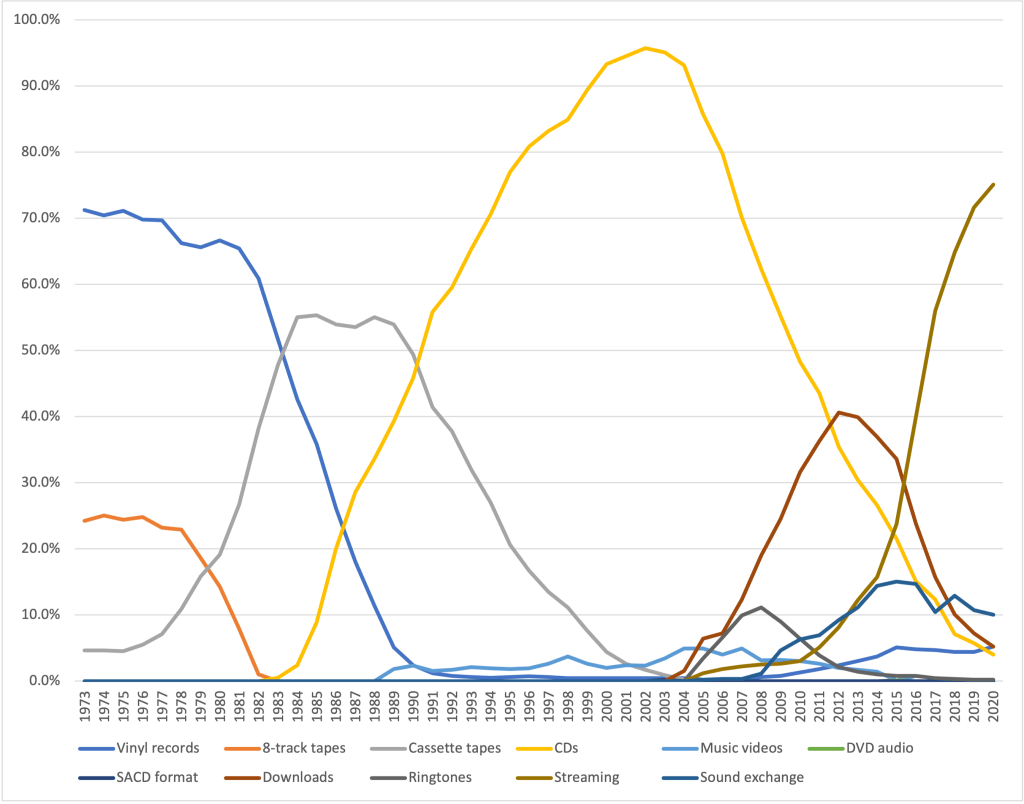
Listening to recorded music seems like a basic, uncomplicated activity, but as we discuss in the opening to Chapter 14, few markets have been as disrupted by technological change over the years as the market for recorded music. The following graph shows the distribution of revenue received by firms in the recording industry by type of music format. The data are first available for 1973.
From the 1930s to the mid-1960s, nearly all recorded music was sold on vinyl records. In the 1960s, 8-track tapes began to compete with vinyl records. In 1973, recording companies received about 71 percent of their revenue from selling vinyl records, 24 percent from selling 8-track tapes, and 5 percent from selling cassette tapes. Cassette tapes became increasingly popular after Sony introduced the Walkman, a portable cassette player, in 1979. The popularity of cassettes contributed to a sharp decline in sales of vinyl records. The share of vinyl records in revenue received from sales of recorded music dropped from 71 percent in 1975 to only 2 percent in 1990. The greater portability of cassette tapes was a significant advantage over 8-track tapes, which were most frequently used in players built into automobiles. By 1983, 8-track tapes had largely disappeared from the market.
The introduction of digital compact discs (CDs) in the early 1980s ended the rapid rise in sales of cassette tapes. By the end of the 1980s, sales of cassette tapes began to decline rapidly and their share of the market had fallen to less than 2 percent by the early 2000s.
As discussed in the opening to Chapter 14, the development by engineers in Germany of the MP3 file format made it possible to store the contents of a music CD on a file small enough to be downloaded from the internet. Apple’s opening its iTunes online music store in 2003 increased sales of music downloads, which peaked at 40 percent of the market in 2012. In that year, recording companies earned about 8 percent of their revenue from payments from streaming services like Spotify or Apple Music.
Steaming music has become increasingly popular and by 2020, 75 percent of industry revenue was earned from streaming. Ten percent was earned from “sound exchange,” which refers to revenue recording companies receive when music is used in a movie, television series, advertisement, or online video. (Some industry analysts consider sound exchange to be a form of streaming. Using that definition raises streaming’s share to 85 percent of the market.) Downloads had a market share of only 5 percent, about the same as the share of vinyl records, which had increased from a low point of less than 1 percent in 2007. CD sales continue to slowly decline and make up about 4 percent of the market.
In Chapter 14, we discuss the streaming market as an example of oligopolistic competition. When a market expands as rapidly as music streaming has, competition can be less intense because it’s possible for firms to increase their revenue as the market expands without having to attract customers from competitors. Typically when a market matures and the increase in total revenue levels off, competition can become more intense. We may see that development in the market for streaming music in coming years.
Source: Data from Recording Industry Association of America, “U.S. Sales Database.”
For the past few decades, across different presidential administrations, antitrust policy has typically involved the following key points, which we discuss in Chapter 15, Section 15.6:
Responsibility for antitrust policy is divided between the Federal Trade Commission (FTC) and the Antitrust Division of the Department of Justice (DOJ).
For horizontal mergers, the DOJ and the FTC have published numerical guidelines that provide a benchmark for their decisions on whether to oppose a merger and give firms a good idea of whether a proposed merger will be allowed.
Antitrust enforcement is focused on consumer well-being, so a merger that increases monopoly power while at the same time improving economic efficiency will be allowed if the net effect of the merger is to increase consumer surplus.
If firms disagree with a merger decision from the FTC or the DOJ, those agencies typically file a law suit in a federal court to enforce their decision. Therefore, antitrust policy ultimately depends on how the federal courts interpret the antitrust laws. (We list the most important antitrust laws in Chapter 15, Table 15.2.)
During the 2020 presidential campaign President Joe Biden did not announce a detailed policy towards antitrust and the issue played only a small role in the campaign. Late in the campaign, a Biden spokesman did state that, “growing economic concentration and monopoly power in our nation today threatens our American values of competition, choice, and shared prosperity.” Once in office, Biden’s appointments to key antitrust positions favored a more aggressive approach to antitrust policy.
The views of most Biden appointees were similar to those of Louis Brandeis who served on the U.S. Supreme Court from 1916 to 1939. Brandeis was not familiar with economics and his views on antitrust as stated in his articles and court decisions can be contradictory.
But Robert Bork of the University of Chicago in his book the Antitrust Paradox provided an influential interpretation of Brandeis’s views. According to Bork, in the early twentieth century, “the dominant goal [of antitrust policy] was the protection of consumer welfare, though Justice Louis Brandeis … was the first to give operative weight to the conflicting goal of small-business welfare.” Bork argued that an implication of Brandeis’s views was that antitrust enforcement might end up “protecting the inefficient [firms] from competition.” Similarly, Daniel Crane of the University of Michigan refers to the “’Brandeisian’ tradition, associated with US Supreme Court Justice Louis Brandeis, [which] is often described as … supporting atomistic competition because of its beneficial effects on personal liberty and autonomy.”
President Biden has appointed several people who support the Brandeis approach to antitrust including Lina Khan of Columbia University as chair of the FTC; Tim Wu of Columbia University as an adviser to the president; and Bharat Ramamurti, a former aide to Massachusetts Senator Elizabeth Warren, as deputy director of the National Economic Council. John Cassidy, an economics writer for the New Yorker, summarized their position:
“Proponents of the New Brandeis-ism contend that these agencies should act proactively—carrying out broad investigations, publishing reports, and establishing rules of conduct for companies with a great deal of market power, including tech platforms and broadband providers.”
In July 2021, President Biden issued an executive order creating a White House Competition Council. According to a statement from the White House, the purpose of the council is to: “to coordinate the federal government’s response to the rising power of large corporations in the economy.” Also in July 2021, the FTC under Chair Khan’s leadership voted to move away from the consumer welfare standard for judging anticompetitive business strategies, including merging or acquiring other firms and certain pricing decisions, such as cutting prices to below those charged by smaller rivals. The result of the FTC’s new approach is that the agency will take action against business strategies that are not directly in violation of the federal antitrust laws. The FTC is particularly concerned by strategies used over the years by large technology firms such as Facebook, Google, Amazon, and Apple.
The Biden administration’s redirection of antitrust policy has run into criticism. An article in the Wall Street Journalquoted the president of the Consumer Technology Association as stating that: “The consumer-welfare standard grounds competition policy in objective facts and evidence. By protecting consumers rather than competitors, we ensure antitrust decisions are not subjective or political.” The “consumer-welfare standard” is the standard that had been used under previous presidential administrations as we outlined in points 2. and 3. above. A possible barrier to the Biden administration’s change in policy is that ultimately it is up to the federal courts to decide the legality of a business strategy. In recent decades, the federal courts have consistently required that for a strategy to be declared illegal it must be a violation of the antitrust laws.
Until the FTC or the DOJ use the new standard to bring actions against firms and until the courts either uphold or dismiss those actions, it won’t be possible to know whether the Biden administration’s antitrust policy will end up being much different from the policies of previous administrations. It could be a number of years before actions brought under the new standard make their way through the court system.
Sources: Brent Kendall, “New Policy Gives FTC Greater Control Over How Companies Do M&A,” wsj.com, October 29, 2021; Executive Office of the President, “Fact Sheet: Executive Order on Promoting Competition in the American Economy,” whitehouse.gov, July 9, 2021; John D. McKinnon, “FTC Vote to Broaden Agency’s Mandate Seen as Targeting Tech Industry,” wsj.com, July 1, 2021; John Cassidy, “The Biden Antitrust Revolution,” newyorker.com, July 12, 2021; David McCabe and Jim Tankersley, “Biden Urges More Scrutiny of Big Businesses, Such as Tech Giants,” nytimes.com, September 16, 2021; Daniel A. Crane, “Rationales for Antitrust: Economics and Other Bases,” in Roger D. Blair and D. Daniel Sokol, The Oxford Handbook of International Antitrust Economics, Vol. 1, New York: Oxford University Press, 2015; Robert H. Bork, The Antitrust Paradox: A Policy at War with Itself, New York: Basic Books, 1978; and Kenneth G. Elzinga and Micah Webber, “Louis Brandeis and Contemporary Antitrust Enforcement,” Touro Law Review, 2015, Vol. 33, No. 1 , Article 15.
The restaurant industry was hit hard by the Covid-19 pandemic. Fast food restaurants like McDonalds and Taco Bell had their revenues hold up the best because many of their customers were experienced in using their drive-through windows, which typically remained open except during the worst of the pandemic in the Spring of 2020. Restaurants that rely on table service suffered steeper declines in revenue because even when local governments allowed them to be open, they were typically required to operate at reduced capacity. In addition, through most of 2021, some consumers were reluctant to spend an hour or more eating indoors for fear of contracting the virus.
In the years leading up to the pandemic, fast-casual restaurants like Chipotle, Panera Bread, and Cheesecake Factory had been increasing in popularity, drawing customers from both more formal table service restaurants and from fast food-food restaurants. But because of their reliance on indoor dining, many fast-casual restaurants suffered sharp declines in revenue. For instance, in the spring of 2020, Cheesecake Factory was losing $6 million per week and at one point had less than $100 million remaining on hand to meet its costs.
As we discuss in Chapter 13, Section 13.3, firms in a monopolistically competitive like restaurants have difficulty earning an economic profit in the long run. Normally, economic profit is eliminated by entry of new firms. But during the pandemic, the process was speeded up as what had been profitable business strategies suddenly no longer were.
Cheesecake Factory had been earning an economic profit by following a strategy that differentiated it from similar restaurant chains. At 10,000 square feet, the dining rooms in its restaurants are much larger than in other fast-casual restaurants and Cheesecake Factory has many more items on its menus. Both these features turned into liabilities during the pandemic because before the pandemic Cheesecake Factory’s revenue would exceed its costs only if its restaurants were operated close to their capacity. In many cities, well into 2021, government restrictions required restaurants to operate at reduced capacity. In addition, like most other restaurants, as it reopened Cheesecake Factory had trouble attracting enough servers and cooks—a particular problem given the large number of items on its menus.
Cheesecake Factory returned to profitability in 2021 by adopting a new strategy of emphasizing delivering orders and having orders available for pickup at its restaurants (“to-go” orders). This strategy was successful in part because Cheesecake Factory executives made the decision during 2020 to continue to pay its 3,000 managers during the period when most of its restaurants were closed. Doing so meant having to raise $200 million from investors to pay the managers’ salaries. Keeping managers on payroll meant that the firm had the staff on hand to successfully manage the increase in to-go and delivery orders.
The success of the strategy was helped by the fact that cheesecake turned out to be a more popular delivery item than the firm had expected. An article in the Wall Street Journal quoted the firm’s president as saying that people were ordering it for a delivery throughout the day, including people “who are just getting slices at nine o’clock at night delivered to their house.” The firm has doubled its to-go orders compared with before the pandemic and its overall sales per restaurant have increased from an average of $11 million before the pandemic to $12 million in 2021.
Is Cheesecake Factory’s recent success sustainable? In emphasizing to-go and delivery orders, Cheesecake Factory initially had an advantage over its competitors because it had retained thousands of managers who could implement this new strategy. But this advantage may not last long for two reasons: 1) as the effects of the pandemic lessen, consumers may want to return to indoor dining, so the volume of to-go and delivery orders may decline; and 2) to the extent that consumers have permanently reduced their demand for indoor dining, competitors can copy Cheesecake Factory’s approach. Many competitors in fact have devoted more resources to to-go and delivery orders and the market for this type of dining is becoming as competitive as the market for in-door dining.
Cheesecake Factory has one other advantage: Cheesecake turned out to be a particularly popular food for delivery and cheesecake sales have become a larger percentage of the firm’s revenues since the beginning of the pandemic. Although, because the word “cheesecake” is in the firm’s name, it may retain some advantage among consumers who want to order a delivery of cheesecake, competitors can easily also add cheesecake to their delivery menus.
So, our general conclusion holds that it is very difficult for firms in a monopolistically competitive industry to earn an economic profit in the long run.
Sources: Heather Haddon, “How Cheesecake to Go Saved the Cheesecake Factory,” wsj.com, October 29, 2021; Teresa Rivas, “Cheesecake Factory Stock Is Falling Because Sales Took a Nose Dive,” barrons.com, July 29, 2020; Rick Clough, “Cheesecake Factory Settles SEC Charges over Covid Statements,” bloomberg.com, December 4, 2020; Tomi Kilgore, “Cheesecake Factory Stock Jumps after Upbeat Sales Update,” marketwatch.com, June 2, 2021.
Some governments have been subsidizing purchases of electric vehicles, or more broadly, fuel-efficient vehicles to slow climate change. How well do such policies work? Are they more or less efficient than other policies intended to reduce carbon dioxide emissions?
A subsidy is a payment by the government that provides an incentive for people to take an action they otherwise wouldn’t, such as buying an electric car. Subsidies have the potential downside that they may involve payments to people to do something they would have done anyway. For instance, in the United States in 2021, buyers of electric cars were eligible for a credit of up to $7,500 against their federal income taxes. Suppose that you become aware of this subsidy only after you have already purchased an electric car. In that case, the federal government has wasted $7,500 because you would have bought the electric car even without the subsidy. The same would be true if you knew about the subsidy before you bought but because of the subsidy you bought a higher-priced electric car rather than a lower-priced one.
These complications make it difficult for policymakers to assess the efficiency of subsidizing fuel-efficient cars as a means of slowing climate change. Two recent academic papers address this difficulty.
Chia-Wen Chen of Academia Sinica in Taiwan, We-Min Hu of National Chengchi University in Taiwan, and Christopher Knittel of the Massachusetts Institute of Technology have analyzed a Chinese government program that subsidizes the purchase of fuel-efficient cars. Because the study used data from 2010 and 2011, these vehicles were fuel-efficient gasoline powered cars rather than electric cars. They find that only about 44 percent of the subsidies went to car buyers who would otherwise not have bought a fuel-efficient car. “Thus, about 56 percent of the program’s payments were ineffective ….”
The authors calculate that the subsidy cost about $89 per metric ton of carbon dioxide reduced, which is high relative to other policies, such as a carbon tax. With a carbon tax, the government taxes energy consumption on the basis of the carbon content of the energy. (We discuss a carbon tax in the opener to Chapter 5.) The authors conclude: “Paying more than $89 for a metric ton of carbon dioxide is not a cost effective way to reduce carbon dioxide; if the main policy objective of China’s subsidy program on fuel-efficient vehicles was to reduce carbon dioxide emissions, then our results suggest that it was an ineffective way to achieve this goal.”
Jianwei Xing of Peking University, Benjamin Leard of Resources for the Future, and Shanjun Li of Cornell University analyze the efficiency of the U.S. federal income tax credit for purchasing an electric vehicle. As with the study just discussed, they find that consumers who use the credit to buy an electric vehicle were likely to have otherwise bought a hybrid vehicle (a vehicle that combines an electric motor with a gasoline engine) or a relatively fuel-efficient gasoline powered car. They also find, as with the other study, that the federal subsidy is inefficient because while it increased electric vehicle sales by 29 percent, “70 percent of the [tax] credits were obtained by households that would have bought an EV without the credits.”
Because the design of a particular subsidy for buying an electric car will affect the subsidy’s efficiency, these studies are not conclusive evidence that all programs of subsidizing electric cars will be inefficient. But their results show that two existing programs in large markets—China and the United States—are, in fact, inefficient.
As we note in Chapter 5, many economists favor a carbon tax as a way to reduce carbon emissions rather than policies, such as the federal electric vehicle tax credit, that target a particular source of carbon emissions. Economists can contribute to debates over public policy by using economic principles to identify programs that are more or less likely to efficiently achieve policy goals. They can also, as the authors of these two papers do, use statistical methods to analyze the effects of particular policies.
Sources: Chia-Wen Chen, We-Min Hu, and Christopher R. Knittel, “Subsidizing Fuel-Efficient Cars: Evidence from China’s Automobile Industry,” American Economic Journal: Economic Policy, Vo. 13, No. 4, November 2021, pp. 152-184; Jianwei Xing, Benjamin Leard, and Shanjun Li, “What Does an Electric Vehicle Replace,” National Bureau of Economic Research, Working Paper 25771, February 2021.
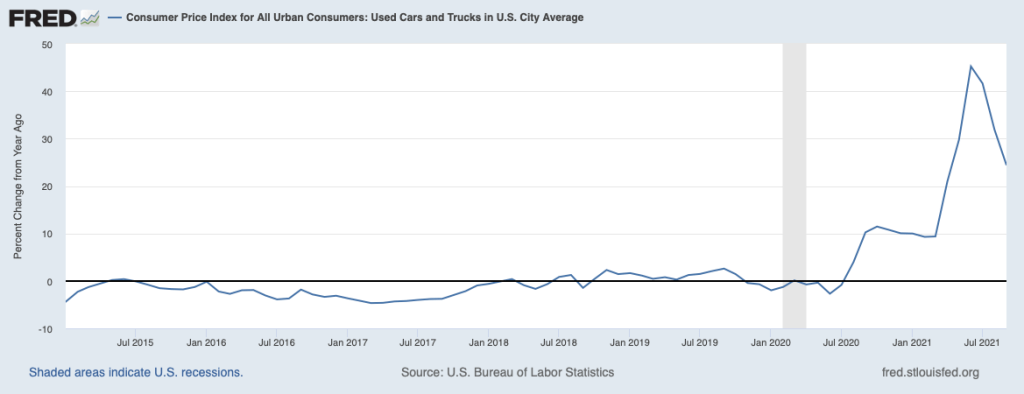
The term “sticker shock” was first used during the 1970s to describe the surprise car buyers experienced when seeing how much car prices had risen. Because inflation during that decade was so high, anyone who hadn’t bought a car for several years was unprepared for the jump in car prices. During 2020 and 2021, sticker shock returned, particularly to the used car market. Prices were increasing so rapidly that even people who had purchased a car a year or two before were surprised by the increases.
The following graph shows U.S. Bureau of Labor Statistics (BLS) data on inflation in the market for used cars in the months since January 2015. Inflation is measured as the percent change from the same month in the previous year in the used cars and trucks component of the Consumer Price Index (CPI). The CPI is the most widely used measure of inflation. Used car prices began rising in August 2020, peaking at a 45 percent increase in June 2021. Inflation at such rates over a period longer than a year is very unusual in any of components of the CPI.
What explains the extraordinary burst of inflation in used car prices during 2020 and 2021? Three factors seem to have been of greatest importance:
A decline in the supply of new cars resulting from a shortage in semiconductors caused an increase in new car prices. Rising new car prices led some consumers who would otherwise have bought a new car to enter the used car market, increasing the demand for used cars.
Because of the Covid-19 pandemic, some people became reluctant to ride buses and other mass transit, increasing the demand for both new and used cars.
As the pandemic increased in severity in the spring of 2020, most rental car companies decided to purchase fewer new cars for their fleets. After keeping a car in its fleet for one year, rental car companies typically sell the car to used car dealers for resale. Because rental car companies were selling them fewer cars, used car dealers had fewer cars on their lots. So the supply of used cars declined.
We can use the demand and supply model to explain the jump in used car prices. As shown in the following figure, the demand curve for used cars shifted to the right from D1 to D2, as some consumers who would otherwise have bought new cars, bought used cars instead, and as some people swithced from public transportation to driving their cars to work. At the same time, the supply of used cars shifted to the left from S1 to S2 because used car dealers were able to buy fewer used cars from rental car companies. The result was that the price of used cars rose from P1 to P2 at the same time that the quantity of used cars sold fell from Q1 to Q2.
Sources: Yueqi Yang, “U.S. Used-Car Prices, Key Inflation Driver, Surge to Record,” bloomberg.com, October 7, 2021; Nora Naughton, “Looking to Buy a Used Car? Expect High Prices, Few Options,” wsj.com, May 10, 2021; Cox Automotive, “13-Month Rolling Used-Vehicle SAAR,” coxautoinc.com, October 15, 2021; and Federal Reserve Bank of St. Louis.
In Economics, Chapter 10, Section 10.4, when discussing behavioral economics, we mentioned Richard Thaler’s idea of nudges, which are small changes that government policymakers or business managers can make that may affect people’s behavior. Underlying the concept of nudges is the assumption that at least some of the time people may not be making fully rational decisions (We discuss in the chapter the reasons why people may not always make fully rational decisions.) An example of a nudge is a business automatically enrolling employees into retirement savings plans to overcome the tendency of many people to be unrealistic about their future behavior.
Once vaccines for the Covid-19 virus became widely available to the general adult population in 2021, some government policymakers were concerned that not enough people were being vaccinated to quickly curb the pandemic. Some people who declined to be vaccinated had carefully thought through the decision and declined the vaccine either because they believed they were at only a small risk of developing a severe case of Covid-19 or for other reasons. But some people who were not vaccinated intended eventually to receive the injection but for various reasons had not yet done so. The second group were potentially candidates for being nudged into becoming vaccinated.
A recent National Bureau of Economic Research working paper by Tom Chang of the University of Southern California and colleagues reports an experiment that measured the effect of nudges intended to increase the likelihood of someone becoming vaccinated. The study was conducted in Contra Costa Country in northern California with 2,700 Medicaid (a state run system of health care offered to people with low incomes) recipients who agreed to participate. The study took place between May and July 2021 after all adults in the county had been eligible for several weeks to receive a vaccine. Half the people involved in the experiment received three nudges: 1) a video noting the positive effects of being vaccinated, 2) a financial incentive of either $10 or $50 if they received a vaccination within two weeks, and 3) “a highlighted convenient link to the county’s new public vaccination appointment scheduling system or just a message about getting vaccinated without a link.” The other half of the people involved in the experiment received none of these nudges.
The authors’ statistical analysis of the results of the experiment indicates that none of the nudges individually or in combination significantly raised vaccination rates. Do these results show conclusively that nudges are ineffective in increasing Covid-19 vaccination rates? The authors note that the people involved in this experiment were not representative of the U.S. population. All had low incomes (which made them eligible for Medicaid), they were relatively young, and were more likely to be Black or Hispanic than is true of the overall U.S. population. The study also took place just before the peak in the spread of the Delta variant of Covid-19 at a time when infection rates appeared to be declining. So, while for these reasons the study cannot be called a definitive, it does provide some evidence that nudges may not be effective in changing behavior towards vaccinations.
Source: Tom Chang, Mireille Jacobson, Manisha Shah, Rajiv Pramanik, and Samir B. Shah, “Financial Incentives and other Nudges Do Not Increase Covid-19 Vaccinations among the Vaccine Hesitant,” National Bureau of Economic Research, Working Paper 29403, October 2021.
In 1901, U.S. Steel became the world’s first corporation with a stock market value greater than $1 billion. In October 2021, Tesla joined Alphabet (Google’s corporate parent), Amazon, Apple, and Microsoft as the only U.S. corporations whose stock market value exceeds $1 trillion. (The Saudi Arabian Oil Company is the only non-U.S. firm with a market value above $1 trillion.)
As large U.S. corporations developed in the late nineteenth and early twentieth centuries, a key problem facing them was how to allocate the firms’ scarce financial capital across competing uses. (A thorough—and lengthy!—discussion of the development of the modern U.S. corporation is Alfred Chandler’s book, The Visible Hand: The Managerial Revolution in American Business.) By 1940, many large corporations had formed executive committees comprised of the chief executive officer (CEO), the chief operating officer (COO), and other so-called C-suite executives.
Executive committees typically don’t become involved in the day-to-day operations of the firms, leaving those responsibilities to lower level managers. Instead, executive committees devote most of their time to strategic issues such as whether to introduce new products, where to locate sales and production facilities, and how much of the firm’s resources to devote to research and development and to marketing. The decisions that an executive committee concentrates on involve how best to allocate the firm’s financial capital, funds that come from investors who buy the firm’s stocks and bonds and from the firm’s retained earnings—the firm’s profits that aren’t distributed as dividends to the firm’s shareholders. In allocating these funds, executive committees face trade-offs of the type we discuss in Chapter 2. For instance, if a U.S.-based firm uses funds to build a factory in another country, it may not have the funds to expand its domestic factories.
Allocating the firm’s financial capital will not have much effect on the firm’s profits in the short run but can be the main determinant of the firm’s profitability—and even its survival—in the long run. For instance, the failure of Blockbuster Video to expand into offering rentals of DVDs by mail or to offering a movie streaming service, resulted in the company shrinking from having 4,000 stores in the early 2000s to a single store today. In contrast, the decision in 2018 by U.S. pharmaceutical firm Pfizer to partner with BioNTech, a small German firm, to develop vaccines using messenger RNA (or mRNA) biotechnology proved very profitable for Pfizer (and saved many lives) when the Covid-19 virus led to a worldwide epidemic.
At Tesla, CEO Elon Musk has final say on strategic decisions, a situation typical of many large firms where a single executive, through stock ownership, has control of the company. One of his key decisions has been where to locate his production facilities. In making this decision, Musk faces trade-offs in how to use the scarce funds the firm has available for expanding production capacity. Building a facility in one place means not being able to fund building a facility in another place. In addition, funds used to build new factories is not available to increase research and development on autonomous cars or on other improvements to car design or technology.
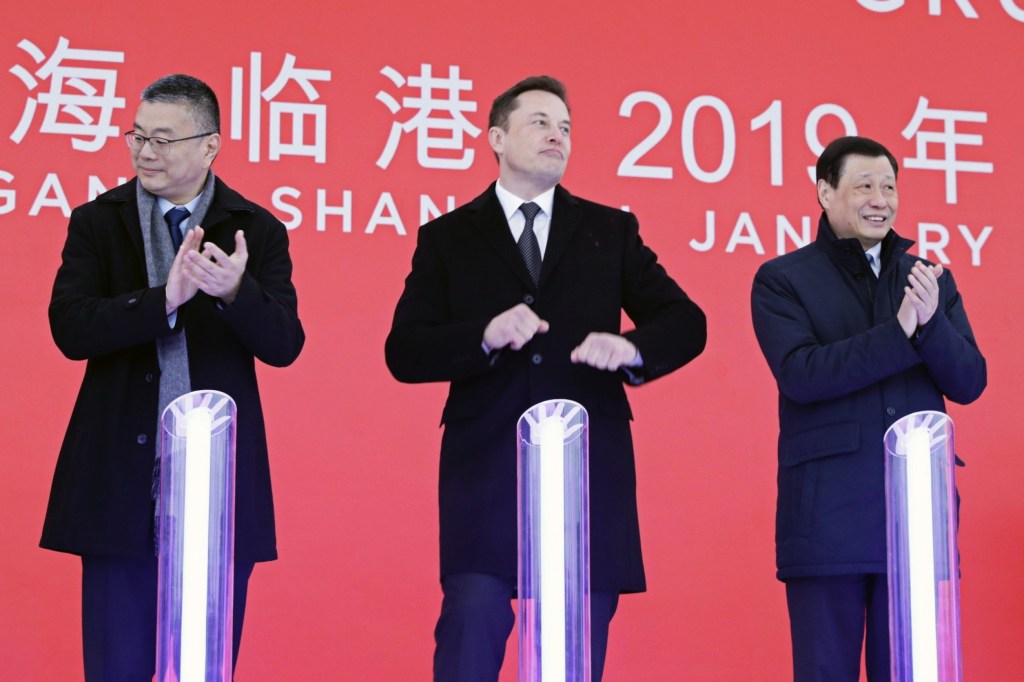
Initially, Tesla operated a single factory in Fremont, California. Built in 1962, the factory had been owned by General Motors and then jointly by GM and Toyota before being sold to Tesla in 2010. In 2019, Tesla began construction of a second factory in Shanghai, China and in 2021 was awaiting final governmental approval to build a factory in Grünheide, Germany.
Why would Tesla, or another U.S. firm, decide to build factories in other countries? The simplest answer is that firms expand their operations outside the United States when they expect to increase their profitability by doing so. Today, most large U.S. corporations are multinational firms with factories and other facilities overseas. Firms might expect to increase their profits through overseas operations for five main reasons:
To avoid tariffs or the threat of tariffs. Tariffs are taxes imposed by countries on imports from other countries. Sometimes firms establish factories in other countries to avoid having to pay tariffs.
2. To gain access to raw materials. Some U.S. firms have expanded abroad to secure supplies of raw materials. U.S. oil firms—beginning with Standard Oil in the late nineteenth century—have had extensive overseas operations aimed at discovering, recovering, and refining crude oil.
3. To gain access to low-cost labor. In recent decades, some U.S. firms have located factories or other facilities in countries such as China, India, Malaysia, and El Salvador to take advantage of the lower wages paid to workers in those countries.
4. To reduce exchange-rate risk. The exchange rate tells us how many units of foreign currency are received in exchange for a unit of domestic currency. Fluctuations in exchange rates can reduce the profits of a firm that exports goods to other countries. (We discuss this point in more detail in Economics, Chapter 28, Section 28.3 and in Macroeconomics, Chapter 18, Section 18.3.)
5. To respond to industry competition. In some instances, companies expand overseas as a competitive response to an industry rival. The worldwide competition for markets between Pepsi and Coke is an example of this kind of expansion.
All of these reasons, apart from 2., likely played a role in Tesla’s decision to build factories in China and Germany.
In 2021, Tesla was building a factory in Austin, Texas. It was also moving its corporate headquarters from California to Texas. With these actions, the firm may have been responding to lower taxes in Texas and lower housing costs for its workers.
In October 2021, Tesla’s $1 trillion stock market value seemed very high relative to the profits it was currently earning and also because it made Tesla’s value greater than the values of the next nine largest car makers combined. The price of its stock reflected the expectation among investors that Tesla’s profits would increase in future years. Tesla’s decisions about locating its new factories would play a key role in determining whether that expectation turns out to be correct.
Sources: Rebecca Elliott and Dave Sebastian, “Tesla Surpasses $1 Trillion in Market Value as Hertz Orders 100,000 Vehicles,” wsj.com, October 25, 2021; Al Root, “How Tesla Gained $175 Billion in Value From Hertz’s $4 Billion Order. It Makes Perfect Sense,” barrons.com, October 26, 2021; Bojan Pancevski and Jared S. Hopkins, “How Pfizer Partner BioNTech Became a Leader in Coronavirus Vaccine Race,” wsj.com, October 22, 2020; William Boston, “Tesla Awaits Green Light for Production in Germany,” wsj.com, October 12, 2021; Niraj Chokshi, “Tesla Will Move Its Headquarters to Austin, Texas, in Blow to California,” nytimes.com, October 13, 2021; and Alfred D. Chandler, Jr., The Visible Hand: The Managerial Revolution in American Business, Cambridge: Harvard University Press, 1977; and Tesla.com.
In 2021, SPACs were the hottest trend on the stock market and had become the leading way for companies to go public. A public company is one with shares that trade on the stock market. Private firms make up more than 95 percent of all firms in the United States. Most will never become public firms because they will never grow large enough for investors to have sufficient information on the firms’ financial health to be willing to buy the firms’ stocks and bonds.
But some firms, particularly technology firms, grow rapidly enough that they are able to become public firms. Apple, Microsoft, Google, Uber, Facebook, Snap, and other firms have followed this path. When these firms went public, they did so using an initial public offering (IPO). (We briefly discuss IPOs in Economics and Microeconomics, Chapter 8, Section 8.2 and in Macroeconomics, Chapter 6, Section 6.2.) With an IPO, a firm uses one or more investment banks to underwrite the firm’s sales of new stocks or bonds to the public. In underwriting,investment banks typically guarantee a price for stocks or bonds to the issuing firm, sell the stocks or bonds in financial markets or directly to investors at a higher price, and keep the difference, known as the spread.
Beginning in 2020 and continuing through 2021, an increasing number of firms have used a different means of going public—merging with a SPAC. SPAC stands for special-purpose acquisition company and is a firm that holds only cash—it doesn’t sell a good or service—and only has the purpose of merging with another firm that wants to go public. Once a merger takes place, the acquired firm takes the place of the SPAC in the stock market. For instance, a SPAC named Diamond Eagle Acquisition merged with online sports betting site DraftKings in April 2020. Once the merger had been completed, DraftKings took Diamond Eagle’s place on the stock market, trading under the stock symbol DKNG. By 2021, the value of SPAC mergers had risen to being three times as much as the value of IPOs.
Some firms intending to go public prefer SPACs to traditional IPOs because they can bargain directly with the managers of the SPAC in determining the value of the firm. In addition, IPOs are closely regulated by the federal government’s Securities and Exchange Commission (SEC). In particular, the SEC monitors whether an investment bank is accurately stating the financial prospects of a firm whose IPO the bank is underwriting. The claims that SPACs make when attracting investors are less closely monitored. SPAC mergers can also be finalized more quickly than can traditional IPOs.
The experience of WeWork illustrates how some firms that have struggled to go public through an IPO have been able to do so by merging with a SPAC. Adam Neumann and Miguel McLevey founded WeWork in 2010 as a firm that would rent office space in cities, renovate the space, and then sub-lease it to other firms. In 2019, the firm prepared for an IPO that would have given the firm a total value of more than $40 billion. But doubts about the firm’s business model led to an indefinite postponement of the IPO and Neumann was forced out as CEO.
WeWork was reorganized under new CEO Sandeep Mathrani and went public in October 2021 by merging with BowX Acquisition Corporation, a SPAC. Although WeWork’s stock began trading (under stock symbol WE) at a price that put the firm’s value at about $9 billion—far below the value it expected at the time of its postponed IPO two years before—investors seemed optimistic about the firm’s future because its stock price rose sharply during the first two days it traded on the stock market.
Some policymakers are concerned that individual investors may not have sufficient information on firms that go public through a merger with a SPAC. Under one proposal being considered by Congress, financial advisers would only be allowed to recommend investing in SPACs to wealthy investors. The SEC is also considering whether new regulations governing SPACS were needed. Testifying before Congress, SEC Chair Gary Gensler sated: “There’s real questions about who’s benefiting [from firms going public using SPACs] and [about] investor protection.”
It remains to be seen whether SPACs will retain their current position as being the leading way for firms to go public.
Sources: Dave Sebastian, “WeWork Shares Rise on First Day of Trading, Two Years After Failed IPO,” wsj.com, October 21, 2021; Peter Santilli and Amrith Ramkumar, “SPACs Are the Stock Market’s Hottest Trend. Here’s How They Work,” wsj.com, March 29, 2021; Benjamin Bain, “SPAC Marketing Heavily Curtailed in House Democrats’ Draft Bill,” bloomberg.com, October 4, 2021; and Dave Michaels, “SEC Weighs New Investor Protections for SPACs,” wsj.com, May 26, 2021.
Beginning in the 1950s, several companies pioneered in developing modern shipping containers that once arrived at docks can be lifted by cranes and directly attached to trucks or loaded on to trains for overland shipping. As economist Marc Levinson was the first to discuss in detail in his 2004 book, The Box, container shipping, by greatly reducing transportation costs, helped to make the modern global economy possible. (We discuss globalization in Economics, Chapter 9, Section 9.1 and Chapter 21, Section 21.4, and in Macroeconomics, Chapter 7, Section 7.1 and Chapter 11, Section 11.4.)
Lower transportation costs meant that small manufacturing firms and other small businesses that depended on selling in local markets faced much greater competition, including from firms located thousands of miles away. The number of dockworkers declined dramatically as the loading and unloading of cargo ships became automated. Ports such as New York City, San Francisco, and Liverpool that were not well suited for handling containers because they lacked sufficient space for the automated equipment and the warehouses, lost most of their shipping business to other ports, such as Los Angeles, Seattle, and London. Consumers in all countries benefited because lower transportation costs meant they were able to buy cheaper imported goods and had a much greater variety of goods to choose from.
In the decades since the 1950s, shipping firms have continued to exploit economies of scale in container ships. (We discuss the concept of economies of scale in Econimics and Microeconomics, Chapter 11, Section 11.6.) Today, shipping containers have been standardized at either 20 feet or 40 feet long and the largest ships can haul thousands of containers. Levinson explains why economies of scale are important in this industry:
“A vessel to carry 3,000 containers did not require twice as much steel or twice as large an engine as a vessel to carry 1,500. [Because of automation, a] larger ship did not require a larger crew, so crew wages per container were much lower. Fuel consumption did not increase proportionally with the vessel’s size.”
To take advantage of these economies of scale, the ships needed to sail fully loaded. The largest ships can sail fully loaded only on routes where shipping volumes are highest, such as between Asia and the United States or between the United States and Europe. As a result, as Levinson notes, the largest ships are “uneconomic to run on most of the world’s shipping lanes” because on most routes the costs per container are higher for the largest ships for smaller ships. (Note that even these “smaller ships” are still very large in absolute size, being able to haul 1,000 containers.)
Large U.S. retail firms, such as Walmart, Home Depot, and Target rely on imported goods from Asian countries, including China, Japan, and Vietnam. Ordinarily, they are importing goods in sufficient quantities that the goods are shipped on the largest vessels, which today have the capacity to haul 20,000 containers. But during the pandemic, a surge in demand for imported goods combined with disruptions caused by Covid outbreaks in some Asian ports and a shortage of truck drivers and some other workers in the United States, resulted in a backlog of ships waiting to disembark their cargoes at U.S. ports. The ports of Los Angeles and Long Beach in southern California were particularly affected. By October 2021, it was taking an average of 80 days for goods to be shipped across the Pacific, compared with an average of 40 days before the pandemic.
Some large U.S. firms responded to the shipping problems by chartering smaller ships that ordinarily would only make shorter voyages. According to an article in the Wall Street Journal, “the charters provide the big retailers with a way to work around bottlenecks at ports such as Los Angeles, by rerouting cargo to less congested docks such as Portland, Ore., Oakland, Calif., or the East Coast.” Unfortunately, because the smaller ships lacked the economies of scale of the larger ships, the cost the U.S. firms were paying per container were nearly twice as high. (Note that this result is similar to the cost difference between a large and a small automobile factory, which we illustrated in Economics and Microeconomics, Figure 11.6.)
Unfortunately for U.S. consumers, the higher costs U.S. retailers paid for transporting goods across the Pacific Ocean resulted in higher prices on store shelves. Shopping for presents during the 2021 holiday season turned out to be more expensive than in previous years.
Sources: Marc Levinson, The Box: How the Shipping Container Made the World Smaller and the World Economy Bigger, Second edition, Princeton, NJ: Princeton University Press, 2016; Sarah Nassauer and Costas Paris, “Biggest U.S. Retailers Charter Private Cargo Ships to Sail Around Port Delays,” wsj.com, October 10, 2021; and Melissa Repko, “How Bad Are Global Shipping Snafus? Home Depot Contracted Its Own Container Ship as a Safeguard,” cnbc.com, June 13, 2021.