Jerome Powell (photo from the Wall Street Journal)
Most economists believe that monetary policy actions, such as changes in the Fed’s pace of buying bonds or in its target for the federal funds rate, affect real GDP and employment only with a lag of several months or longer. But monetary policy actions can have a more immediate effect on the prices of financial assets like stocks and bonds.
Investors in financial markets are forward looking because the prices of financial assets are determined by investors’ expectations of the future. (We discuss this point in Economics and Microeconomics, Chapter 8, Section 8.2, Macroeconomics, Chapter 6, Section 6.2, and Money, Banking and the Financial System, Chapter 6.) For instance, stock prices depend on the future profitability of firms, so if investors come to believe that future economic growth is likely to be slower, thereby reducing firms’ profits, the investors will sell stocks causing stock prices to decline.
Similarly, holders of existing bonds will suffer losses if the interest rates on newly issued bonds are higher than the interest rates on existing bonds. Therefore, if investors come to believe that future interest rates are likely to be higher than they had previously expected them to be, they will sell bonds, thereby causing their prices to decline and the interest rates on them to rise. (Recall that the prices of bonds and the interest rates (or yields) on them move in opposite directions: If the price of a bond falls, the interest rate on the bond will increase; if the price of a bond rises, the interest rate on the bond will decrease. To review this concept, see the Appendix to Economics and Microeconomics Chapter 8, the Appendix to Macroeconomics Chapter 6, and Money, Banking, and the Financial System, Chapter 3.)
Because monetary policy actions can affect future interest rates and future levels of real GDP, investors are alert for any new information that would throw light on the Fed’s intentions. When new information appears, the result can be a rapid change in the prices of financial assets. We saw this outcome on January 5, 2022, when the Fed released the minutes of the Federal Open Market Committee meeting held on December 14 and 15, 2021. At the conclusion of the meeting, the FOMC announced that it would be reducing its purchases of long-term Treasury bonds and mortgage-backed securities. These purchases are intended to aid the expansion of real GDP and employment by keeping long-term interest rates from rising. The FOMC also announced that it intended to increase its target for the federal funds rate when “labor market conditions have reached levels consistent with the Committee’s assessments of maximum employment.”
When the minutes of this FOMC meeting were released at 2 pm on January 5, 2022, many investors realized that the Fed might increase its target for the federal funds rate in March 2022—earlier than most had expected. In this sense, the release of the FOMC minutes represented new information about future Fed policy and the markets quickly reacted. Selling of stocks caused the S&P 500 to decline by nearly 100 points (or about 2 percent) and the Nasdaq to decline by more than 500 points (or more than 3 percent). Similarly, the price of Treasury securities fell and, therefore, their interest rates rose.
Investors had concluded from the FOMC minutes that economic growth was likely to be slower during 2022 and interest rates were likely to be higher than they had previously expected. This change in investors’ expectations was quickly reflected in falling prices of stocks and bonds.
Sources: An Associated Press article on the reaction to the release of the FOMC minutes can be found HERE; the FOMC’s statement following its December 2021 meeting can be found HERE; and the minutes of the FOMC meeting can be found HERE.
When Congress established the Federal Reserve System in 1913, it intended to make the Fed independent of the rest of the federal government. (We discuss this point in the opener to Macroeconomics, Chapter 15 and to Economics, Chapter 25. We discuss the structure of the Federal Reserve System in Macroeconomics, Chapter 14, Section 14.4 and in Economics, Chapter 24, Section 24.4.) The ultimate responsibility for operating the Fed lies with the Board of Governors in Washington, DC. Members of the Board of Governors are nominated by the president and confirmed by the Senate to 14-year nonrenewable terms. Congress intentionally made the terms of Board members longer than the eight years that a president serves (if the president is reelected to a second term).
The president is still able to influence the Board of Governors in two ways:
The terms of members of the Board of Governors are staggered so that one term expires on January 31 of each even-number year. Although this approach means that it’s unlikely that a president will be able to appoint all seven members during the president’s time in office, in practice, many members do not serve their full 14-year terms. So, a president who serves two terms will typically have an opportunity to appoint more than four members of the Board.
The president nominates one member of the Board to serve a renewable four-year term as chair, subject to confirmation by the Senate.
The terms of Fed chairs end in the year after the year a president begins either the president’s first or second term. As a result, presidents are often faced with what is at times a difficult decision as to whether to reappoint a Fed chair who was first appointed by a president of the other party.
For example, after taking office in January 2009, President Barack Obama, a Democrat, faced the decision of whether to nominate Fed Chair Ben Bernanke to a second term to begin in 2010. Bernanke had originally been appointed by President George W. Bush, a Republican. Partly because the economy was still suffering the aftereffects of the financial crisis and the Great Recession, President Obama decided that it would potentially be disruptive to financial markets to replace Bernanke, so he nominated him for a second term.
After taking office in January 2017, President Donald Trump, a Republican, had to decide whether to nominate Fed Chair Janet Yellen, who had been appointed by Obama, to another term that would begin in 2018. He decided not to reappoint Yellen and instead nominated Jerome Powell, who was already serving on the Board of Governors. Although a Republican, Powell had been appointed to the Board in 2014 by Obama.
President Biden’s reasons for nominating Powell to a second term to begin in 2022 were similar to Obama’s reasons for nominating Bernanke to a second term: The U.S. economy was still recovering from the effects of the Covid-19 pandemic, including the strains the pandemic had inflicted on the financial system. He believed that replacing Powell with another nominee would have been potentially disruptive to the financial system.
There had been speculation that Biden would choose Lael Brainard, who has served on the Board of Governors since 2014 following her appointment by Obama, to succeed Powell as Fed chair. Instead, Biden appointed Brainard as vice chair of the Board. In announcing the appointments, Biden stated: “America needs steady, independent, and effective leadership at the Federal Reserve. That’s why I will nominate Jerome Powell for a second term as Chair of the Board of Governors of the Federal Reserve System and Dr. Lael Brainard to serve as Vice Chair of the Board of Governors.”
Sources: Nick Timiraos and Andrew Restuccia, “Biden Will Tap Jerome Powell for New Term as Fed Chairman,” wsj.com, November 22, 2021; and Jeff Cox and Thomas Franck, “Biden Picks Jerome Powell to Lead the Fed for a Second Term as the U.S. Battles Covid and Inflation,” cnbc.com, November 22, 2021.
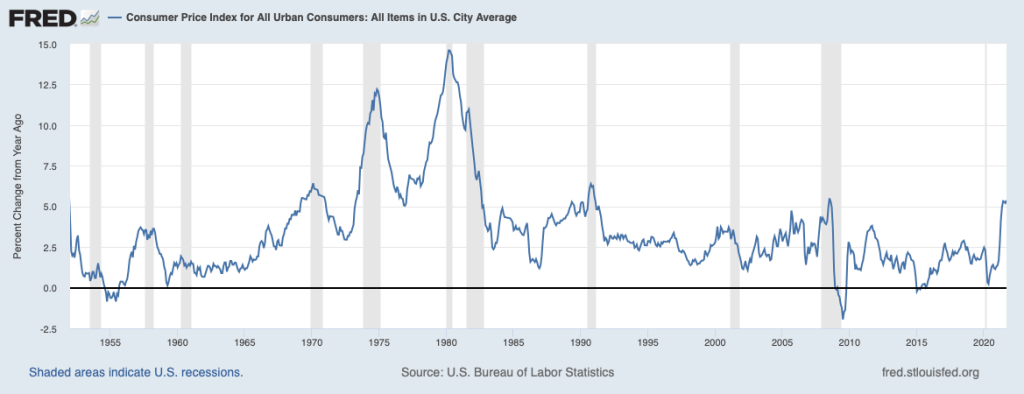
A recent publication by economists Regis Barnichon, Luiz E. Oliveira, and Adam H. Shapiro at the Federal Reserve Bank of San Francisco asks that provocative question. “The ‘60s” is a reference to the events that led to the U.S. economy experiencing more than 10 years of high inflation rates. Below is a graph similar to Chapter 15, Figure 15.1 in Macroeconomics (Economics, Chapter 25, Figure 25.1) that shows the inflation rate in the United States as measured by the percentage change in the Consumer Price Index (CPI) for each year since 1952. Economists call the years from 1968 though 1982 the “Great Inflation” because inflation was greater during that period than during any other period in the history of the United States.
As we discuss in Macroeconomics, Chapter 17, Section 17.2 (Economics, Chapter 27, Section 27.2), many economists believe that the Great Inflation began as a result of the Federal Reserve attempting to keep the unemployment rate below the natural rate of unemployment for a period of several years. As predicted by the Phillips Curve, the inflation rate increased and, as Milton Friedman and Edmund Phelps had argued would likely happen, the expected inflation rate eventually increased. The inflation was made worse during the 1970s by two supply shocks resulting from sharp increases in oil prices.
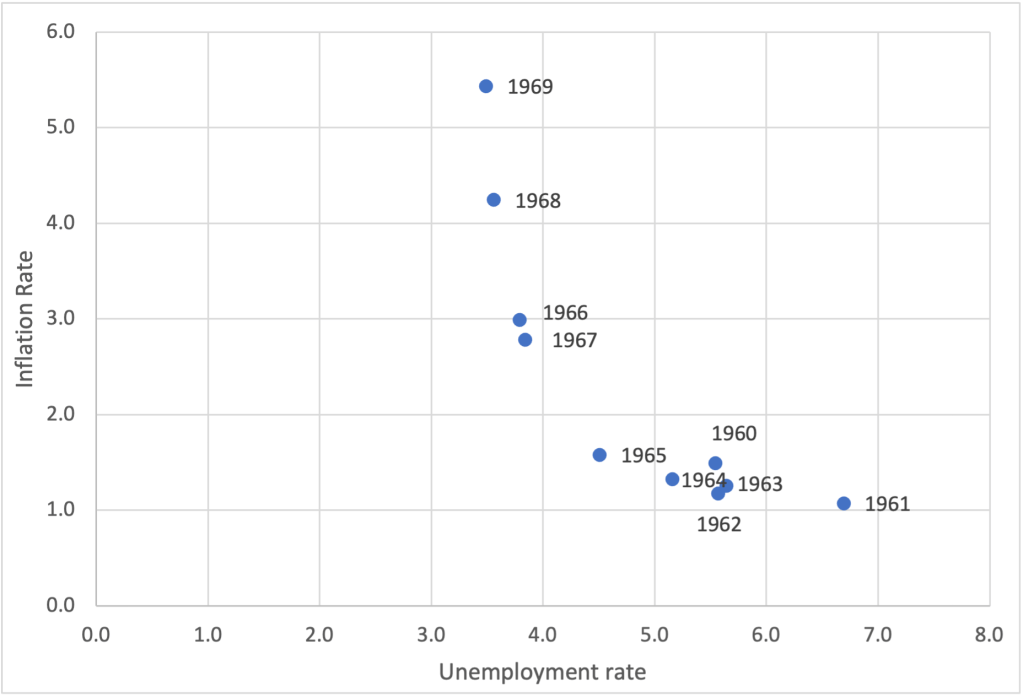
Is the United States on the edge of repeating the experience of the Great Inflation? Earlier this year, Olivier Blanchard of the Peterson Institute for International Economics wrote a paper arguing that the U.S. economy was at significant risk of experiencing a significant acceleration in inflation. His paper included a figure similar to the one below showing the combinations of inflation and unemployment during each year of the 1960s. The figure shows a substantial acceleration in inflation over the course of the decade.
Blanchard notes that:
“The history of the Phillips curve is one of shifts, largely due to the adjustment of expectations of inflation to actual inflation. True, expectations have [currently] been extremely sticky for a long time, apparently not reacting to movements in actual inflation. But, with such overheating, expectations might well deanchor. If they do, the increase in inflation could be much stronger.”
….
“If inflation were to take off, there would be two scenarios: one in which the Fed would let inflation increase, perhaps substantially, and another—more likely—in which the Fed would tighten monetary policy, perhaps again substantially. Neither of these two scenarios is ideal. In the first, inflation expectations would likely become deanchored, cancelling one of the major accomplishments of monetary policy in the last 20 years and making monetary policy more difficult to use in the future. In the second, the increase in interest rates might have to be very large, leading to problems in financial markets.”
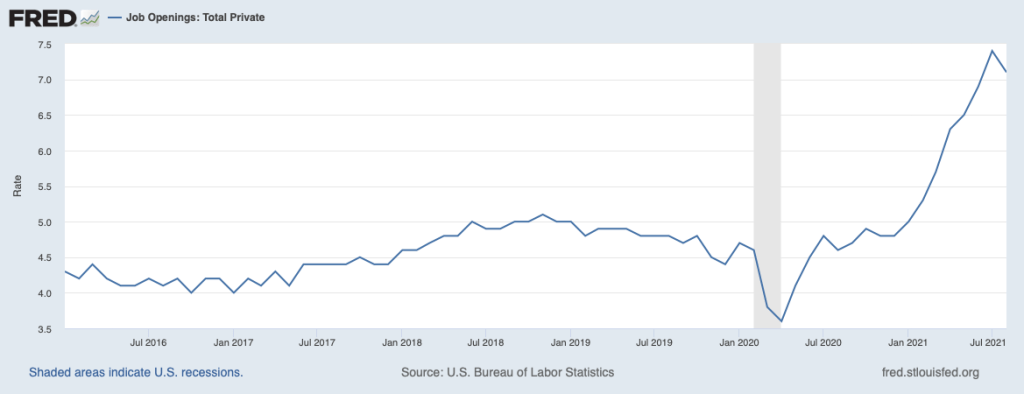
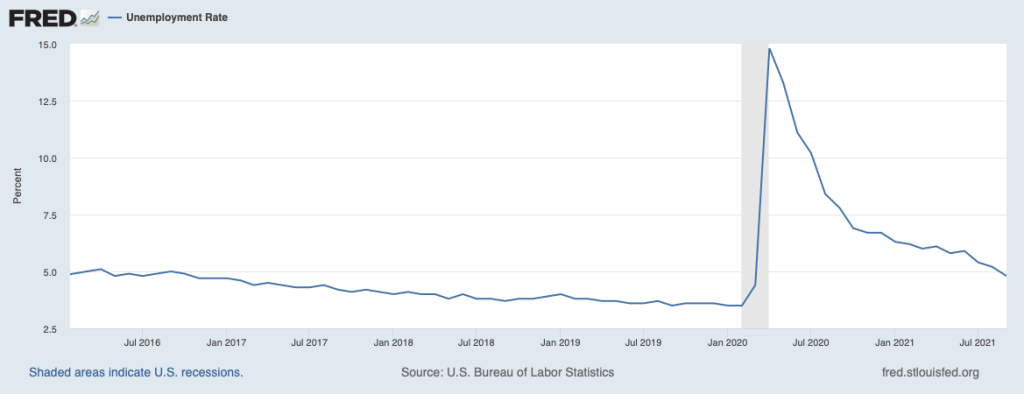
The authors of the San Francisco Fed publication are more optimistic. They begin their discussion by observing that because of the pandemic, the state of the labor market is more difficult to assess than in most years. They note that the unemployment rate of 4.8 percent in September 2021 was only slightly below the average unemployment rate over the past 30 years and well above the low unemployment rates of 2019 and early 2021. So, on the basis of the unemployment rate, policymakers at the Fed and in Congress might conclude that the inflation the U.S. economy is experiencing is not the result of overly tight labor markets such as those of the late 1960s. But the job openings rate(sometimes called the vacancy rate) is telling a different story. Job openings are positions that are both available to be filled within the next 30 days and for which firms are actively recruiting applicants from outside the firm. (According to the BLS: “The job openings rate is computed by dividing the number of job openings by the sum of employment and job openings and multiplying that quotient by 100.”)
The authors of the San Francisco Fed study note that “the vacancy rate is well above its 30-year average … and has surpassed its historic highs from the late 1960s … indicating that employers are having a difficult time filling positions. Confirming this high vacancy rate, the fraction of small businesses reporting that job openings are hard to fill is at historic highs ….” The figures below show the vacancy rate and the unemployment rate since January 2016.
The authors combine the unemployment rate and the vacancy rate into a statistic—the vacancy-to-unemployment ratio—that they demonstrate has historically done a better job of explaining movements in inflation than has the unemployment rate. They expect that expansionary fiscal policy will result in an increase in vacancy-to-unemployment ratio and, therefore, an increase in the inflation rate. But they share the view of Blanchard and many other economists that a key issue is “the stability of longer-run inflation expectations.”
We know that in the 1960s, several years of rising inflation made long-run inflation expectations unstable—in terms of the discussion in Chapter 17, the short-run Phillips curve shifted up. We don’t yet know what will happen to inflation expectations in late 2021 and in 2022, so we can’t yet tell how persistent current rates of inflation will be.
Sources: Regis Barnichon, Luiz E. Oliveira, and Adam H. Shapiro, “Is the American Rescue Plan Taking Us Back to the ’60s?,” FRBSF Economic Letter, No. 2021-27, October 18, 2021; Olivier Blanchard, “In Defense of Concerns over the $1.9 Trillion relief Plan,” piie.com, February 18, 2021; and Federal Reserve Bank of St. Louis.
In 2021, SPACs were the hottest trend on the stock market and had become the leading way for companies to go public. A public company is one with shares that trade on the stock market. Private firms make up more than 95 percent of all firms in the United States. Most will never become public firms because they will never grow large enough for investors to have sufficient information on the firms’ financial health to be willing to buy the firms’ stocks and bonds.
But some firms, particularly technology firms, grow rapidly enough that they are able to become public firms. Apple, Microsoft, Google, Uber, Facebook, Snap, and other firms have followed this path. When these firms went public, they did so using an initial public offering (IPO). (We briefly discuss IPOs in Economics and Microeconomics, Chapter 8, Section 8.2 and in Macroeconomics, Chapter 6, Section 6.2.) With an IPO, a firm uses one or more investment banks to underwrite the firm’s sales of new stocks or bonds to the public. In underwriting,investment banks typically guarantee a price for stocks or bonds to the issuing firm, sell the stocks or bonds in financial markets or directly to investors at a higher price, and keep the difference, known as the spread.
Beginning in 2020 and continuing through 2021, an increasing number of firms have used a different means of going public—merging with a SPAC. SPAC stands for special-purpose acquisition company and is a firm that holds only cash—it doesn’t sell a good or service—and only has the purpose of merging with another firm that wants to go public. Once a merger takes place, the acquired firm takes the place of the SPAC in the stock market. For instance, a SPAC named Diamond Eagle Acquisition merged with online sports betting site DraftKings in April 2020. Once the merger had been completed, DraftKings took Diamond Eagle’s place on the stock market, trading under the stock symbol DKNG. By 2021, the value of SPAC mergers had risen to being three times as much as the value of IPOs.
Some firms intending to go public prefer SPACs to traditional IPOs because they can bargain directly with the managers of the SPAC in determining the value of the firm. In addition, IPOs are closely regulated by the federal government’s Securities and Exchange Commission (SEC). In particular, the SEC monitors whether an investment bank is accurately stating the financial prospects of a firm whose IPO the bank is underwriting. The claims that SPACs make when attracting investors are less closely monitored. SPAC mergers can also be finalized more quickly than can traditional IPOs.
The experience of WeWork illustrates how some firms that have struggled to go public through an IPO have been able to do so by merging with a SPAC. Adam Neumann and Miguel McLevey founded WeWork in 2010 as a firm that would rent office space in cities, renovate the space, and then sub-lease it to other firms. In 2019, the firm prepared for an IPO that would have given the firm a total value of more than $40 billion. But doubts about the firm’s business model led to an indefinite postponement of the IPO and Neumann was forced out as CEO.
WeWork was reorganized under new CEO Sandeep Mathrani and went public in October 2021 by merging with BowX Acquisition Corporation, a SPAC. Although WeWork’s stock began trading (under stock symbol WE) at a price that put the firm’s value at about $9 billion—far below the value it expected at the time of its postponed IPO two years before—investors seemed optimistic about the firm’s future because its stock price rose sharply during the first two days it traded on the stock market.
Some policymakers are concerned that individual investors may not have sufficient information on firms that go public through a merger with a SPAC. Under one proposal being considered by Congress, financial advisers would only be allowed to recommend investing in SPACs to wealthy investors. The SEC is also considering whether new regulations governing SPACS were needed. Testifying before Congress, SEC Chair Gary Gensler sated: “There’s real questions about who’s benefiting [from firms going public using SPACs] and [about] investor protection.”
It remains to be seen whether SPACs will retain their current position as being the leading way for firms to go public.
Sources: Dave Sebastian, “WeWork Shares Rise on First Day of Trading, Two Years After Failed IPO,” wsj.com, October 21, 2021; Peter Santilli and Amrith Ramkumar, “SPACs Are the Stock Market’s Hottest Trend. Here’s How They Work,” wsj.com, March 29, 2021; Benjamin Bain, “SPAC Marketing Heavily Curtailed in House Democrats’ Draft Bill,” bloomberg.com, October 4, 2021; and Dave Michaels, “SEC Weighs New Investor Protections for SPACs,” wsj.com, May 26, 2021.
As we discuss in the chapter, initially, bitcoin was thought of as a way to buy and sell goods and services. Some stores accepted bitcoin and allowed customers to make payment by scanning a bar code with a phone. Some websites offered merchants a way to process purchases made with bitcoins in a manner similar to the way merchants process credit card payments.
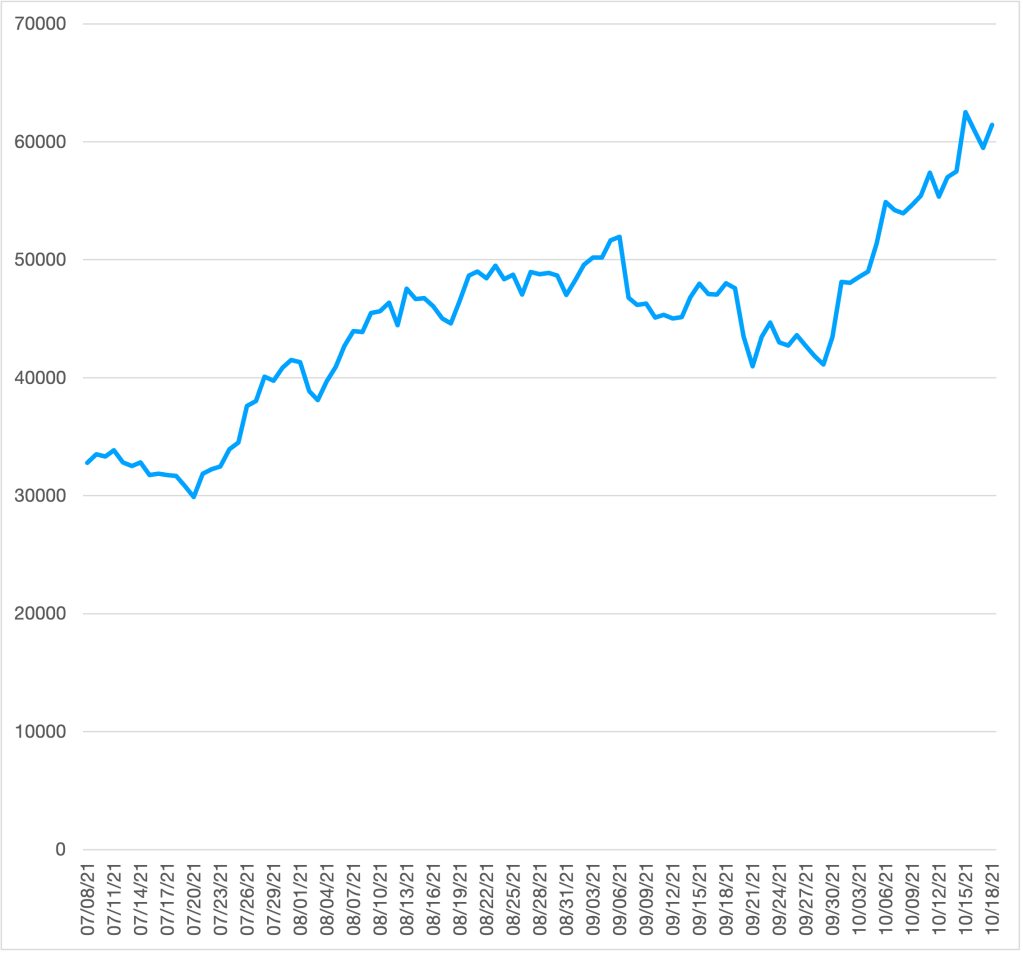
In practice, though, swings in the value of bitcoin have been much too large to make it a good substitute for cash, checks, or credit cards in everyday transactions. For instance, at the beginning of 2015, one bitcoin was worth about $300. Over the following five years, the price of bitcoin rose as high at $17,000 before falling to about $8,000 at the beginning of 2020. During 2021, the volatility of bitcoin prices increased, rising as high as $62,000 in April and falling as low as $30,000 in July before rising back above $60,000 in October. (The following chart shows movements in the price of bitcoin from early July to mid-October 2021; the vertical axis shows the price as dollars per bitcoin.)
Some economists have suggested that rather being a medium of exchange, like dollar bills, bitcoin has become a speculative asset, like gold. Bitcoin shares with gold the characteristic that ultimately its total supplied is limited. The supply of Bitcoin can’t increase beyond 21 million, a limit that is expected to be reached in 2030. The gold stock slowly increases as mines produce more gold, although the output of mines is small compared with the existing stock of gold. Some investors and speculators are reassured that, in contrast to the assets in M1 and M2 that can increase as much as the Fed chooses, gold and bitcoin have limits on how much they can increase.
Will Bitcoin Be a Good Hedge Against Inflation? Can It Be Useful in Diversifying a Portfolio?
Some investors and speculators believe that the limited quantities of gold and bitcoin available make them good hedges against inflation—that is, they believe that the prices of gold and bitcoin will reliably increase during periods of inflation. In fact, though, gold has proven to be a poor hedge against inflation because in the long run the price of gold has not reliably increased faster than the inflation rate. There is no good economic reason to expect that over the long run bitcoin would be a good inflation hedge either.
From a broader perspective than as just an inflation hedge, some economists argue that gold has a role to play in an investor’s portfolio—which is the collection of assets, such as stocks and bonds, that an investor owns. Investors can reduce the financial risk they face through diversification, or spreading their wealth among different assets. For instance, an investor who only holds Apple stock in her portfolio is subject to more risk than an investor with the same dollar amount invested in a portfolio that holds the stocks of multiple firms as well as non-stock investments. An investor obtains the benefits of diversification best by adding assets to her portfolio that are not well correlated with the assets she already owns—that is the prices of the assets she adds to her portfolio don’t typically move in the same direction as the prices of the assets she already owns.
For instance, during a typical recession sales of consumer staples, like baby diapers and laundry detergent, hold up well, while sales of consumers durables, like automobiles, usually decline significantly. So adding shares of stock in Proctor & Gamble to a portfolio that already has many shares of General Motors achieves diversification and reduces financial risk because movements in the price of shares of Proctor & Gamble are likely not to be highly correlated with movements in the price of shares of General Motors.
Studies have shown that during some periods movements in gold prices are not correlated with movements in prices of stocks or bonds. In other words, gold prices may rise during a period when stock prices are declining. As a result, an investor may want to add gold to her portfolio to diversify it. To this point, bitcoin hasn’t been around long enough to draw firm conclusions about whether adding bitcoin to a portfolio provides significant diversification, although some investors believes that it does.
Finance professionals are divided in their opinions on whether bitcoin is a good substitute for gold in a financial portfolio. In an interview, billionaire investor Ray Dalio, founder of Bridgewater Associates, the world’s hedge fund, noted that while he believes that bitcoin may serve as a hedge against inflation, but if he could only hold gold or bitcoin, “I would choose gold.” His preference for gold is due in part to his belief that the federal government may increase regulation of bitcoin and that regulators might eventually even decide to ban it. A businessinsider.com survey of 10 financial experts found them divided with five preferring gold as an investment and five preferring bitcoin.
Sources: Jade Scipioni, “Bitcoin vs. Gold: Here’s What Billionaire Ray Dalio Thinks,” cnbc.com, August 4, 2021; and Isabelle Lee and Will Daniel, “Bitcoin vs. Gold: 10 Experts Told Us Which Asset They’d Rather Hold for the Next 10 Years, and Why,” businessinsider.com, February 20, 2021.
Authors Glenn Hubbard and Tony O’Brien discuss the economic impact of the recent infrastructure bill and what role fiscal policy plays in determining shovel-ready projects. Also, they explore the vast impact of the economy-wide supply-chain issues and the challenges companies face. Until the pandemic, we had a very efficient supply chain but now we’re seeing companies employ the “just-in-case” inventory method vs. “just-in-time”!
It’s customary for textbook authors to note that “much has happened in the economy” since the last edition of their book appeared. To say that much has happened since we prepared our last edition in 2019 would be a major understatement. Never in the lifetimes of today’s students and instructors have events like those of 2020 and 2021 occurred. The U.S. and world economies had experienced nothing like the Covid-19 pandemic since the influenza pandemic of 1918. In the spring of 2020, the U.S. economy suffered an unprecedented decline in the supply of goods and services as a majority of businesses in the country shut down to reduce spread of the virus. Many businesses remained closed or operated at greatly reduced capacity well into 2021. Most schools, including most colleges, switched to remote learning, which disrupted the lives of many students and their parents.
During the worst of the pandemic, total spending in the economy declined as the unemployment rate soared to levels not seen since the Great Depression of the 1930s. Reduced spending and closed businesses resulted in by far the largest decline in total production in such a short period in the history of the U.S. economy. Congress, the Trump and Biden administrations, and the Federal Reserve responded with fiscal and monetary policies that were also unprecedented.
Our updated Eighth Edition covers all of these developments as well as the policy debates they initiated. As with previous editions, we rely on extensive digital resources, including: author-created application videos and audio recordings of the chapter openers and Apply the Concept features; figure animation videos; interactive real-time data graphs animations; and Solved Problem whiteboard videos.
Glenn and Tony discuss the updated edition in this video:
Sample chapters will be available by October 15.
The full Macroeconomics text will available in early to mid December.
The full Microeconomics text will be available in mid to late December.
If you would like to view the sample chapters or are considering adopting the updated Eighth Edition for the spring semester, please contact your local Pearson representative. You can use this LINK to find and contact your representative.
Authors Glenn Hubbard and Tony O’Brien discuss the recent jobs report falling short of expectations. They also discuss the comments of Fed Chairman Powell’s comments at the Federal Reserve’s recent Jackson Hole conference. They also get to some of the recommendations of a Brookings Task Force, co-chaired by Glenn Hubbard, on ways to address financial stability. Use the links below to see more information about these timely topics: Powell’s Jackson Hole speech:
Join authors Glenn Hubbard and Tony O’Brien as they return for a new academic year! The issues have evolved but the importance of these issues has not waned. We discuss the impact of closures related to the delta variant has on the economy. The discussion extends to the active fiscal and monetary policy that has reintroduced inflation as a topic facing our economy. Many students have little or no experience with inflation so it is a learning opportunity. Check back regularly where Glenn & Tony will continue to wrestle with these important economic concepts and relate them to the classroom!
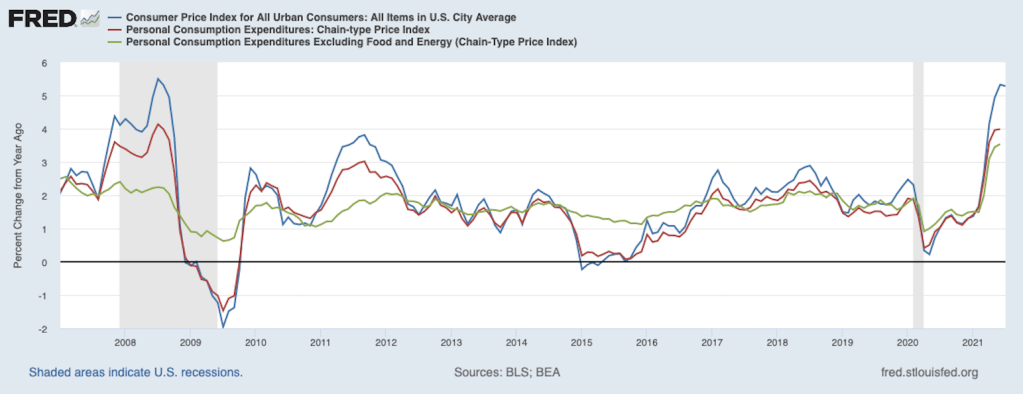
The U.S. inflation rate has accelerated. As the following figure shows, in mid-2021, inflation, measured as the percentage change in the CPI from the same month in the previous year (the blue line), rose above 5 percent for the first time since the summer of 2008.
As we discuss in an Apply the Concept in Chapter 25, Section 25.5 (Chapter 15, Section 15.5 of Macroeconomics), the Fed prefers to measure inflation using the personal consumption expenditures (PCE) price index. The PCE price index is a measure of the price level similar to the GDP deflator, except it includes only the prices of goods and services from the consumption category of GDP. Because the PCE price index includes more goods and services than the CPI, it is a broader measure of inflation. As the red line in the figure shows, inflation as measured by the PCE price index is generally lower than inflation measured by the CPI. The difference is particularly large during periods in which CPI inflation is especially high, as it was during 2008, 2011, and 2021.
Prices of food and energy are particularly volatile, so the measure of inflation the Fed focuses on most closely is the PCE price index, excluding food and energy prices (the green line in figure). The figure shows that this measure of inflation is more stable than either of the other two measures. For instance, during June 2021, measured by the CPI, inflation was 5.3 percent, but was 3.5 percent when measured by the PCE, excluding food and energy.
In the summer of 2021, even inflation measured by the PCE, excluding food and energy, is running well above the Fed’s long-run target rate of 2 percent. Why is inflation increasing? Most economists and policymakers believe that two sets of factors are responsible:
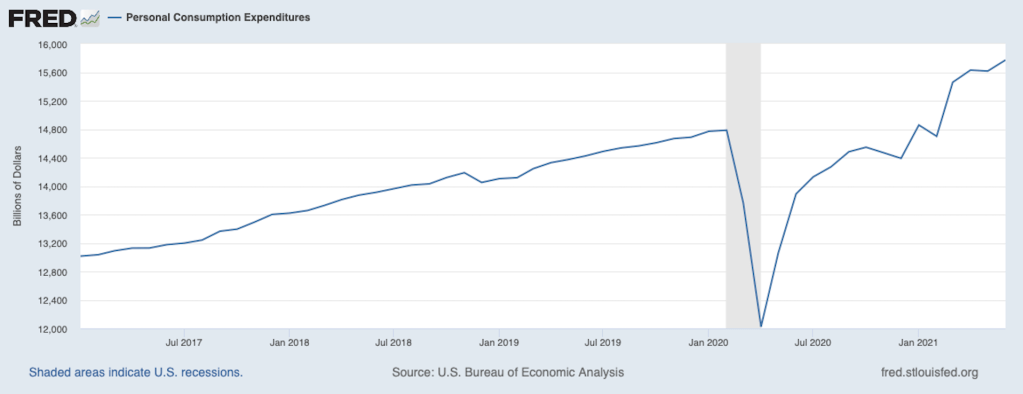
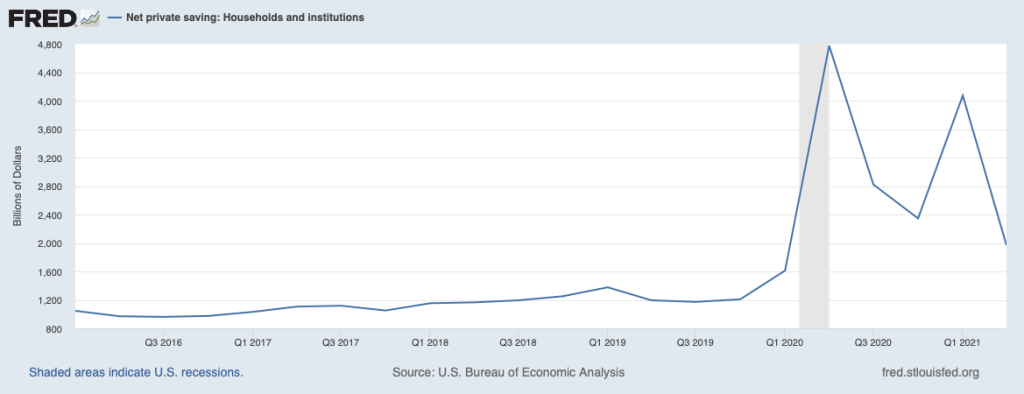
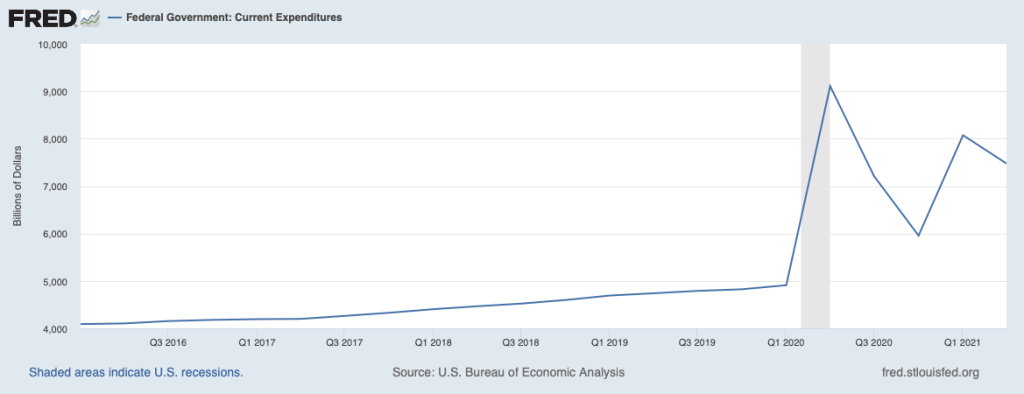
Increases in aggregate demand. Consumption spending (see the first figure below) has increased as the economy has reopened and people have returned to eating in restaurants, going to the movies, working out in gyms, and spending at other businesses that were closed or operating at reduced capacity. Households have been able to sharply increase their spending because household saving (see the second figure below) soared during the pandemic in response to payments from the federal government, including supplemental unemployment insurance payments and checks sent directly to most households. The increase in federal government expenditures that helped fuel the increase in aggregate demand is shown in the third figure below.
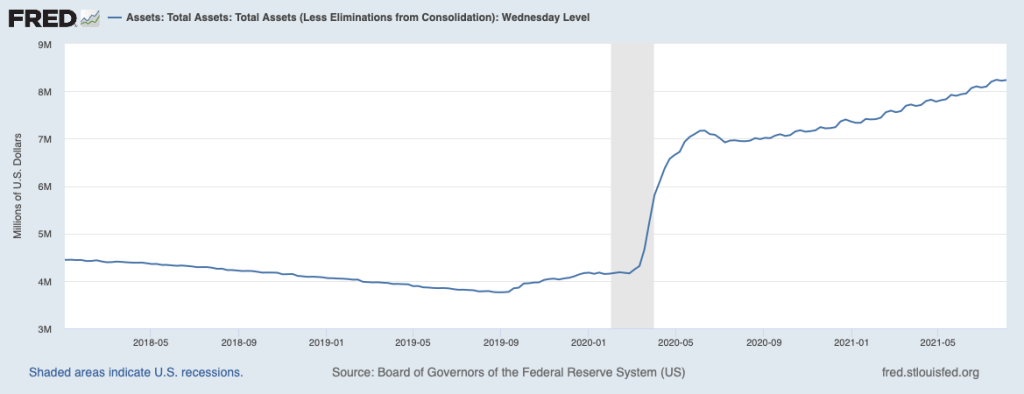
Fed policy has also been strongly expansionary, with the target for the federal funds kept near zero and the Fed continuing its substantial purchases of Treasury notes and mortgage-backed securities. The continuing expansion of the Fed’s balance sheet through the summer of 2021 is shown in the last of the figures below. The Fed’s asset purchases have help keep interest rates low and provided banks with ample funds to loan to households and firms.
2. Reductions in aggregate supply. The pandemic disrupted global supply chains, reducing the goods available to consumers. In the summer of 2021, not all of these supply chain issues had been resolved. In particular, a shortage of computer chips had reduced output of motor vehicles. New cars, trucks, SUVs, and minivans were often selling above their sticker prices. High prices for new vehicles led many consumers to increase their demand for used vehicles, driving up their prices. Between July 2020 and July 2021, prices of new vehicles rose 6.4 percent and prices for used vehicles rose an extraordinary 41.7 percent.
Supply issues also exist in some service industries, such as restaurants and hotels, that have had difficulty hiring enough workers to fully reopen.
Economists and policymakers differ as to whether high inflation rates are transitory or whether the U.S. economy might be entering a prolonged period of higher inflation. Most Federal Reserve policymakers argue that the higher inflation rates in mid-2021 are transitory. For instance, in a statement following its July 28, 2021 meeting, the Federal Open Market Committee noted that: “Inflation has risen, largely reflecting transitory factors.” Although the statement also noted that inflation is “on track to moderately exceed 2 percent for some time.”
In a speech at the end of July, Fed Governor Lael Brainard expanded on the Fed’s reasoning:
“Recent high inflation readings reflect supply–demand mismatches in a handful of sectors that are likely to prove transitory…. I am attentive to the risk that inflation pressures could broaden or prove persistent, perhaps as a result of wage pressures, persistent increases in rent, or businesses passing on a larger fraction of cost increases rather than reducing markups, as in recent recoveries. I am particularly attentive to any signs that currently high inflation readings are pushing longer-term inflation expectations above our 2 percent objective.”
“Currently, I do not see such signs. Most measures of survey- and market-based expectations suggest that the current high inflation pressures are transitory, and underlying trend inflation remains near its pre-COVID trend…. Many of the forces currently leading to outsized gains in prices are likely to dissipate by this time next year. Current tailwinds from fiscal support and pent-up consumption are likely to shift to headwinds, and some of the outsized price increases associated with acute supply bottlenecks may ease or partially reverse as those bottlenecks are resolved.”
Brainard’s remarks highlight a point that we make in Chapter 27, Section 27.1 (Chapter 17, Section 17.1 of Macroeconomics): The expectations of households and firms of future inflation play an important part in determining current inflation. Inflation can rise above and fall below the expected inflation rate in response to changes in the labor market—which affect the wages firms pay and, therefore, the firms’ costs—as well as in response to fluctuations in aggregate supply resulting from positive or negative supply shocks—such as the pandemic’s negative effects on aggregate supply. Fed Chair Jerome Powell has argued that with households and firms’ expectations still well-anchored at around 2 percent, inflation was unlikely to remain above that level in the long run.
Some economists are less convinced that households and firms will continue to expect 2 percent inflation if they experience higher inflation rates through the end of 2021. The Wall Street Journal’s editorial board summed up this view: “One risk for the Fed is that more months of these price increases will become what consumers and businesses come to expect. To use the Fed jargon, prices would no longer be ‘well-anchored.’ That may be happening.”
As we discuss in Chapter 27, Sections 27.2 and 27.3 (Macroeconomics, Chapter 17, Sections 17.2 and 17.3), during the late 1960s and early 1970s, higher rates of inflation eventually increased households and firms’ expectations of the inflation rate, leading to an acceleration of inflation that was difficult for the Fed to reverse.
Earlier this year, Olivier Blanchard of the Peterson Institute for International Economics, formerly a professor of economics at MIT and director of research at the International Monetary Fund, raised the possibility that overly expansionary monetary and fiscal policies might result in the Fed facing conditions similar to those in the 1970s. The Fed would then be forced to choose between two undesirable policies:
“If inflation were to take off, there would be two scenarios: one in which the Fed would let inflation increase, perhaps substantially, and another—more likely—in which the Fed would tighten monetary policy, perhaps again substantially. Neither of these two scenarios is ideal. In the first, inflation expectations would likely become deanchored, cancelling one of the major accomplishments of monetary policy in the last 20 years and making monetary policy more difficult to use in the future. In the second, the increase in interest rates might have to be very large, leading to problems in financial markets. I would rather not go there.”
In a recent interview, Lawrence Summers of Harvard University, who served as secretary of the Treasury in the Clinton administration, made similar points:
“We have inflation that since the beginning of the year has been running at a 5 percent annual rate. …. Starting at high inflation, we’ve got an economy that’s going to grow at extremely high rates for the next quarter or two. … I think we’re going to find ourselves with a new normal of inflation above 3 percent. Then the Fed is either going to have to be inconsistent with all the promises and commitments it’s made [to maintain a target inflation rate of 2 percent] or it’s going to have to attempt the task of slowing down the economy, which is rarely a controlled process.”
Clearly the pandemic and the resulting policy responses have left the Fed in a challenging situation.
Sources: Federal Reserve Open Market Committee, “Federal Reserve Press Release,” federalreserve.gov, July 28, 2021; Lael Brainard, “Assessing Progress as the Economy Moves from Reopening to Recovery,” speech at “Rebuilding the Post-Pandemic Economy” 2021 Annual Meeting of the Aspen Economic Strategy Group, Aspen, Colorado, federalreserve.gov, July 30, 2021; Wall Street Journal editorial board, “Powell Gets His Inflation,” Wall Street Journal, July 13, 2021; Olivier Blanchard, “In Defense of Concerns over the $1.9 Trillion Relief Plan,” piie.com, February 21, 2012; “Former Treasury Secretary on Consumer Prices, U.S. Role in Global Pandemic, Efforts,” wbur.org, August 22, 2021; and Federal Reserve Bank of St. Louis, https://fred.stlouisfed.org.