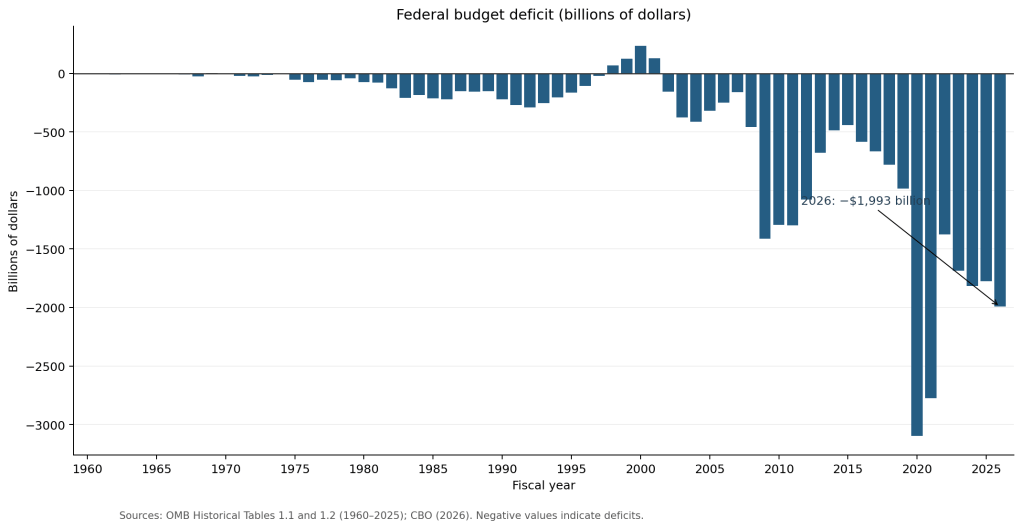
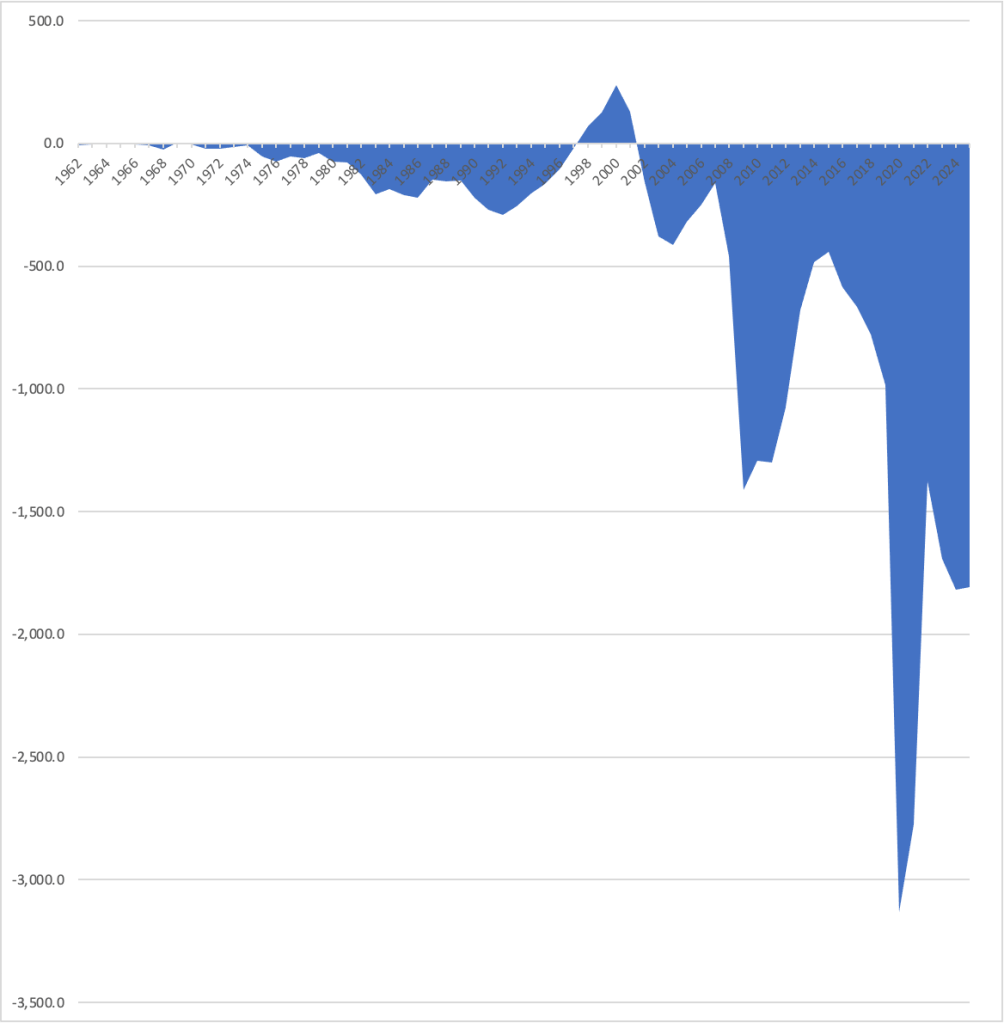
The federal government’s fiscal year runs from October 1 to September 30. The Congressional Budget Office (CBO) has released its estimate of the deficit for the 2026 fiscal year, which ended September 30, 2026. The deficit increased to $1,993 billion in 2026 from $1,775 billion in 2025. As the following figure shows, in the context of the period since 1960, the budget deficit in 2026 remains very large, particularly at a time when the U.S. economy is at or very close to full employment. The budget deficit in 2026 is well below the record deficit of $3,096 billion in 2020.
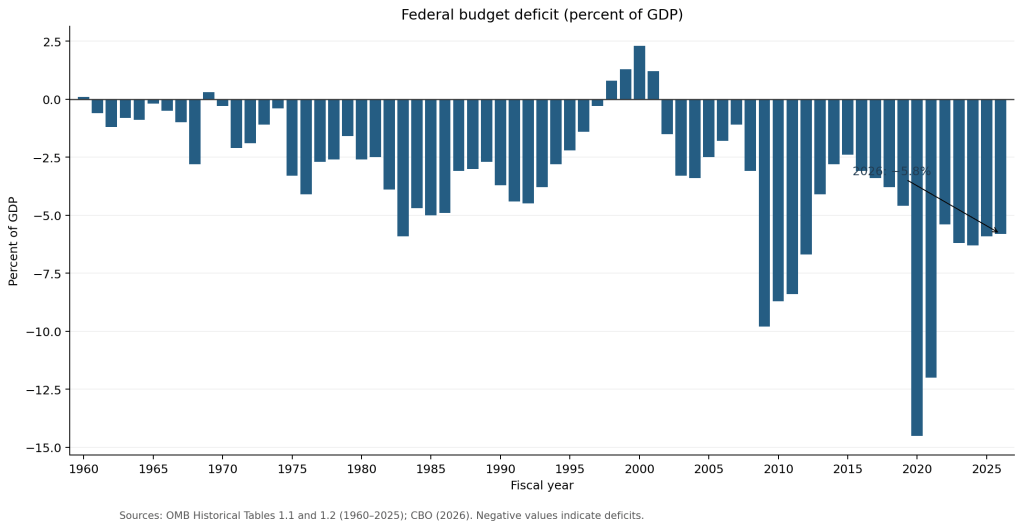
Economists typically focus more on the size of the budget deficit relative to the size of the economy, as measured by GDP. The following figure shows the federal budget deficit as a percentage of GDP was largest during and after the Great Recession of 2007–2009, and in 2020–2021, during and immediately after the Covid recession. In both those periods, federal tax revenues declined as production and employment fell. In addition, Congress passed legislation increasing government purchases and transfer payments. Although during the past few years the budget deficit as a percentage of GDP has declined from a high of 14.5 percent in 2020 (which was the largest deficit since World War II ended in 1945), it still remains very high for a period of close to full employment.
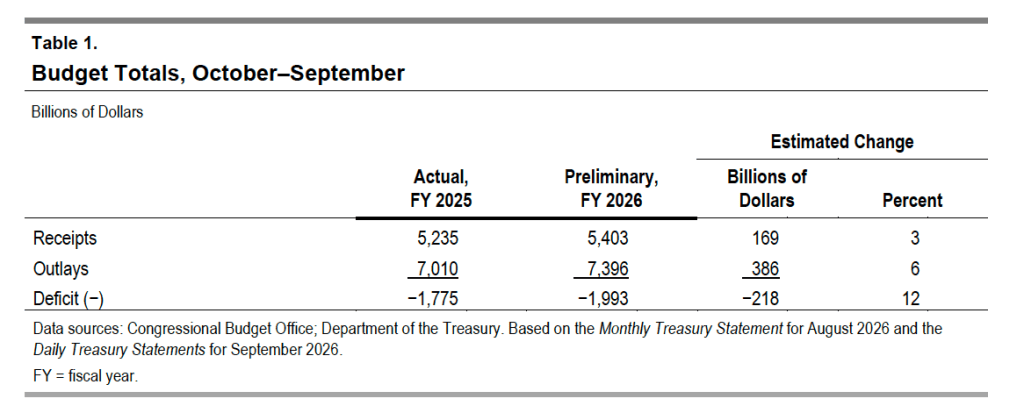
The following table from the CBO report shows that in 2026 federal receipts increased less than federal outlays, leading to a larger budget deficit.
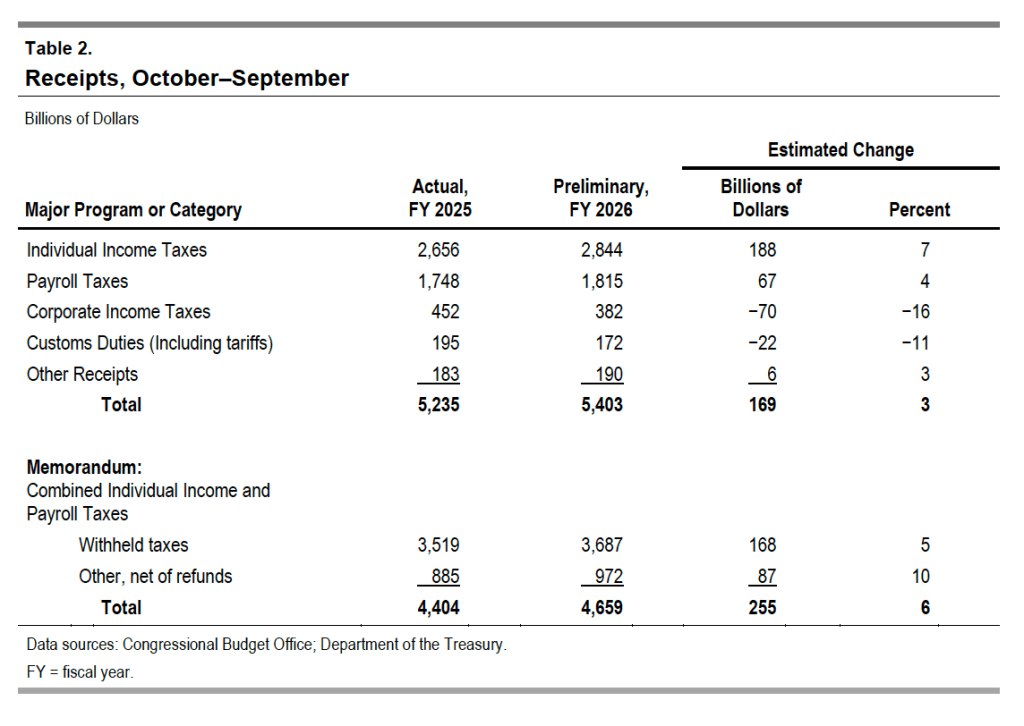
The next table shows the changes in the major categories of federal receipts. Individual income and payroll taxes—which fund the Social Security and Medicare programs, as well as the federal government’s contributions to state unemployment insurance plans—both increased, while corporate income tax receipts fell. Customs duties declined as the federal government refunded tariffs collected under higher tariff rates imposed by the Trump administration beginning in April 2025. The Supreme Court ruled in February 2026 that some of the tariff increases were not authorized by federal law.
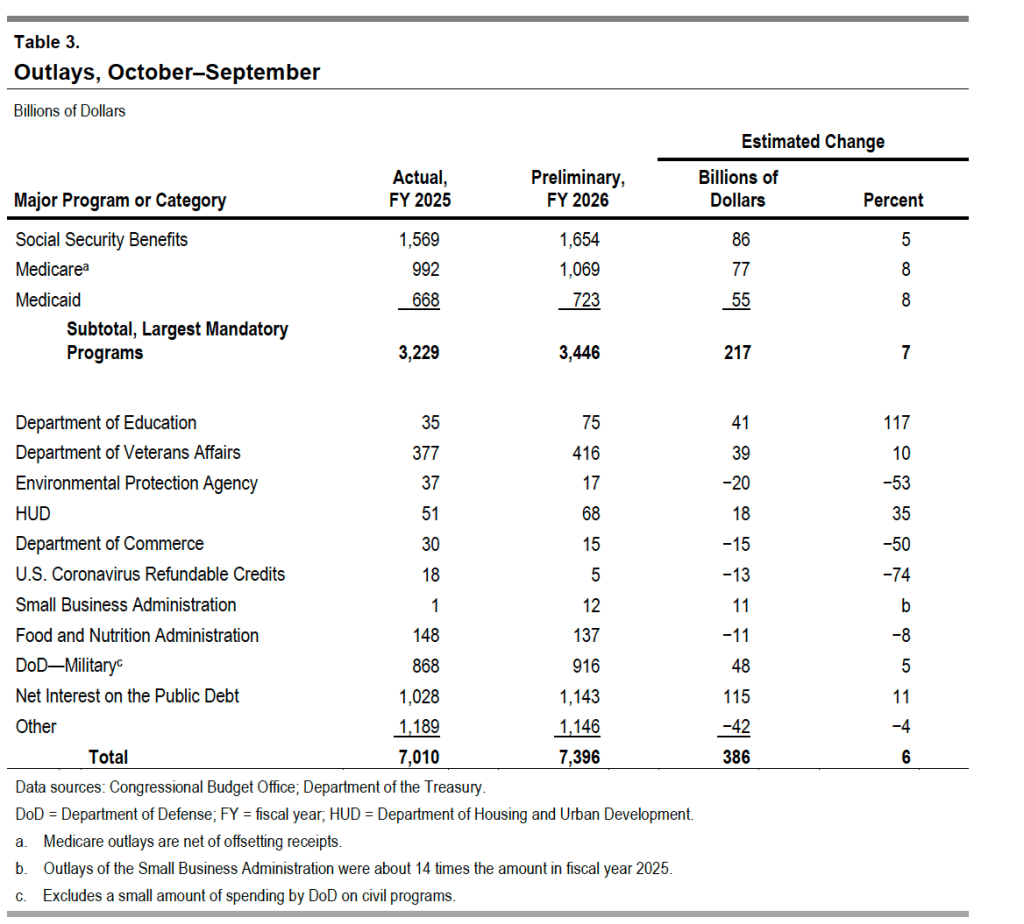
The next table shows the changes in the major categories of federal outlays. Spending on the Social Security, Medicare (health insurance for older people), and Medicaid (health insurance for lower-income people) programs continue to steadily increase. Spending on Medicare is now more than $150 billion greater than spending on defense. Interest on the public debt continues to increase as the debt grows and interest rates remain well above their pre-2021 levels.
In Macroeconomics, Chapter 16 (Economics, Chapter 26), we discuss the problems facing the Social Security system. In this opinion column, which first appeared on thewebsite of theEconomist, Glenn discusses a new approach to discovering the views of the public on possible reforms to the system.
America Needs a Citizens’ Assembly to Reform Social Security
Of the various fiscal challenges faced by America, the one the public feels most keenly is the looming crisis in Social Security. It also presents an opportunity for a bold reform process outside the polarised and dysfunctional electoral process, built around consulting a sample of voters directly in a citizens’ assembly. This would have the twin benefits of bypassing both voters’ mistrust of politicians and politicians’ incomplete understanding of voters’ attitudes towards reform.
Voters are clearly ready for reform. Recent polling of swing-state voters by the Peterson Foundation, an organisation launched to promote fiscal responsibility, revealed broad opposition to inaction and support for reforms including raising the earnings cap subject to the payroll tax and capping Social Security benefits for better-off households. Only 17% of voters said they were likely to support a candidate in the upcoming midterms who promised not to touch the current system.
Social Security pays retirement benefits to 62m Americans and disability benefits to another 8m. But the 2026 Social Security Trustees Report (sstr) predicts that the system’s trust funds will be exhausted in 2032, and if no action is taken by Congress, benefits will need to be cut across the board by 22% at that time.
Elected officials have responded in a now-familiar way, with a proposal for a 13-member commission of members of Congress and experts. Historically, a commission held promise: one assembled in 1981 and commonly known as the Greenspan Commission after its chairman, Alan Greenspan, offered a sensible roadmap for gradual reforms in 1983. Today, such an approach, however well intentioned, is likely to fail, given how out-of-balance the system is. According to the sstr, it faces an actuarial deficit of 4.4% of payroll annually for the next 75 years. Tackling that via a commission would have been extremely difficult in the 1980s. Doing so today, with public trust in government and experts a lot lower, looks impossible. According to the Pew Research Centre, just 17% of Americans trust the federal government to do “what is right” always or most of the time, down from around 40% in the early 1980s.
America needs to experiment more boldly this time by entrusting the big decisions to voters, via a citizens’ assembly tasked with presenting clear options to elected officials. Social Security reform offers a logical use case for such an approach because the areas where change is needed are clearly delineated: retirement age, benefit formulas and the level and structure of taxation. And it can give insight to politicians about voters’ real views about the thorny economic and political trade-offs that will need to be made.
Citizens’ assemblies date back to ancient Athens as a way to inform democracy. In the modern era they have been used in several countries, including Belgium, France and Ireland, to develop policy. In Ireland, for example, recent citizens’ assemblies illustrated to politicians that attitudes towards abortion and same-sex marriage had changed more than legislators had realised.
A citizens’ assembly can help to break through policy gridlock by allowing ideas to be developed and debated in a higher-trust environment than a commission drawn from politicians and experts in whom the public has declining faith. Moreover, the ideas emerging from an assembly can sometimes reveal the “Overton window”—the range of reforms that the public can live with at that particular time—better than elected leaders can alone, as seen in the Irish case.
Three steps are critical to the success of any citizens’ assembly. The first concerns its composition. Its members, typically 50-100, should be chosen by lot, as with candidates for a jury. It should be an electorate in miniature, representative of the nation’s social strata and demography. Towards this end, sampling should be random to avoid simply selecting volunteers with particular upfront points of view. Those selected should be compensated for their time and expenses. Structured in this way, the citizens’ assembly can channel mistrust of politicians towards a reclaimed populism of actual voters’ input, not slogans.
Second, per the advice of William McChesney Martin, a former chair of the Federal Reserve, experts should be on tap, not on top. In contrast to the typical commission, experts’ role would be to provide information, not to suggest prescriptions. That would allow an assembly to develop reform options that reveal genuine voter sentiment, while neutralising populist mistrust of experts.
Third, politicians and their existing institutions need to support the work of the assembly. Congress should signal strongly that it will give serious consideration to proposals coming out of an assembly—and commit to an up-or-down vote on them, as with the process for military-base closures in 1988. Elected officials should not need reminding about the large benefit reductions that will kick in as a result of a failure to act by 2032.
Selection, expert input and politicians’ commitment map well into Social Security reform. Over multiple sessions (the Irish deliberation on abortion unfolded over several weekends in a six-month period) the assembly would agree upon objectives and principles, a menu of reform options and a recommendation for formal consideration by Congress. Outside experts would provide background information on design choices (say, refining the current system or moving, for example, to a system with a flat benefit for all) and the budget and individual tax-and-benefit consequences of options (say, changes in the retirement age, payroll tax, and benefit level and structure). With this input, the assembly would evaluate options with both principles and political feasibility in mind.
Such an assembly offers an opportunity for meaningful action before the 2032 deadline. Were it successful, that would also provide momentum in related areas, such as the need for budget consolidation and policies towards artificial intelligence.
Social Security reform is stuck in deep political mud. A citizens’ assembly might just be the way to free it. It’s surely worth a tr
The federal government’s fiscal year runs from October 1 to September 30. Today (October 8), the Congressional Budget Office (CBO) released its estimate of the deficit for the fiscal year ending September 30, 2025. The deficit fell slightly from $1,817 billion in 2024 to $1,809 in 2025. As the following figure shows, the budget deficit in 2025 remains very large, particularly at a time when the U.S. economy is at or very close to full employment, although well below the record deficit of $3,133 billion in 2020.
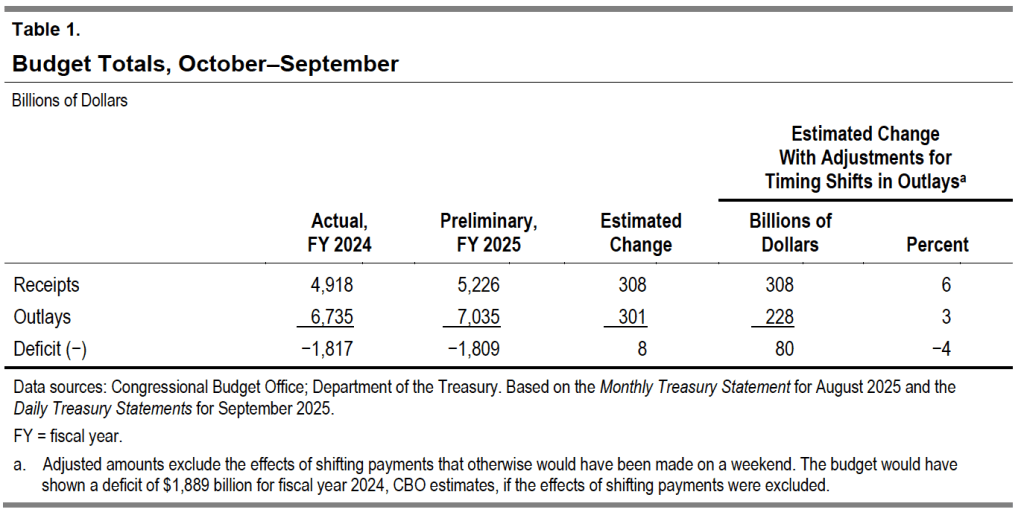
The following table from the CBO report shows that in 2025 federal receipts increased slightly more than federal outlays, leading to a slightly smaller deficit.
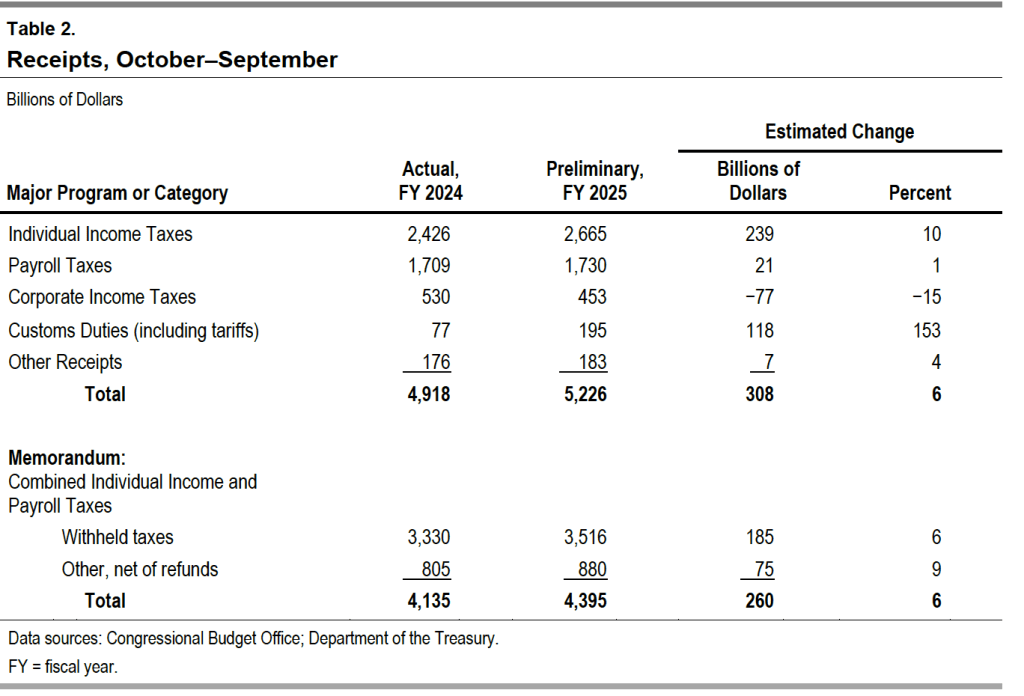
The next table shows the changes in the major categories of federal receipts. Individual income and payroll taxes—which fund the Social Security and Medicare programs, as well as the federal government’s contributions to state unemployment insurance plans—both increased, while corporate income tax receipts fell. The biggest change was in custom duties, which more than doubled following the Trump administration’s sharp increase in tariff rates beginning on April 2.
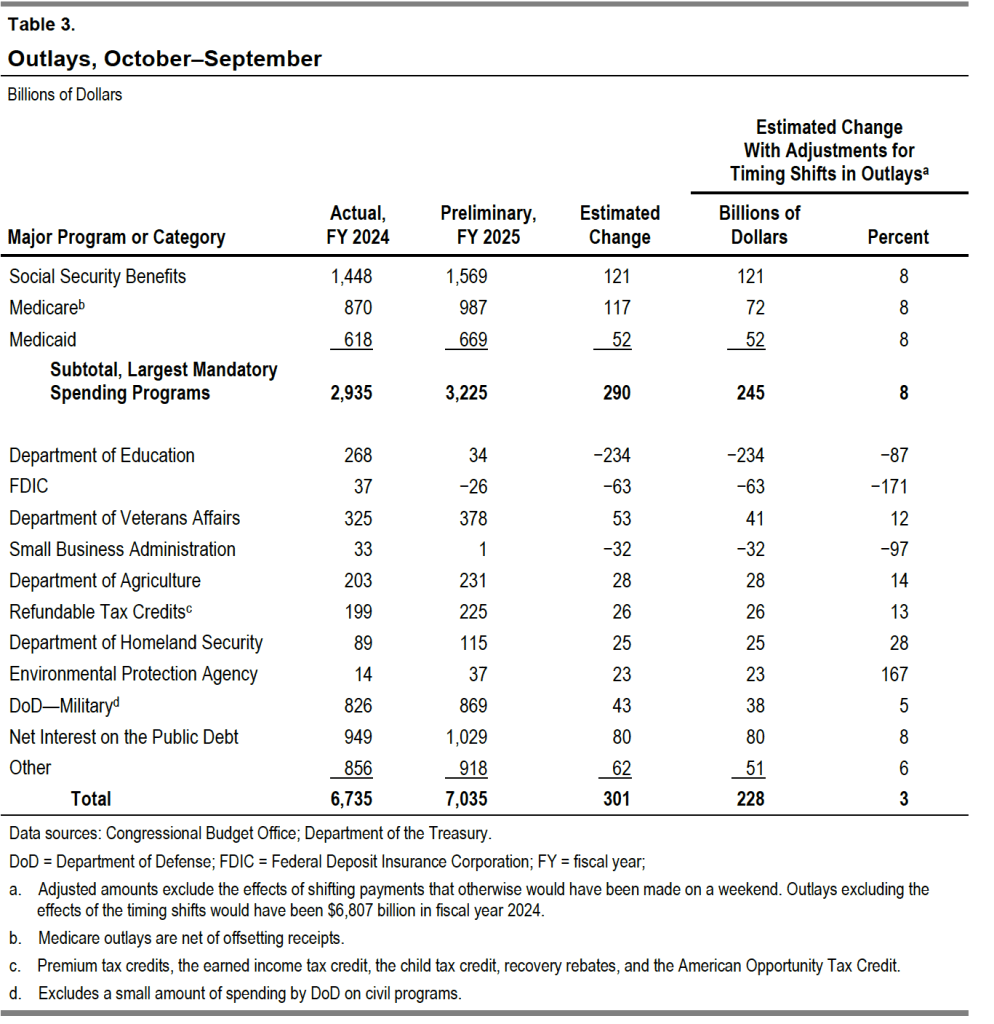
The next table shows the changes in the major categories of federal outlays. Spending on the Social Security, Medicare (health insurance for older people), and Medicaid (health insurance for lower-income people) programs continue to rapidly increase. Spending on Medicare is now more than $100 billion greater than spending on defense. Interest on the public debt continues to increase as the debt increases and interest rates remain well above their pre-2021 levels.
In June, the U.S. Census Bureau released its population estimates for 2024. Included was the following graphic showing the change in the U.S. population pyramid from 2004 to 2024. As the graphic shows, people 65 years and older have increased as a fraction of the total population, while children have decreased as a fraction of the total population. (The Census considers everyone 17 and younger to be a child.) Between 2004 and 2024, people 65 and older increased from 12.4 percent of the population to 18.0 percent. People younger than 18 fell from 25.0 percent of the population in 2004 to 21.5 percent in 2024.
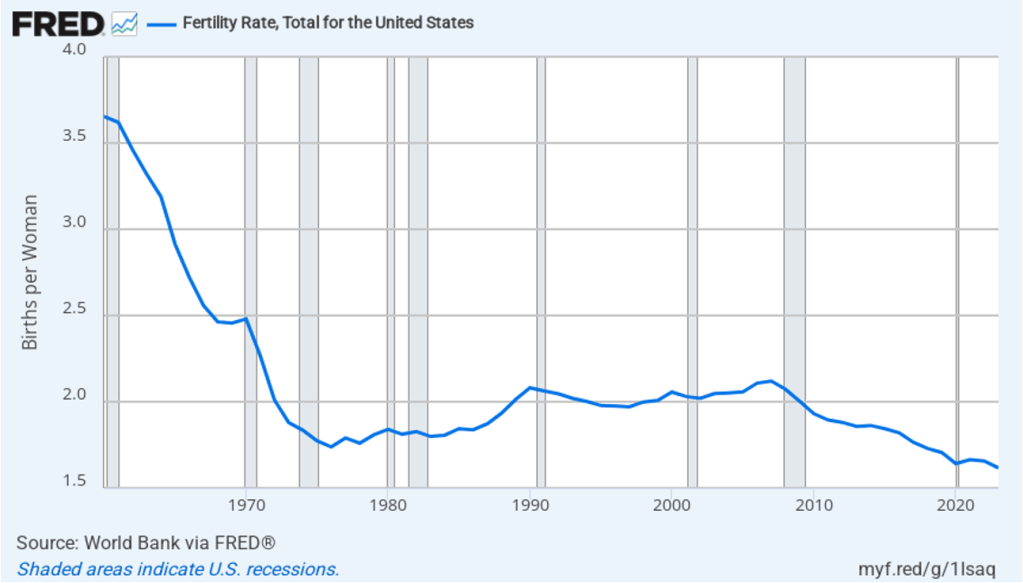
The aging of the U.S. population reflects falling birth rates. Demographers and economists typically measure birth rates as the total fertility rate (TFR), which is defined by the World Bank as: “The number of children that would be born to a woman if she were to live to the end of her childbearing years and bear children in accordance with age-specific fertility rates currently observed.” The TFR has the advantage over the simple birth rate—which is the number of live births per thousand people—because the TFR corrects for the age structure of a country’s female population. Leaving aside the effects of immigration and emigration, a TFR of 2.1 is necessary to keep a country’s population stable. Stated another way, a country needs a TFR of 2.1 to achieve replacement level fertility. A country with a TFR above 2.1 experiences long-run population growth, while a country with a TFR of less than 2.1 experiences long-run population decline.
The following figure shows the TFR for the United States for each year between 1960 and 2023. Since 1971, the TFR has been below 2.1 in every year except for 2006 and 2007. Immigration has helped to offset the effects on population growth of a TFR below 2.1.
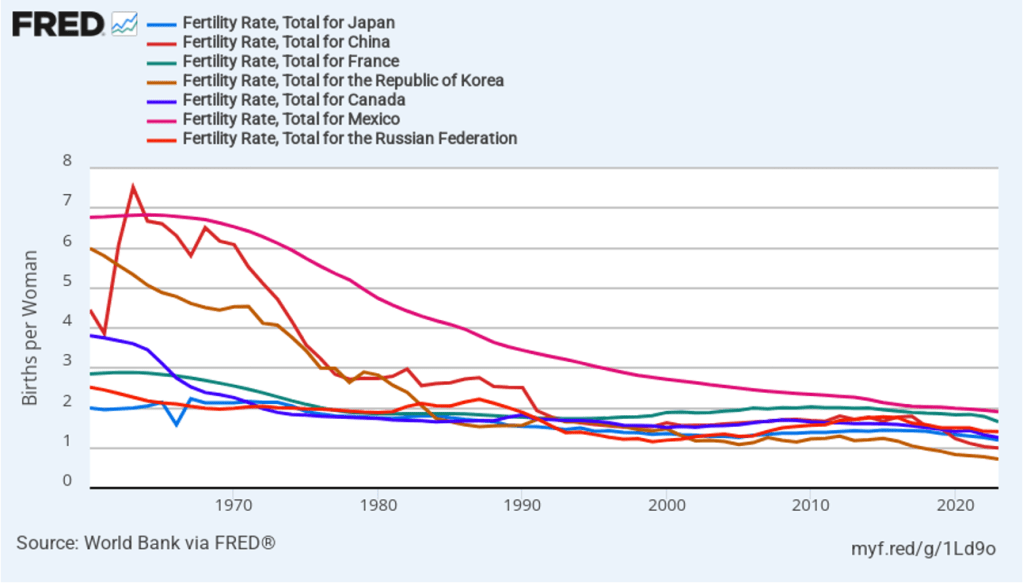
The United States is not alone in experiencing a sharp decline in its TFR since the 1960s. The following figure shows some other countries that currently have below replacement level fertility, including some countries—such as China, Japan, Korea, and Mexico—in which TFRs were well above 5 in the 1960s. In fact, only a relatively few countries, such as Israel and some countries in sub-Saharan Africa are still experiencing above replacement level fertility.
An aging population raises the number of retired people relative to the number of workers, making it difficult for governments to finance pensions and health care for older people. We discuss this problem with respect to the U.S. Social Security and Medicare programs in an Apply the Concept in Macroeconomics, Chapter 16 (Economics, Chapter 26 and Essentials of Economics, Chapter 18). Countries experiencing a declining population typically also experience lower rates of economic growth than do countries with growing populations. Finally, as we discuss in an Apply the Concept in Microeconomics, Chapter 3, different generations often differ in the mix of products they buy. For instance, a declining number of children results in declining demand for diapers, strollers, and toys.
During 2023, GDP and employment have continued to expand. Between the second quarter of 2022 and the second quarter of 2023, nominal GDP increased by 6.1 percent. From July 2022 to July 2023, total employment increased by 3.3 million as measured by the establishment (or payroll) survey and by 3.0 as measured by the household survey. (In this post, we discuss the differences between the employment measures in the two surveys.)
We would expect that with an expanding economy, federal tax revenues would rise and federal expenditures on unemployment insurance and other transfer programs would decline, reducing the federal budget deficit. (We discuss the effects of the business cycle on the federal budget deficit in Macroeconomics, Chapter 16, Section 16.6, Economics, Chapter 26, Section 26.6, and Essentials of Economics, Chapter 18, Section 18.6.) In fact, though, as the figure from the Congressional Budget Office (CBO) at the top of this post shows, the federal budget deficit actually increased substantially during 2023 in comparison with 2022. The federal budget deficit from the beginning of government’s fiscal year on October 1, 2022 through July 2023 was $1,617 billion, more than double the $726 billion deficit during the same period in fiscal 2022.
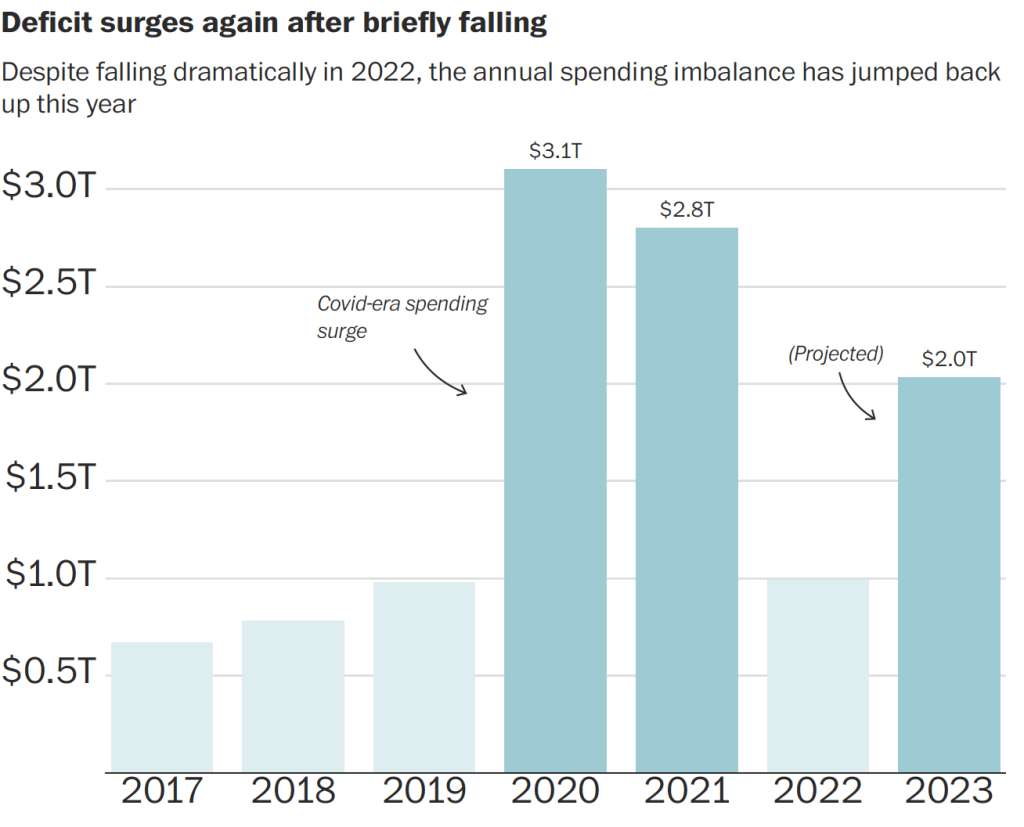
The following figure from an article in the Washington Post uses data from the Committee for a Responsible Federal Budget to illustrate changes in the federal budget deficit in recent years. The figure shows the sharp decline in the federal budget deficit in 2022 as the economic recovery from the Covid–19 pandemic increased federal tax receipts and reduced federal expenditures as emergency spending programs ended. Given the continuing economic recovery, the surge in the deficit during 2023 was unexpected.
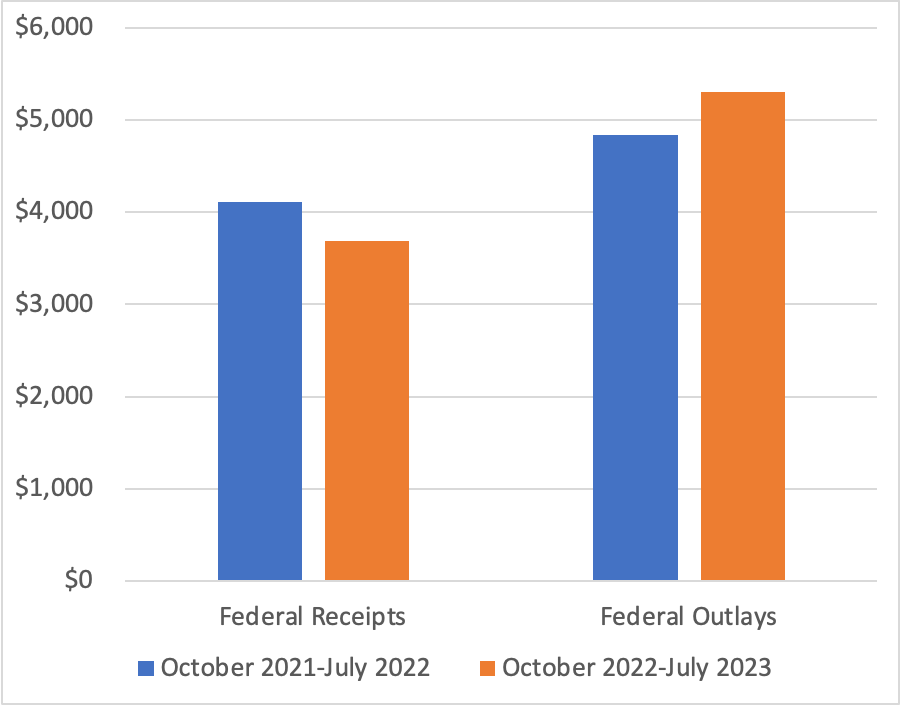
As the following figure shows, using CBO data, federal receipts—mainly taxes—are 10 percent lower this year than last year, and federal outlays—including transfer payments—are 11 percent higher. For receipts to fall and outlays to increase during an economic expansion is very unusual. As an article in the Wall Street Journal put it: “Something strange is happening with the federal budget this year.”
Note: The values on the vertical axis are in billions of dollars.
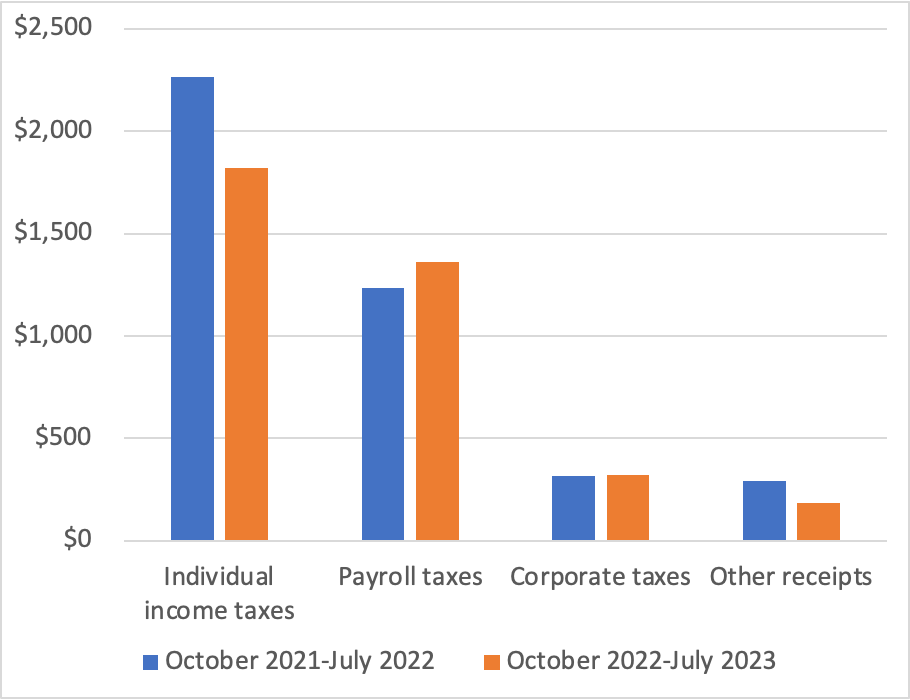
The following figure shows a breakdown of the decline in federal receipts. While corporate taxes and payroll taxes (primarily used to fund the Social Security and Medicare systems) increased, personal income tax receipts fell by 20 percent, and “other receipts” fell by 37 percent. The decline in other receipts is largely the result of a decline in payments from the Federal Reserve to the U.S. Treasury from $99 billion in 2022 to $1 billion in 2023. As we discuss in Macroeconomics, Chapter 17, Section 17.4 (Economics, Chapter 27, Section 27.4), Congress intended the Federal Reserve to be independent of the rest of the government. Unlike other federal agencies and departments, the Fed is self-financing rather than being financed by Congressional appropriations. Typically, the Fed makes a profit because the interest it earns on its holdings of Treasury securities is more than the interest it pays banks on their reserve deposits. After paying its operating costs, the Fed pays the rest of its profit to the Treasury. But as the Fed increased its target for the federal funds rate beginning in March 2022, it also increased the interest rate it pays banks on their reserve deposits. Because most of the securities it holds pay low interest rates, the Fed has begun running a deficit, reducing the payments it makes to the Treasury.
Note: The values on the vertical axis are in billions of dollars.
The reasons for the sharp decline in individual income taxes are less clear. The decline was in the “nonwithheld category” of individual income taxes; federal income taxes withheld from worker paychecks increased. People who are self-employed or who receive substantial income from sources such as capital gains from selling stocks, make quarterly estimated income tax payments. It’s these types of personal income taxes that have been unexpectedly low. Accordingly, smaller capital gains may be one explanation for the shortfall in federal revenues, but a more complete explanation won’t be possible until more data become available later in the year.
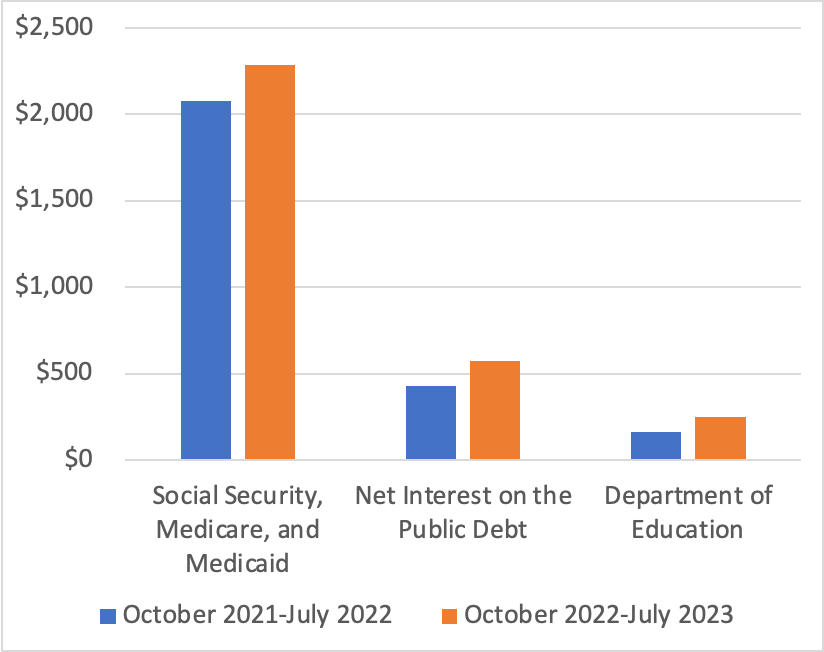
The following figure shows the categories of federal outlays that have increased the most from 2022 to 2023. The largest increase is in spending on Social Security, Medicare, and Medicaid, with spending on Social Security alone increasing by $111 billion. This increase is due partly to an increase in the number of retired workers receiving benefits and partly to the sharp rise in inflation, because Social Security is indexed to changes in the consumer price index (CPI). Spending on Medicare increased by $66 billion or a surprisingly large 18 percent. Interest payments on the public debt (also called the federal government debt or the national debt) increased by $146 billion or 34 percent because interest rates on newly issued Treasury securities rose as nominal interest rates adjusted to the increase in inflation and because the public debt had increased significantly as a result of the large budget deficits of 2020 and 2021. The increase in spending by the Department of Education reflects the effects of the changes the Biden administration made to student loans eligible for the income-driven repayment plan. (We discuss the income-driven repayment plan for student loans in this blog post.)
Note: The values on the vertical axis are in billions of dollars.
The surge in federal government outlays occurred despite a $120 billion decline in refundable tax credits, largely due to the expiration of the expansion of the child tax credit Congress enacted during the pandemic, a $98 billion decline in Treasury payments to state and local governments to help offset the financial effects of the pandemic, and $59 billion decline in federal payments to hospitals and other medical facilities to offset increased costs due to the pandemic.
In this blog post from February, we discussed the challenges posed to Congress and the president by the CBO’s forecasts of rising federal budget deficits and corresponding increases in the federal government’s debt. The unexpected expansion in the size of the federal budget deficit for the current fiscal year significantly adds to the task of putting the federal government’s finances on a sound basis.
On February 1, 2022, a headline in the Wall Street Journal noted that: “U.S. National Debt Exceeds $30 Trillion for the First Time.” The national debt—or, more formally, the federal government debt—is the value of all U.S. Treasury securities outstanding. Treasury securities include Treasury bills, which mature in one year or less; Treasury notes, which mature between 2 years and 10 years; Treasury bonds, which mature in 30 years; U.S. savings bonds purchased by individual investors; and Treasury Inflation-Protected Securities (TIPS), which, unlike other Treasury securities, have their principal amounts adjusted every six months to reflect changes in the consumer price index (CPI).
With a value of $30 trillion, the federal government debt in early February is about 120 percent of GDP, a record that exceeds the ratio of government debt to GDP during World War II. In 2007, at the beginning of the Great Recession of 2007–2009, the ratio of government debt to GDP was only 35 percent. (We discuss the federal government debt in Macroeconomics, Chapter 16, Section 16.6 and in Economics, Chapter 26, Section 26.6.)
There are many important economic issues involved with the federal government debt, but in this blog post we’ll focus just on the question of who owns the debt.
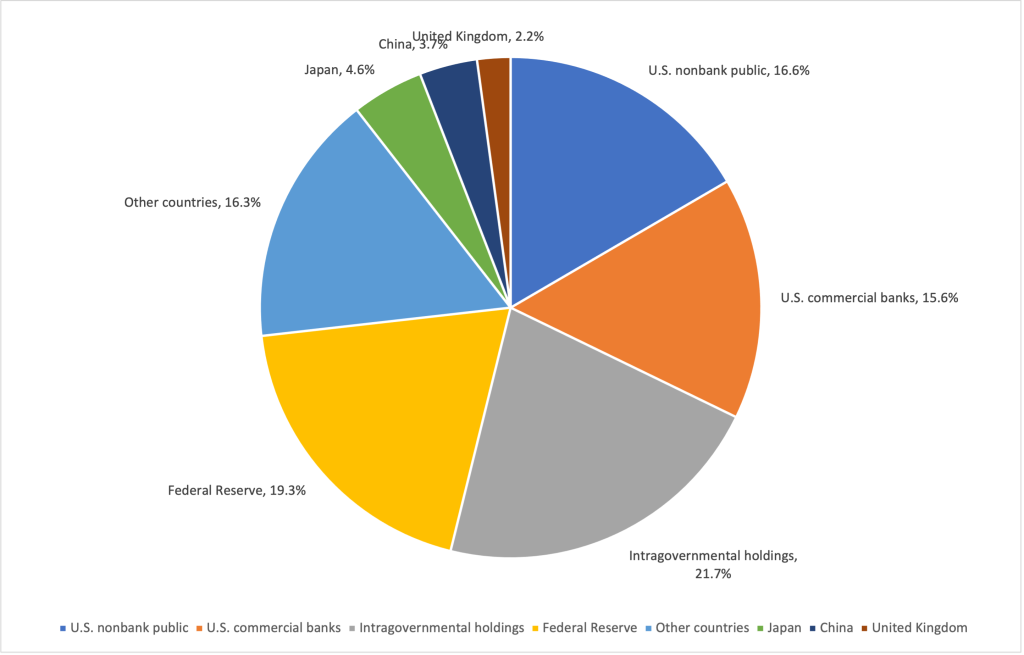
The pie chart below shows the shares of the debt held by different groups. The largest slice shown is for “intragovernmental holdings,” which represent ownership of Treasury securities by government trust funds, notably the Social Security trust funds. The Social Security system makes payments to retired or disabled workers. The system operates on a pay-as-you-go basis, which means that the payroll taxes collected from today’s workers are used to make payments to retired workers. Because of slowing population growth, Congress authorized an increase in payroll taxes above the level necessary to make current payments. The Social Security system has invested the surplus in special Treasury securities that the Treasury redeems when the funds are necessary to make payments to retired workers. (In the Apply the Concept “Is Spending on Social Security and Medicare a Fiscal Time Bomb?” in Macroeconomics, Chapter 16, Section 16.1, we discuss the long-term funding problems of the Social Security and Medicare systems.)
Some economists argue that the value of these Treasury securities should not be counted as part of the federal government debt because the securities are not marketable in the way that Treasury bills, notes, and bonds are and because the securities represent a flow of funds from one federal agency to another federal agency. If we exclude the value of these securities, the national debt on February 1, 2022 was $23.5 trillion rather than $30.0 trillion.
The Federal Reserve System holds about 19 percent of federal government debt. The Fed buys and sells Treasury securities as part of its normal conduct of monetary policy. In addition, the Fed accumulated large holdings of Treasury securities as part of its quantitative easing operations during and following the 2007–2009 financial crisis and from 2020 to 2022 during the worst of the Covid-19 pandemic. (We discuss quantitative easing in Macroeconomics, Chapter 15, Section 15.3.)
About 27 percent of the debt is held by foreign central banks, foreign commercial banks, and foreign investors. The largest amount of Treasury debt is held by Japan, followed by China and the United Kingdom. All other countries combined hold about 16 percent of the debt.
U.S. commercial banks hold more than 15 percent of the debt. Banks hold Treasury securities partly because since the 2007–2009 financial crisis most interest rates, including those on loans and on corporate and municipal bonds, have been very low compared with historic averages. The interest rates on these assets are in some cases too low to compensate banks for the risk of owning the assets rather than default-risk free Treasury securities. In addition, large banks are required to meet a liquidity coverage ratio, which means that they have to hold sufficient liquid assets—those that can be easily converted into cash—to meet their need for funds in a financial crisis. Many banks meet their liquidity requirements, in part, by owning Treasury securities.
The remaining Treasury securities—about 16.5 percent of the total federal government debt—are held by the U.S. nonbank public. The nonbank public includes financial firms—such as investment banks, insurance companies, and mutual funds—as well as individual investors.
Sources: Amara Omeokwe, “U.S. National Debt Exceeds $30 Trillion for First Time,” Wall Street Journal, February 1, 2022; “Debt to the Penny,” fiscaldata.treasury.gov; “Major Foreign Holders of Treasury Securities,” ticdata.treasury.gov; and Federal Reserve Bank of St. Louis.