Is the U.S. Economy Heading “Back to the ‘60s”?

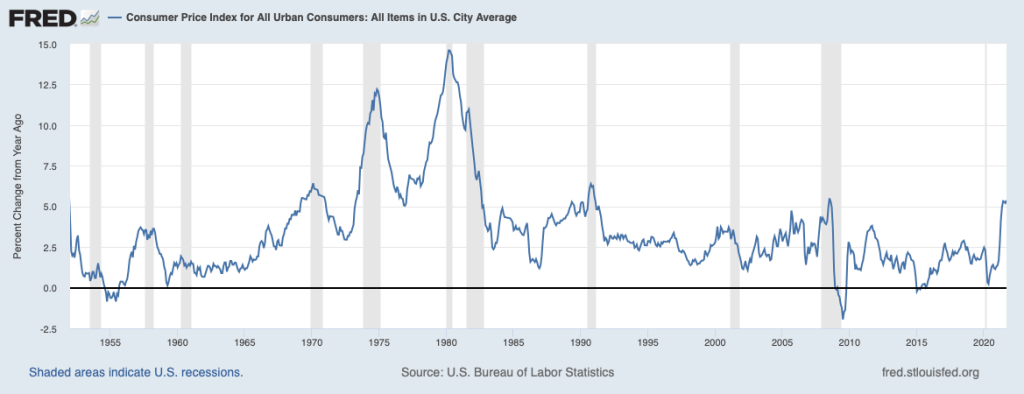
A recent publication by economists Regis Barnichon, Luiz E. Oliveira, and Adam H. Shapiro at the Federal Reserve Bank of San Francisco asks that provocative question. “The ‘60s” is a reference to the events that led to the U.S. economy experiencing more than 10 years of high inflation rates. Below is a graph similar to Chapter 15, Figure 15.1 in Macroeconomics (Economics, Chapter 25, Figure 25.1) that shows the inflation rate in the United States as measured by the percentage change in the Consumer Price Index (CPI) for each year since 1952. Economists call the years from 1968 though 1982 the “Great Inflation” because inflation was greater during that period than during any other period in the history of the United States.
As we discuss in Macroeconomics, Chapter 17, Section 17.2 (Economics, Chapter 27, Section 27.2), many economists believe that the Great Inflation began as a result of the Federal Reserve attempting to keep the unemployment rate below the natural rate of unemployment for a period of several years. As predicted by the Phillips Curve, the inflation rate increased and, as Milton Friedman and Edmund Phelps had argued would likely happen, the expected inflation rate eventually increased. The inflation was made worse during the 1970s by two supply shocks resulting from sharp increases in oil prices.

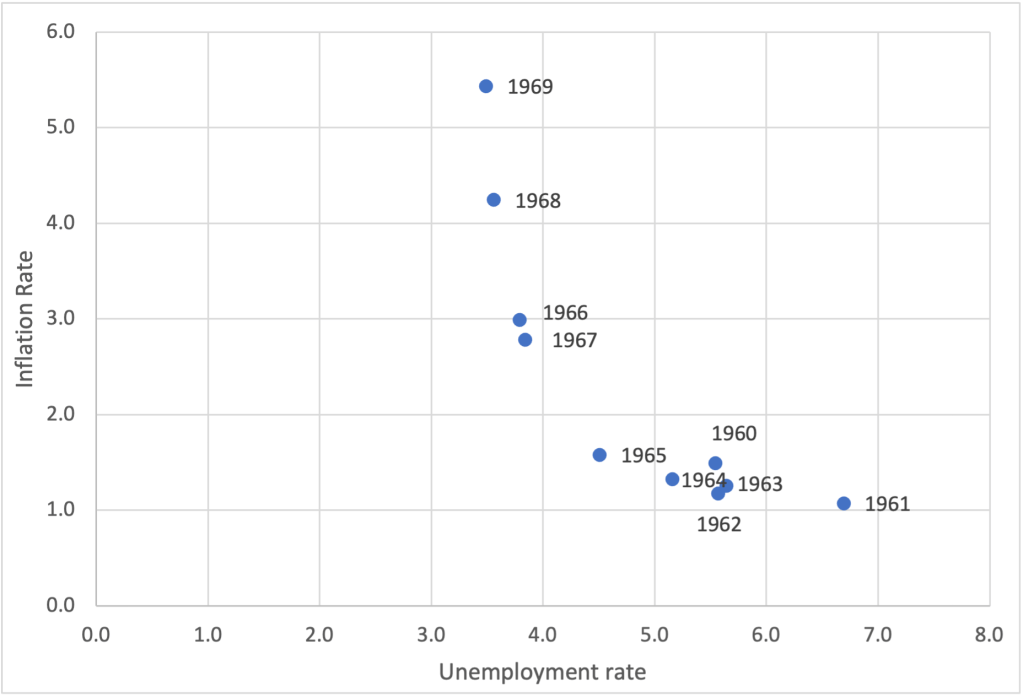
Is the United States on the edge of repeating the experience of the Great Inflation? Earlier this year, Olivier Blanchard of the Peterson Institute for International Economics wrote a paper arguing that the U.S. economy was at significant risk of experiencing a significant acceleration in inflation. His paper included a figure similar to the one below showing the combinations of inflation and unemployment during each year of the 1960s. The figure shows a substantial acceleration in inflation over the course of the decade.
Blanchard notes that: 

“The history of the Phillips curve is one of shifts, largely due to the adjustment of expectations of inflation to actual inflation. True, expectations have [currently] been extremely sticky for a long time, apparently not reacting to movements in actual inflation. But, with such overheating, expectations might well deanchor. If they do, the increase in inflation could be much stronger.” 

….

“If inflation were to take off, there would be two scenarios: one in which the Fed would let inflation increase, perhaps substantially, and another—more likely—in which the Fed would tighten monetary policy, perhaps again substantially. Neither of these two scenarios is ideal. In the first, inflation expectations would likely become deanchored, cancelling one of the major accomplishments of monetary policy in the last 20 years and making monetary policy more difficult to use in the future. In the second, the increase in interest rates might have to be very large, leading to problems in financial markets.”

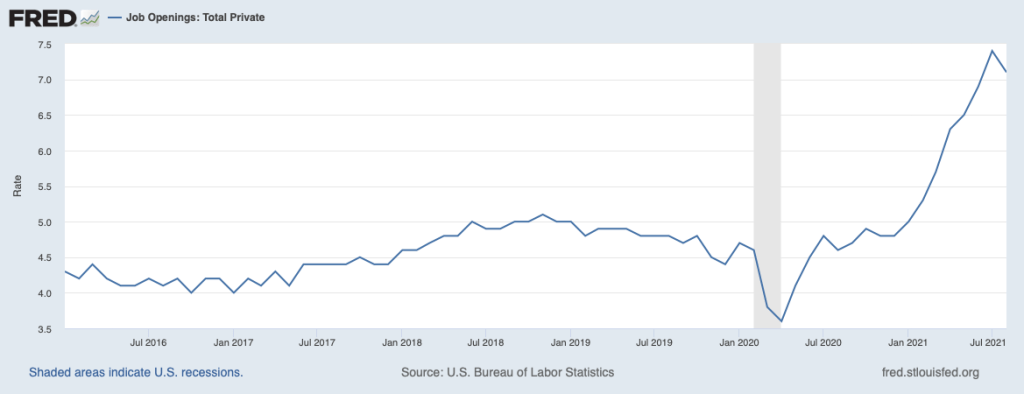
The authors of the San Francisco Fed publication are more optimistic. They begin their discussion by observing that because of the pandemic, the state of the labor market is more difficult to assess than in most years. They note that the unemployment rate of 4.8 percent in September 2021 was only slightly below the average unemployment rate over the past 30 years and well above the low unemployment rates of 2019 and early 2021. So, on the basis of the unemployment rate, policymakers at the Fed and in Congress might conclude that the inflation the U.S. economy is experiencing is not the result of overly tight labor markets such as those of the late 1960s. But the job openings rate(sometimes called the vacancy rate) is telling a different story. Job openings are positions that are both available to be filled within the next 30 days and for which firms are actively recruiting applicants from outside the firm. (According to the BLS: “The job openings rate is computed by dividing the number of job openings by the sum of employment and job openings and multiplying that quotient by 100.”)

The authors of the San Francisco Fed study note that “the vacancy rate is well above its 30-year average … and has surpassed its historic highs from the late 1960s … indicating that employers are having a difficult time filling positions. Confirming this high vacancy rate, the fraction of small businesses reporting that job openings are hard to fill is at historic highs ….” The figures below show the vacancy rate and the unemployment rate since January 2016.
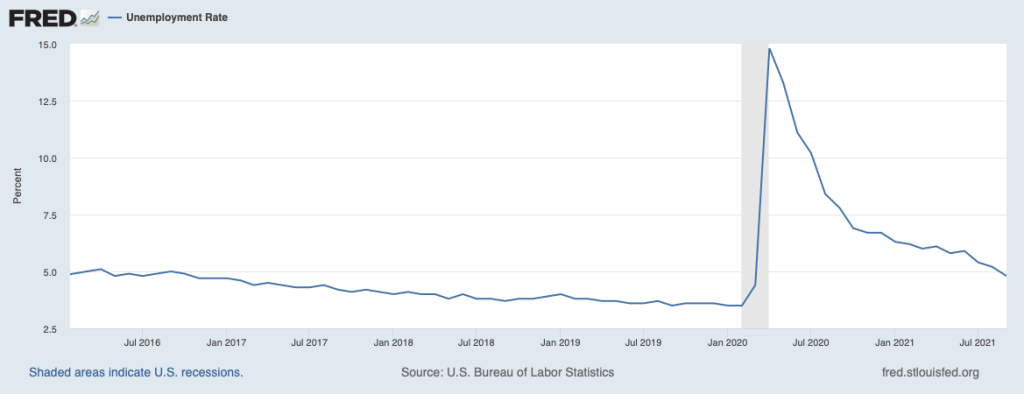
The authors combine the unemployment rate and the vacancy rate into a statistic—the vacancy-to-unemployment ratio—that they demonstrate has historically done a better job of explaining movements in inflation than has the unemployment rate.  They expect that expansionary fiscal policy will result in an increase in vacancy-to-unemployment ratio and, therefore, an increase in the inflation rate. But they share the view of Blanchard and many other economists that a key issue is “the stability of longer-run inflation expectations.” 

We know that in the 1960s, several years of rising inflation made long-run inflation expectations unstable—in terms of the discussion in Chapter 17, the short-run Phillips curve shifted up. We don’t yet know what will happen to inflation expectations in late 2021 and in 2022, so we can’t yet tell how persistent current rates of inflation will be. 

Sources: Regis Barnichon, Luiz E. Oliveira, and Adam H. Shapiro, “Is the American Rescue Plan Taking Us Back to the ’60s?,” FRBSF Economic Letter, No. 2021-27, October 18, 2021; Olivier Blanchard, “In Defense of Concerns over the $1.9 Trillion relief Plan,” piie.com, February 18, 2021; and Federal Reserve Bank of St. Louis.
Elkhart County, Indiana Rides the Surge in Spending on Consumer Durables

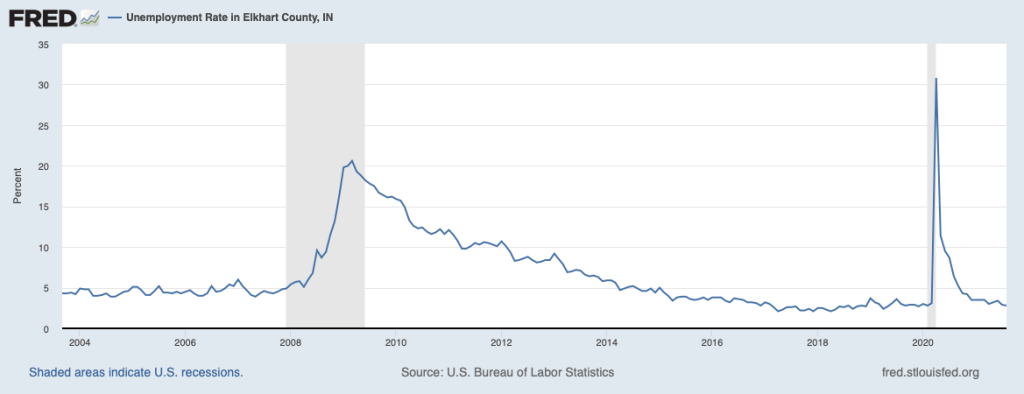
More than 80 percent of the recreational vehicles (RV) sold in the United States are manufactured in Elkhart County, Indiana. As we discuss in the opener to Chapter 22 in Economics (Chapter 12 in Macroeconomics), being dependent on sales of expensive durable goods like RVs means that the county is particularly vulnerable to the business cycle, with local firms experiencing rising sales during economic expansions and sharply falling sales during economic recessions. Accordingly, the unemployment rate in the county fluctuates much more during the business cycle than is typical—as shown in the above graph.

For example, during the Great Recession of 2007-2009, the unemployment rate in the country rose from a low of 3.9 percent in May 2007 to a high of 20 percent in March 2009, before declining during the following economic recovery.  Just before the start of the Covid-19 recession of 2020, the unemployment rate in Elkhart was 2.8 percent. It then soared to 30.8 percent in April. 

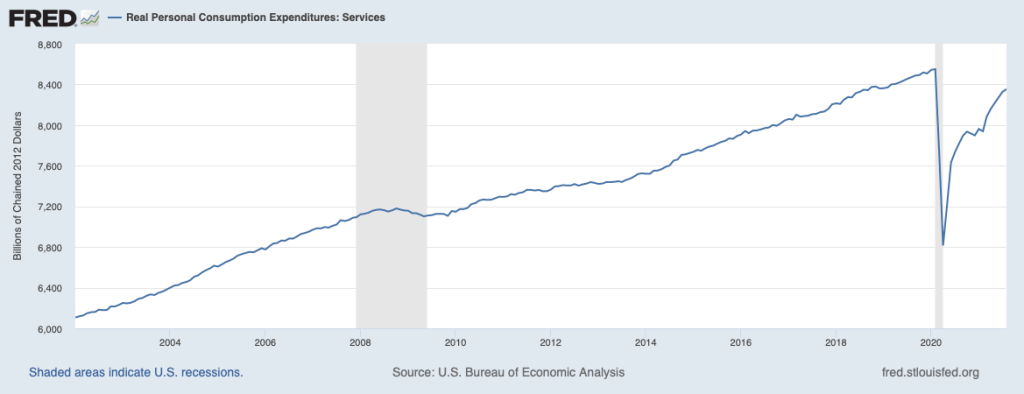
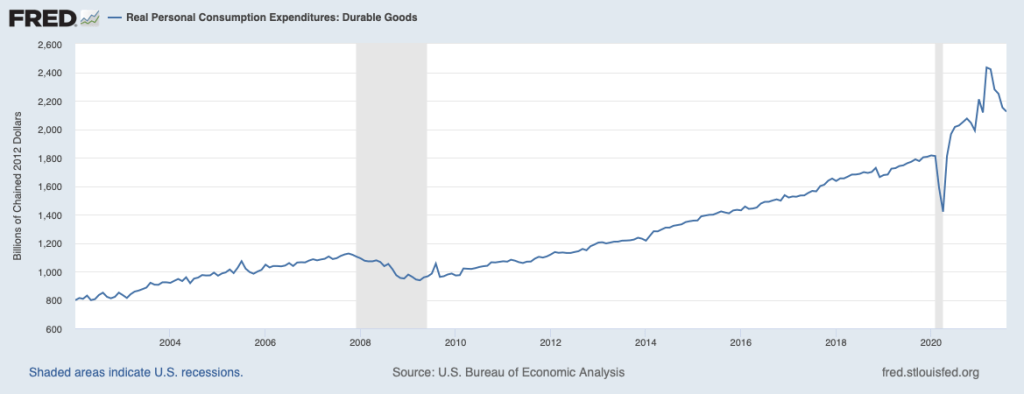
But, as we discuss in the chapter, the recovery from the 2020 recession was unusually rapid, although uneven. Many services industries, such as restaurants, gyms, and movie theaters continued to struggle well into 2021 as firms had difficulty attracting workers and as some consumers remained reluctant to spend time inside in close contact with other people. In contrast, consumer spending on durable goods was far above its pre-pandemic level, as well as being above the rate at which it had been growing during the years before the pandemic. The two graphs below show real consumer spending on durables and on services up through August 2021.

During 2021, sales of RVs through August were 50 percent higher than in the same period in 2020 and were on a pace to reach record annual sales. The success of the RV industry has led to rising incomes in Elkhart County, which, in turn, has allowed the area to attract other industries, including a logistics center that when completed will be the largest industrial building in Indiana and an Amazon warehouse that when completed will provide 1,000 new jobs. Rising incomes have also supported other businesses, such as community theaters, art galleries, and a recently reopened 1920s-era hotel.

In October 2021, the Wall Street Journal ranked Elkhart County first in its rating of metropolitan areas as measured by the index it compiles with realtor.com. The index “identifies the top metro areas for home buyers seeking an appreciating housing market and appealing lifestyle amenities.” If consumers continue to buy more goods and fewer services, it could be bad news for restaurants and other service industries, but good news for places like Elkhart that depend on goods-producing industries. 

Sources: Nicole Friedman, “RV Capital of America Tops WSJ/Realtor.com Housing Index in Third Quarter,” wsj.com, October 19, 2021; Business Wire, “Amazon Announces New Robotics Fulfillment Center and Delivery Station in Elkhart County, Creating More Than 1,000 New, Full-Time Jobs,” businesswire.com, October 7, 2021; Construction Review Online, “Hotel Elkhart Grand Opening Celebrated in Elkhart, Indiana,” constructionreviewonline.com, October 4, 2021; Construction Review Online, “Elkhart County Logistics Facility to Bring about 1,000 jobs in Indiana,” constructionreviewonline.com, August 16, 2021; Federal Reserve Bank of St. Louis; and RV Industry Association.

WeWork Gets SPAC’d

In 2021, SPACs were the hottest trend on the stock market and had become the leading way for companies to go public. A public company is one with shares that trade on the stock market. Private firms make up more than 95 percent of all firms in the United States. Most will never become public firms because they will never grow large enough for investors to have sufficient information on the firms’ financial health to be willing to buy the firms’ stocks and bonds.

But some firms, particularly technology firms, grow rapidly enough that they are able to become public firms. Apple, Microsoft, Google, Uber, Facebook, Snap, and other firms have followed this path. When these firms went public, they did so using an initial public offering (IPO). (We briefly discuss IPOs in Economics and Microeconomics, Chapter 8, Section 8.2 and in Macroeconomics, Chapter 6, Section 6.2.) With an IPO, a firm uses one or more investment banks to underwrite the firm’s sales of new stocks or bonds to the public. In underwriting,investment banks typically guarantee a price for stocks or bonds to the issuing firm, sell the stocks or bonds in financial markets or directly to investors at a higher price, and keep the difference, known as the spread.

Beginning in 2020 and continuing through 2021, an increasing number of firms have used a different means of going public—merging with a SPAC. SPAC stands for special-purpose acquisition company and is a firm that holds only cash—it doesn’t sell a good or service—and only has the purpose of merging with another firm that wants to go public. Once a merger takes place, the acquired firm takes the place of the SPAC in the stock market. For instance, a SPAC named Diamond Eagle Acquisition merged with online sports betting site DraftKings in April 2020. Once the merger had been completed, DraftKings took Diamond Eagle’s place on the stock market, trading under the stock symbol DKNG. By 2021, the value of SPAC mergers had risen to being three times as much as the value of IPOs.

Some firms intending to go public prefer SPACs to traditional IPOs because they can bargain directly with the managers of the SPAC in determining the value of the firm. In addition, IPOs are closely regulated by the federal government’s Securities and Exchange Commission (SEC). In particular, the SEC monitors whether an investment bank is accurately stating the financial prospects of a firm whose IPO the bank is underwriting. The claims that SPACs make when attracting investors are less closely monitored. SPAC mergers can also be finalized more quickly than can traditional IPOs.

The experience of WeWork illustrates how some firms that have struggled to go public through an IPO have been able to do so by merging with a SPAC. Adam Neumann and Miguel McLevey founded WeWork in 2010 as a firm that would rent office space in cities, renovate the space, and then sub-lease it to other firms. In 2019, the firm prepared for an IPO that would have given the firm a total value of more than $40 billion. But doubts about the firm’s business model led to an indefinite postponement of the IPO and Neumann was forced out as CEO.

WeWork was reorganized under new CEO Sandeep Mathrani and went public in October 2021 by merging with BowX Acquisition Corporation, a SPAC. Although WeWork’s stock began trading (under stock symbol WE) at a price that put the firm’s value at about $9 billion—far below the value it expected at the time of its postponed IPO two years before—investors seemed optimistic about the firm’s future because its stock price rose sharply during the first two days it traded on the stock market. 

Some policymakers are concerned that individual investors may not have sufficient information on firms that go public through a merger with a SPAC. Under one proposal being considered by Congress, financial advisers would only be allowed to recommend investing in SPACs to wealthy investors. The SEC is also considering whether new regulations governing SPACS were needed. Testifying before Congress, SEC Chair Gary Gensler sated: “There’s real questions about who’s benefiting [from firms going public using SPACs] and [about] investor protection.” 

It remains to be seen whether SPACs will retain their current position as being the leading way for firms to go public.

Sources: Dave Sebastian, “WeWork Shares Rise on First Day of Trading, Two Years After Failed IPO,” wsj.com, October 21, 2021; Peter Santilli and Amrith Ramkumar, “SPACs Are the Stock Market’s Hottest Trend. Here’s How They Work,” wsj.com, March 29, 2021; Benjamin Bain, “SPAC Marketing Heavily Curtailed in House Democrats’ Draft Bill,” bloomberg.com, October 4, 2021; and Dave Michaels, “SEC Weighs New Investor Protections for SPACs,” wsj.com, May 26, 2021.

10/17/21 Podcast – Authors Glenn Hubbard & Tony O’Brien discuss economic impact of infrastructure spending & the supply-chain challenges.

Authors Glenn Hubbard and Tony O’Brien discuss the economic impact of the recent infrastructure bill and what role fiscal policy plays in determining shovel-ready projects. Also, they explore the vast impact of the economy-wide supply-chain issues and the challenges companies face. Until the pandemic, we had a very efficient supply chain but now we’re seeing companies employ the “just-in-case” inventory method vs. “just-in-time”!

Some links referenced in the podcast:

Here’s Alan Cole’s blog: https://fullstackeconomics.com/how-i-reluctantly-became-an-inflation-crank/

Neil Irwin wrote a column referencing Cole here:  https://www.nytimes.com/2021/10/10/upshot/shadow-inflation-analysis.html

Here’s a Times article on the inefficiency of subway construction in NYC:  https://www.nytimes.com/2017/12/28/nyregion/new-york-subway-construction-costs.html

A recent article on the state of CA’s bullet train:  https://www.kcra.com/article/california-bullet-trains-latest-woe-high-speed/37954851

A WSJ column on goods v. services: https://www.wsj.com/articles/at-times-like-these-inflation-isnt-all-bad-11634290202

The Pandemic and Hidden Inflation

If the price of your meal is the same, but the service is slow and the menu is limited you have experienced hidden inflation.

Each month, hundreds of employees of the Bureau of Labor Statistics gather data on prices of goods and services from stores in 87 cities and from websites. The BLS constructs the consumer price index (CPI) by giving each price a weight equal to the fraction of a typical family’s budget spent on that good or service. (We discuss the construction of the CPI in Chapter 9, Section 9.4 of Macroeconomics and Chapter 19, Section 19.4 of Economics.) Ideally, the BLS tracks prices of the same product over time. But sometimes a particular brand and style of shirt, for example, is discontinued. In that case, the BLS will use instead the price of a shirt that is a very close substitute.

A more difficult problem arises when the price of a good increases at the same time that the quality of the good improves. For instance, a new model iPhone may have both a higher price and a better battery than the model it replaces, so the higher price partly reflects the improvement in the quality of the phone.  The BLS has long been aware of this problem and has developed statistical techniques that attempt to identify that part of price increases that are due to increases in quality. Economists differ in their views on how successfully the BLS has dealt with this quality bias to the measured inflation rate. Because of this bias in constructing the CPI, it’s possible that the published values of inflation may overstate the actual annual rate of inflation by 0.5 percentage point. So, for instance, the BLS might report an inflation rate of 3.5 percent when the actual inflation rate—if the BLS could determine it—was 4.0 percent.

During 2021, a number of observers pointed to a hidden type of inflation occurring, particularly in some service industries. For example, because many restaurants were having difficulty hiring servers, it was often taking longer for customers to have their orders taken and to have their food brought to the table.  Because restaurants were also having difficulty hiring enough cooks, they also limited the items available on their menus. In other words, the service these restaurants were offering was not as good as it had been prior to the pandemic. So even if the restaurants kept their prices unchanged, their customers were paying the same price but receiving less. 

Alan Cole, who was formerly a senior economist with the Congressional Joint Economic Committee, noted on his blog that “goods and services are getting worse faster than the official statistics acknowledge, suggesting that our inflation problem has actually been bigger than the official statistics suggest.” As examples, he noted that “hotels clean rooms less frequently on multi-night stays,” “shipping delays are longer, and phone hold times at airlines are worse.” In a column in the New York Times, economics writer Neil Irwin made similar points: “Complaints have been frequent about the cleanliness of [restaurant] tables, floors and bathrooms.”  And: “People trying to buy appliances and other retail goods are waiting longer.”

A column in the Wall Street Journal on business travel by Scott McCartney was headlined “The Incredible Disappearing Hotel Breakfast.” McCartney noted that many hotels continue to advertise free hot breakfasts on their websites and apps but have stopped providing them. He also noted that hotels “have suffered from labor shortages that have made it difficult to supply services such as daily housekeeping or loyalty-group lounges,” in addition to hot breakfasts.

The BLS makes no attempt to adjust the CPI for these types of deterioration in the quality of services because doing so would be very difficult. As Irwin notes: “Customer service preferences—particularly how much good service is worth—varies highly among individuals and is hard to quantify. How much extra would you pay for a fast-food hamburger from a restaurant that cleans its restroom more frequently than the place across the street?”

As we noted earlier, most economists believe that the failure of the BLS to fully account for improvements in the quality of goods results in changes in the CPI overstating the true inflation rate.  This bias may have been more than offset since the beginning of the pandemic by deterioration in the quality of services resulting in the CPI understating the true inflation rate. As the dislocations caused by the pandemic gradually resolve themselves, it seems likely that the deterioration in services will be reversed. But it’s possible that the deterioration in the provision of some services may persist. Fortunately, unless the deterioration increases over time, it would not continue to distort the measurement of the inflation rate because the same lower level of service would be included in every period’s prices.

Sources: Alan Cole, “How I Reluctantly Became an Inflation Crank,” fullstackeconomics.com, September 8, 2021; Scott McCartney, “The Incredible Disappearing Hotel Breakfast—and Other Amenities Travelers Miss,” wsj.com, October 20, 2021; and Neil Irwin, “There Is Shadow Inflation Taking Place All Around Us,” nytimes.com, October 14, 2021.

Solved Problem: The Fed’s Policy Dilemma

Supports:  Macroneconomics Chapter 15, Section 15.3; Economics Chapter 25, Section 25.3; and Essentials of Economics Chapter 17, Sections 17.3.

Solved Problem: The Fed’s Policy Dilemma

   In the fall of 2021, the inflation rate was at its highest level since 2008. The unemployment rate was above 5 percent, which was much lower than in the spring of 2020, but still well above its level of early 2020 before the Covid-19 pandemic. In testifying before Congress, Fed Chair Jerome Powell stated that he believed the high inflation rate was transitory and in the longer run “inflation is expected to drop back toward our longer-run 2 percent goal.”

But Powell also stated that if inflation continued to remain high the Fed would face a policy dilemma. “Almost all of the time, inflation is low when unemployment is high, so interest rates work on both problems.” But in contrast, in the fall of 2021 both the unemployment and inflation rates were high: “That’s the very difficult situation we find ourselves in.”

a. Briefly explain what Powell meant by saying that almost all of the time “interest rates work on both problems.”

b. Why did macroeconomic conditions in the fall of 2021 present Fed policymakers with a “very difficult” situation?

Source: Kate Davidson and Nick Timiraos, “Powell Says Fed Faces ‘Difficult Trade-Off’ if Inflation Doesn’t Moderate,” Wall Street Journal, September 30, 2021; and Chair Jerome H. Powell, “Testimony Before the Committee on Banking, Housing, and Urban Affairs, U.S. Senate, Washington, D.C.” September 28, 2021, federalreserve. gov..

Solving the Problem

Step 1:   Review the chapter material. This problem is about the policy situation the Fed faces when the unemployment and inflation rates are both high, so you may want to review Chapter 15, Section 15.3, “Monetary Policy and Economic Activity,” and the discussion of staflation, including Figure 13.7, in Chapter 13, Section 13.3, “Macroeconomic Equilibrium in the Long Run and the Short Run.”

Step 2:   Explain what Powell meant by “interest rates work on both problems.” We’ve seen that in the typical recession the unemployment rate increases while the inflation rate decreases. We’ve also seen that if the economy is above potential GDP, the unemployment rate is very low but the inflation rate increases. (To review these facts, see Chapter 10, Section 10.3 “The Business Cycle.”) The Fed uses changes in its target for the federal funds rate to affect the level of real GDP and the price level, as it attempts to hit its policy goals of high employment and price stability.

So “almost all of the time,” the Fed can use interest rates–changes in the target for the federal funds rate–to work on the problems of high unemployment and high inflation–depending on which is occuring during a particular period.

Step 3: Explain why macroeconomic conditions in the fall of 2021 presented Fed policymakers with a “very difficult” situation. As Powell observes, “almost all the time” Fed policy is focused on reducing either high unemployment or high inflation, but not both. As we note in Chapter 13, Section 13.3, economists refer to a situation when the unemployment and inflations rates are both high at the same time as a period of stagflation. If the inflation rate is high, then expansionary monetary policy–a low target for the federal funds rate–will reduce the unemployment rate but make an already high inflation rate even higher. Similarly, if the unemployment rate is high, then contractionary monetary policy–a high target for the federal funds rate–will reduce the inflation rate but make an already high unemploument rate even higher. A very difficult policy dilemma for the Fed!

How did Fed policymakers expect to resolve this difficulty? In his testimony, Powell explained that he believed that the high inflation rate the U.S. economy was experiencing during the fall of 2021 was transitory and would begin to decline once the supply problems caused by the Covid-19 pandemic were resolved in the coming months. Referring to the supply problems he noted that “These aren’t things that we [the Fed] can control.” Therefore, the Fed did not intend to use policy to address the high inflation rate and could continue to pursue an expansionary monetary policy to push the labor market back to full employment.

Coming Attractions: Hubbard and O’Brien Principles of Economics Updated

It’s customary for textbook authors to note that “much has happened in the economy” since the last edition of their book appeared. To say that much has happened since we prepared our last edition in 2019 would be a major understatement. Never in the lifetimes of today’s students and instructors have events like those of 2020 and 2021 occurred. The U.S. and world economies had experienced nothing like the Covid-19 pandemic since the influenza pandemic of 1918. In the spring of 2020, the U.S. economy suffered an unprecedented decline in the supply of goods and services as a majority of businesses in the country shut down to reduce spread of the virus. Many businesses remained closed or operated at greatly reduced capacity well into 2021. Most schools, including most colleges, switched to remote learning, which disrupted the lives of many students and their parents.

During the worst of the pandemic, total spending in the economy declined as the unemployment rate soared to levels not seen since the Great Depression of the 1930s. Reduced spending and closed businesses resulted in by far the largest decline in total production in such a short period in the history of the U.S. economy. Congress, the Trump and Biden administrations, and the Federal Reserve responded with fiscal and monetary policies that were also unprecedented.

Our updated Eighth Edition covers all of these developments as well as the policy debates they initiated. As with previous editions, we rely on extensive digital resources, including: author-created application videos and audio recordings of the chapter openers and Apply the Concept features; figure animation videos; interactive real-time data graphs animations; and Solved Problem whiteboard videos.

Glenn and Tony discuss the updated edition in this video:

Sample chapters will be available by October 15.

The full Macroeconomics text will available in early to mid December.

The full Microeconomics text will be available in mid to late December.

If you would like to view the sample chapters or are considering adopting the updated Eighth Edition for the spring semester, please contact your local Pearson representative. You can use this LINK to find and contact your representative.

09/03/21 Podcast – Authors Glenn Hubbard & Tony O’Brien discuss the recent jobs report, Fed comments, and financial stability!

Authors Glenn Hubbard and Tony O’Brien discuss the recent jobs report falling short of expectations. They also discuss the comments of Fed Chairman Powell’s comments at the Federal Reserve’s recent Jackson Hole conference. They also get to some of the recommendations of a Brookings Task Force, co-chaired by Glenn Hubbard, on ways to address financial stability. Use the links below to see more information about these timely topics:
Powell’s Jackson Hole speech: 

https://www.federalreserve.gov/newsevents/speech/files/powell20210827a.pdf 

The report of Glenn’s task force: 

https://www.brookings.edu/wp-content/uploads/2021/06/financial-stability_report.pdf 

The most recent economic forecasts of the FOMC: 

https://www.federalreserve.gov/monetarypolicy/files/fomcprojtabl20210616.pdf

Menu Costs in the Digital Age

Inflation imposes a number of costs on households and firms (see our discussion in Economics, Chapter 19, Section 19.7 and Macroeconomics, Chapter 19, Section 19.7). Economists call the costs to firms of changing prices menu costs. For instance, when supermarkets raise prices, employees have to spend time changing the prices posted on shelves. 

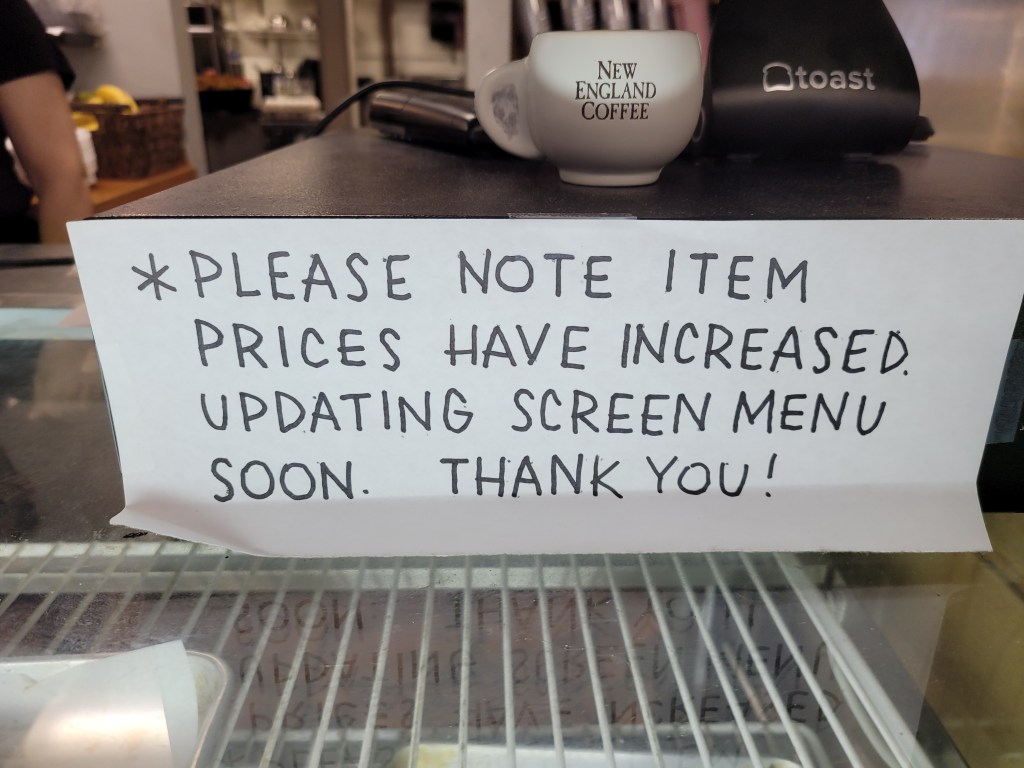
When restaurants raise prices, they have to print new menus (hence the general name economists give to these costs). Particularly during the Covid-19 pandemic, the trend toward having digital menus rather than paper ones increased.  But even with digital menus, a restaurant incurs some costs, as this sign in a coffee shop indicates. An employee has to update the digital menu to reflect the new prices and, in the meantime, the shop may experience friction from customers who see one price on the digital menu and are charged a higher price when they pay at the register. 

H/T Lena Buonanno

WELCOME BACK! New 08/20/21 Podcast – Authors Glenn Hubbard & Tony O’Brien return to discuss delta variant & inflation!

Join authors Glenn Hubbard and Tony O’Brien as they return for a new academic year! The issues have evolved but the importance of these issues has not waned. We discuss the impact of closures related to the delta variant has on the economy. The discussion extends to the active fiscal and monetary policy that has reintroduced inflation as a topic facing our economy. Many students have little or no experience with inflation so it is a learning opportunity. Check back regularly where Glenn & Tony will continue to wrestle with these important economic concepts and relate them to the classroom!