Solved Problem: A Half-Price Sale on U.S. Treasury Bonds?

Supports: Money, Banking, and the Financial System, Chapter 3.
Image generated by ChatGPT of the U.S. Treasury building in Washington, DC

In a recent book review in the Wall Street Journal, financial analyst James Grant wrote: “The Treasury may indeed pay off every claim in freshly printed dollars. But 30-year Treasurys issued at the sub-2% yields prevailing in 2020 change hands today for less than 45 cents on the dollar.”

To illustrate Grant’s point: On May 15, 2020, the U. S. Treasury issued a 30-year bond with a $12.50 coupon and a face value, or par value, of $1,000. On October 6, the market price of the bond was $424.25. If you buy this bond today, you will receive a payment of $1,000 from the U.S. Treasury on May 15, 2050. The U.S. Treasury most recently issued 30-year bonds on August 17, 2026. Those 30-year bonds have a coupon of $51.25.

a. What does Grant mean by writing that 30-year Treasury bonds issued in 2020 “change hands today for less than 45 cents on the dollar”?

b. Why would anyone would be willing to sell you a bond for less than 50 percent of the amount the seller would receive by holding the bond to maturity?

Solving the Problem
Step 1: Review the chapter material. This problem is about why bond prices fluctuate, so you may want to review Money, Banking, and the Financial System, Chapter 3, “Interest Rates and Rates of Return,” particularly the section “What Happens to Bond Prices When Interest Rates Change?”

Step 2: Answer part a. by explaining what Grant meant by bonds changing hands at less than 45 cents on the dollar. By “changing hands” Grant is referring to buying and selling bonds in the bond market. By “less than 45 cents on the dollar,” Grant means that bonds with a face value of $1,000 are selling for less than $450.

Step 3: Answer part b. by explaining why someone would be willing to sell you a bond for only $450 even though the bond has a face value of $1,000. In the bond market, as bonds are bought and sold, bonds of the same characteristics should have the same yield, as measured by the yield to maturity on the bonds. The 30-year bonds the Treasury issued in August of this year currently have a yield to maturity of about of about 5.31%. (The yield to maturity on these bonds is greater than the bonds coupon rate of 5.125% because the prices of the bonds are currently less than $1,000.) As an investor, you would only be willing to buy the 30-year bonds the Treasury issued in 2020 with a coupon rate of 1.25% if the price of the bonds will result in your receiving a yield to maturity of 5.31%.

The expression that links the price of a coupon bond, P, to the yield to maturity on the bond, i, is:
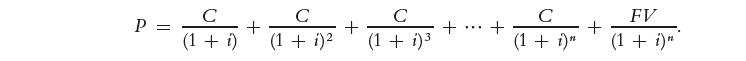
Keeping mind that the coupon, C, on a bond is fixed once the bond is issued, an increase in the yield to maturity must cause a decline in price of the bond. Because the gap in coupon rates between Treasury bonds issued in 2020 and in 2026 is so large, the 2020 bonds must have much lower prices in order to have the same yield to maturity.

Extra credit. The U.S. Treasury only started regularly issuing coupon bonds in the 1970s as the federal government began to run substantial budget deficits nearly every year. Prior to that, individuals rarely bought Treasury bonds with the exception of the tens of billions of “war bonds” the Treasury issued to raise funds during World War I and World War II.
Image from the American Museum of Natural History

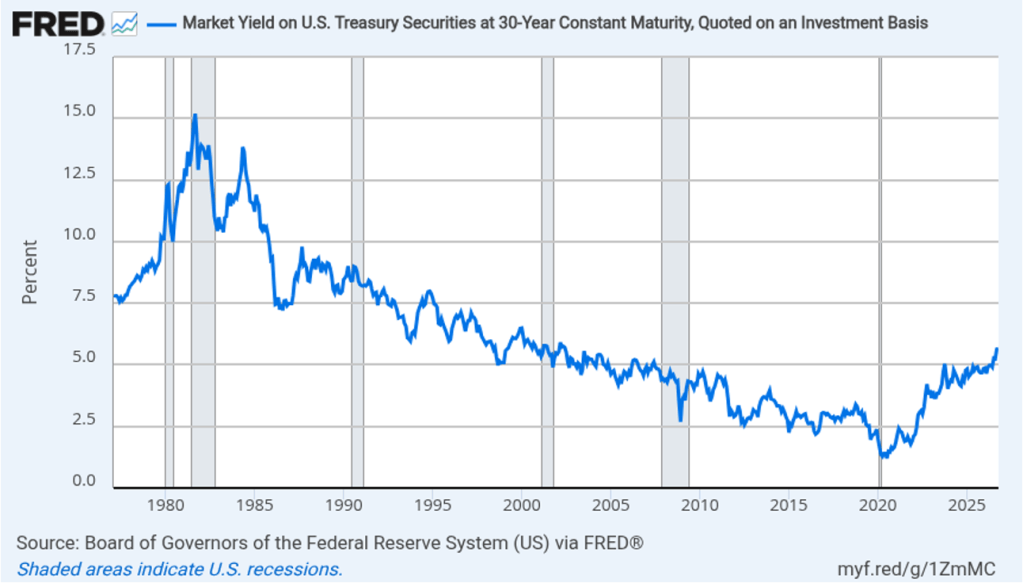
As the following figure shows, since the 1970s, the yields on 30-year Treasury bonds have changed dramatically over time, from more than 15% in 1981 to less than 2% in 2020. These variations in yields reflect the higher or lower coupon rates the Treasury needs to offer investors as a result of fluctuations in inflation and in other factors that affect the demand for bonds.
Solved Problem: Will Investors in Japan and Europe Buy the Increased Quantity of U.S. Treasury Bonds?

Supports: Macroeconomics, Chapter 18, Section 18.2;  Economics, Chapter 28, Section 28.2; and Essentials of Economics, Chapter 19, Section 19.6.

As the figure above shows, federal government debt, sometimes called the national debt, has been increasing rapidly in the years since the 2020 Covid pandemic. (The figure show federal government debt held by the public, which excludes debt held by federal government trust funds, such as the Social Security trusts funds.) The debt grows each year the federal government runs a budget deficit—that is, whenever federal government expenditures exceed federal government revenues. The Congressional Budget Office (CBO) forecasts large federal budget deficits over the next 30 years, so unless Congress and the president increase taxes or cut expenditures, the size of the federal debt will continue to increase rapidly. (The CBO’s latest forecast can be found here. We discuss the long-run deficit and debt situation in this earlier blog post.)

When the federal government runs a budget deficit, the U.S. Treasury must sell Treasury bills, notes, and bonds to raise the funds necessary to bridge the gap between revenues and expenditures. (Treasury bills have a maturity—the time until the debt is paid off by the Treasury—of 1 year or less; Treasury notes have a maturity of 2 years to 10 years; and Treasury bonds have a maturity of greater than 10 years. For convenience, we will refer to all of these securities as “bonds.”) A recent article in the Wall Street Journal discussed the concern among some investors about the ability of the bond market to easily absorb the large amounts of bonds that Treasury will have to sell. (The article can be found here. A subscription may be required.)

According to the article, one source of demand is likely to be European and Japanese investors.

“The euro and yen are both sinking relative to the dollar, in part because the Bank of Japan is still holding rates low and investors expect the European Central Bank to slash them soon. That could increase demand for U.S. debt, with Treasury yields remaining elevated relative to global alternatives.”

a. What does the article mean by “the euro and the yen are both sinking relative to the dollar”?

b. Why would the fact that U.S. interest rates are greater than interest rates in Europe and Japan cause the euro and the yen to sink relative to the dollar?

c. If you were a Japanese investor, would you rather be invested in U.S. Treasury bonds when the yen is sinking relative to the dollar or when it is rising? Briefly explain.

Solving the Problem

Step 1:  Review the chapter material. This problem is about the determinants of exchange rates, so you may want to review Macroeconomics, Chapter 18, Section 18.2, “The Foreign Exchange Market and Exchange Rates” (Economics, Chapter 28, Section 28.2; Essentials of Economics, Chapter 19, Section 19.6.)

Step 2: Answer part a. by explaining what it means that the euro and the yen “sinking relative to the dollar.” Sinking relative to the dollar means that the exchange rates between the euro and the dollar and between the yen and the dollar are declining. In other words, a dollar will exchange for more yen and for more euros.

Step 3: Answer part b. by explaining how differences in interest rates between countries can affect the exchange between the countries’ currencies. Holding other factors that can affect the attractiveness of an investment in a country’s bonds constant, the demand foreign investors have for a country’s bonds will depend on the difference in interest rates between the two countries. For example, a Japanese investor will prefer to invest in U.S. Treasury bonds if the interest rate is higher on Treasury bonds than the interest rate on Japanese government bonds. So, if interest rates in Europe decline relative to interest rates in the United States, we would expect that European investors will increase their investments in U.S. Treasury bonds. To invest in U.S. Treasury bonds, European investors will need to exhange euros for dollars, causing the supply curve for euros in exchange for dollars to shift to the right, reducing the value of the euro.

Step 4: Answer part c. by discussing whether if you were a Japanese investor, you would you rather be invested in U.S. Treasury bonds when the yen is sinking relative to the dollar or when it is rising.  In answering this part, you should draw a distinction between the situation of a Japanese investor who already owns U.S. Treasury bonds and one who is considering buying U.S. Treasury bonds. A Japanese investor who already owns U.S. Treasury bonds would definitely prefer to own them when the value of the yen if falling against the dollar. In this situation, the investor will receive more yen for a given amount of dollars the investor earns from the Treasury bonds. A Japanese investor who doesn’t currently own U.S. bonds, but is thinking of buying them, would want the value of the yen to be increasing relative to the dollar because then the investor would have to pay fewer yen to buy a Treasury bond with a price in dollars, all other factors being equal. (The face value of a Treasury bond is $1,000, although at any given time the price in the bond market may not equal the face value of the bond.) If the interest rate difference between U.S. and Japanese bonds is increasing at the same time as the value of the yen is decreasing (as in the situation described in the article) a Japanese investor would have to weigh the gain from the higher interest rate against the higher price in yen the investor would have to pay to buy the Treasury bond.


Macro Solved Problems on Treasury Bonds and Defining Inflation

Ernie Banks of the Chicago Cubs poses for a portrait circa 1963. (Photo by Louis Requena/MLB Photos)

With the owners of the Major Labor Baseball teams and the Major League Players Association having finally settled on a new collective bargaining agreement, the baseball season will soon begin. Ernie Banks, the late Hall of Fame shortstop for the Chicago Cubs, was known for his upbeat personality. However bad the weather might be at Chicago’s Wrigley Field, Banks would run on the field and say, “What a great day for baseball! Let’s play two.”

In honor of Ernie Banks, today let’s do two Solved Problems in macro. They both involve errors that students in principles courses often make. So, in that sense they would also work as Don’t Let This Happen to You features. 

Solved Problem 1.: Bond Yields and Bond Prices

An article in the Financial Times had the following headline:  “U.S. Government Bond Prices Drop Ahead of Federal Reserve Meeting.” The first sentence of the article reads: “U.S. government bond yields rose to multiyear highs on Monday ahead of this week’s Federal Reserve meeting ….”

a. When a media article mentions “U.S. government bonds,” what type of bonds are they referring to?

b. Is there a contradiction between the headline and the first sentence of the article? Is the article telling us that U.S. government bonds went up or down? Briefly explain.

Solving the Problem

Step 1:  Review the chapter material. This problem is about the inverse relationship between bond yields and bond prices, so you may want to review Macroeconomics, Chapter 6, Appendix, “Using Present Value” (Economics, Chapter 8, Appendix, “Using Present Value”). You may also want to review the discussion of U.S. Treasury bonds in Macroeconomics, Chapter 16, Section 16.6, “Deficits, Surpluses, and Federal Government Debt” (Economics, Chapter 26, Section 26.6, “Deficits, Surpluses, and Federal Government Debt”).

Step 2: Answer part a. by explaining what media articles are referring to when they use the phrase “U.S. government bonds.” As discussed in Chapter 16, Section 16.6, most of the bonds issued by the federal government of the United States are U.S. Treasury bonds. The Treasury sells these bonds to investors when the federal government doesn’t collect enough in tax revenues to pay for all of its spending. So, when the media refers to U.S. government bonds, without further explanation, the reference is always to U.S. Treasury bonds. 

Step 3: Answer part b. by explaining that there is no contradiction between the headline and the first sentence of the article. An important fact about bond markets is that when the price of a bond falls, the yield—or interest rate—on the bond rises. The reverse is also true: When the price of a bond rises, the yield on the bond falls.  The reason why this relationship holds is explained in the Appendix to Chapter 6: The price of a bond (or other financial asset) should be equal to the present value of the payments an investor receives from owning that asset. If you buy a U.S. Treasury bond, the price will equal the present value of the coupon payments the Treasury sends you during the life of the bond and the final payment to you by the Treasury of the principal, or face value of the bond. Remember that present value is the value in today’s dollars of funds to be received in the future. The higher the interest rate, the lower the present value of a payment to be received in the future. So a higher yield, or interest rate, on a bond results in a lower price of the bond because the higher yield reduces the present value of the payments to be received from the bond.

Therefore, whenever the yield on a bond rises, the price of the bond must fall (and whenever the yield on a bond falls, the price of the bond must rise. So, we can conclude that the headline of the Financial Times article and the first sentence of the article are consistent, not contradictory:  Because the prices of Treasury bonds fell, the yields on the bonds must have risen.

Source: Nicholas Megaw, Naomi Rovnick, George Steer, and Hudson Lockett, “U.S. Government Bond Prices Drop Ahead of Federal Reserve Meeting,” ft.com, March 14, 2022.

Solved Problem 2: Being Careful about the Definition of Inflation

An article in the New York Times contrasted inflation during the 1970s with inflation today:

“Price increases had run high for more than a decade by the time Mr. Volcker became chair [of the Federal Reserve Board of Governors] in 1979 …. Shopper expected prices to go up, businesses knew that, and both acted accordingly. This time, inflation has been anemic for years (until recently), and most consumers and investors expect costs to return to lower levels before long, survey and market data show.”

a. What does the article mean by “inflation has been anemic for years”?

b. In the last sentence what “costs” is the article referring to?

c. Is the article correctly using the definition of inflation in the last sentence? Briefly explain.

Solving the Problem

Step 1:  Review the chapter material. This problem is about the definition of inflation, so you may want to review Macroeconomics, Chapter 9, Section 9.4, “Measuring Inflation” (Economics, Chapter 20, Section 20.4, “Measuring Inflation”).

Step 2: Answer part a. by explaining what the phrase “inflation has been anemic for years” means. Anemia is a medical disorder that usually has the symptom of fatigue. So, the word “anemic” is often used to mean weak. The article is arguing that until recently, the inflation rate had been weak, or slow.  

Step 3: Answer part b. by explaining what the article is referring to by “costs.” Economists typically use the word costs for the amount that firm pays to produce a good—labor costs, raw material costs, and so on. Here, though, the article is using “costs” to mean “prices.”  Costs is often used this way in everyday conversation: “I didn’t buy a new car because they cost too much.” Or: “Has the cost of a movie ticket increased?” 

Step 4: Answer part c. by explaining whether the article is correctly using the definition of inflation. In writing “consumers and investors expect costs to return to lower levels” the article is making a common mistake. The article seems to mean that consumers and investors expect that the rate of inflation will be lower in the future. But even if the rate of inflation declines from nearly 8 percent in early 2022 to, say, 3 percent in 2023, prices will still be increasing. So, prices (“costs” in the sentence) will still be higher next year even if the rate of inflation is lower. In other words, even if the rate of increase in prices—inflation—declines, the price level will still be higher. 

It’s a common mistake to think that a decline in the inflation rate means that prices will be lower, when actually prices will still be increasing, just more slowly.

Source: Jeanna Smialek, “Powell Admires Volcker. He May Have to Act Like Him,” New York Times, March 14, 2022.