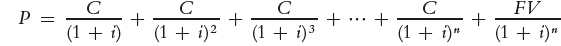Solved Problem: A Half-Price Sale on U.S. Treasury Bonds?

Supports: Money, Banking, and the Financial System, Chapter 3.
Image generated by ChatGPT of the U.S. Treasury building in Washington, DC

In a recent book review in the Wall Street Journal, financial analyst James Grant wrote: “The Treasury may indeed pay off every claim in freshly printed dollars. But 30-year Treasurys issued at the sub-2% yields prevailing in 2020 change hands today for less than 45 cents on the dollar.”

To illustrate Grant’s point: On May 15, 2020, the U. S. Treasury issued a 30-year bond with a $12.50 coupon and a face value, or par value, of $1,000. On October 6, the market price of the bond was $424.25. If you buy this bond today, you will receive a payment of $1,000 from the U.S. Treasury on May 15, 2050. The U.S. Treasury most recently issued 30-year bonds on August 17, 2026. Those 30-year bonds have a coupon of $51.25.

a. What does Grant mean by writing that 30-year Treasury bonds issued in 2020 “change hands today for less than 45 cents on the dollar”?

b. Why would anyone would be willing to sell you a bond for less than 50 percent of the amount the seller would receive by holding the bond to maturity?

Solving the Problem
Step 1: Review the chapter material. This problem is about why bond prices fluctuate, so you may want to review Money, Banking, and the Financial System, Chapter 3, “Interest Rates and Rates of Return,” particularly the section “What Happens to Bond Prices When Interest Rates Change?”

Step 2: Answer part a. by explaining what Grant meant by bonds changing hands at less than 45 cents on the dollar. By “changing hands” Grant is referring to buying and selling bonds in the bond market. By “less than 45 cents on the dollar,” Grant means that bonds with a face value of $1,000 are selling for less than $450.

Step 3: Answer part b. by explaining why someone would be willing to sell you a bond for only $450 even though the bond has a face value of $1,000. In the bond market, as bonds are bought and sold, bonds of the same characteristics should have the same yield, as measured by the yield to maturity on the bonds. The 30-year bonds the Treasury issued in August of this year currently have a yield to maturity of about of about 5.31%. (The yield to maturity on these bonds is greater than the bonds coupon rate of 5.125% because the prices of the bonds are currently less than $1,000.) As an investor, you would only be willing to buy the 30-year bonds the Treasury issued in 2020 with a coupon rate of 1.25% if the price of the bonds will result in your receiving a yield to maturity of 5.31%.

The expression that links the price of a coupon bond, P, to the yield to maturity on the bond, i, is:
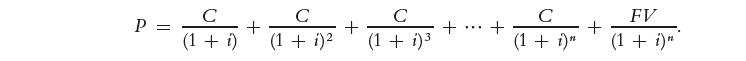
Keeping mind that the coupon, C, on a bond is fixed once the bond is issued, an increase in the yield to maturity must cause a decline in price of the bond. Because the gap in coupon rates between Treasury bonds issued in 2020 and in 2026 is so large, the 2020 bonds must have much lower prices in order to have the same yield to maturity.

Extra credit. The U.S. Treasury only started regularly issuing coupon bonds in the 1970s as the federal government began to run substantial budget deficits nearly every year. Prior to that, individuals rarely bought Treasury bonds with the exception of the tens of billions of “war bonds” the Treasury issued to raise funds during World War I and World War II.
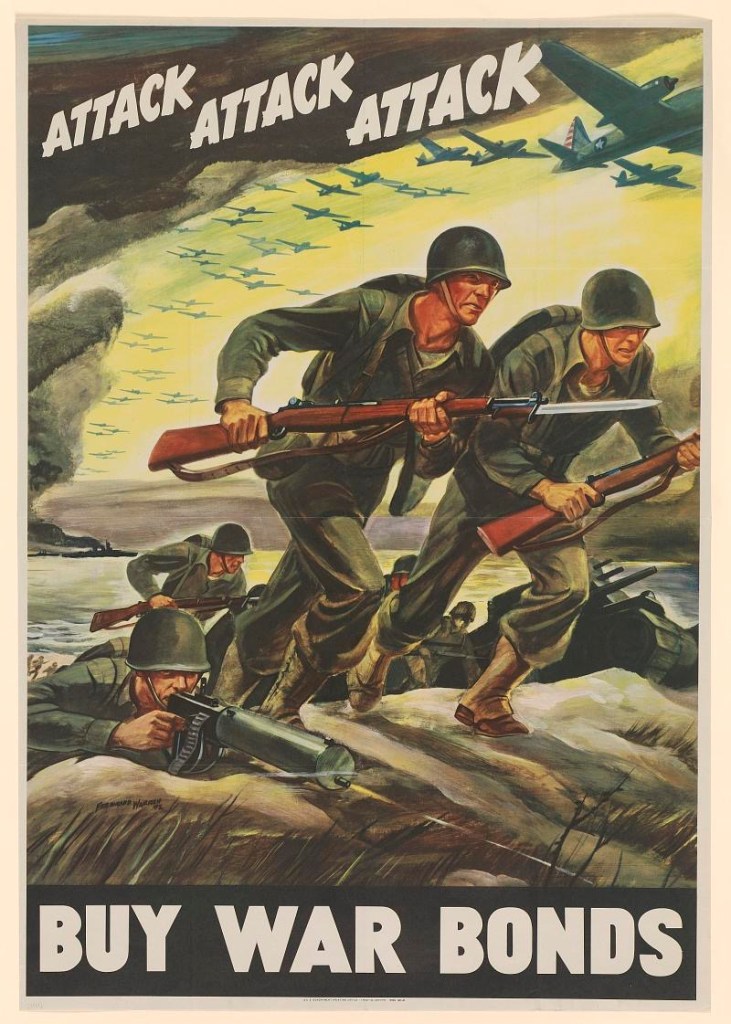
Image from the American Museum of Natural History

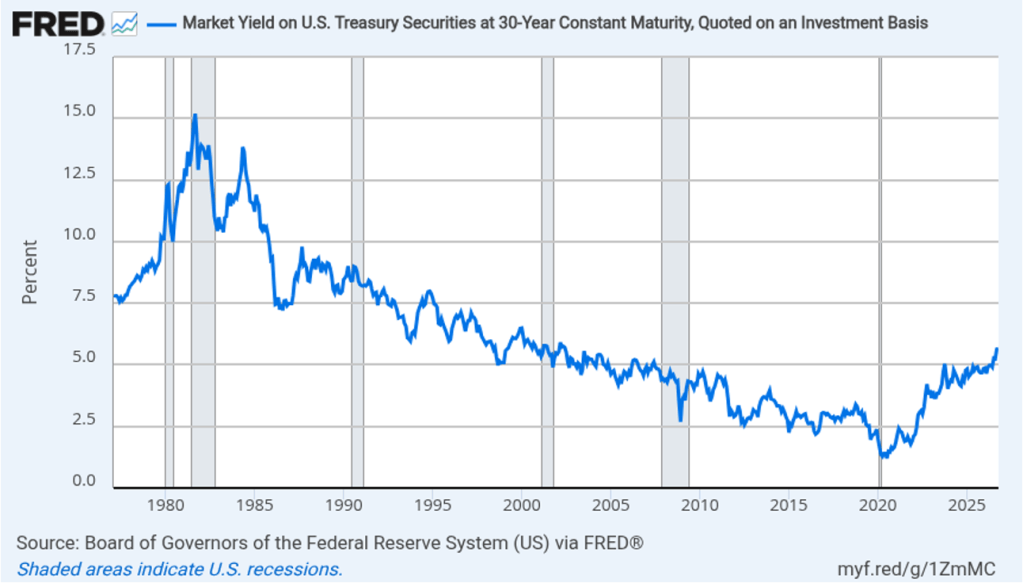
As the following figure shows, since the 1970s, the yields on 30-year Treasury bonds have changed dramatically over time, from more than 15% in 1981 to less than 2% in 2020. These variations in yields reflect the higher or lower coupon rates the Treasury needs to offer investors as a result of fluctuations in inflation and in other factors that affect the demand for bonds.
Solved Problem: Why Do Bond Prices and Bond Yields Move Inversely?

Supports: Money, Banking, and the Financial System, Chapter 3, and Microeconomics, Chapter 8, Appendix.

Image created by ChatGPT

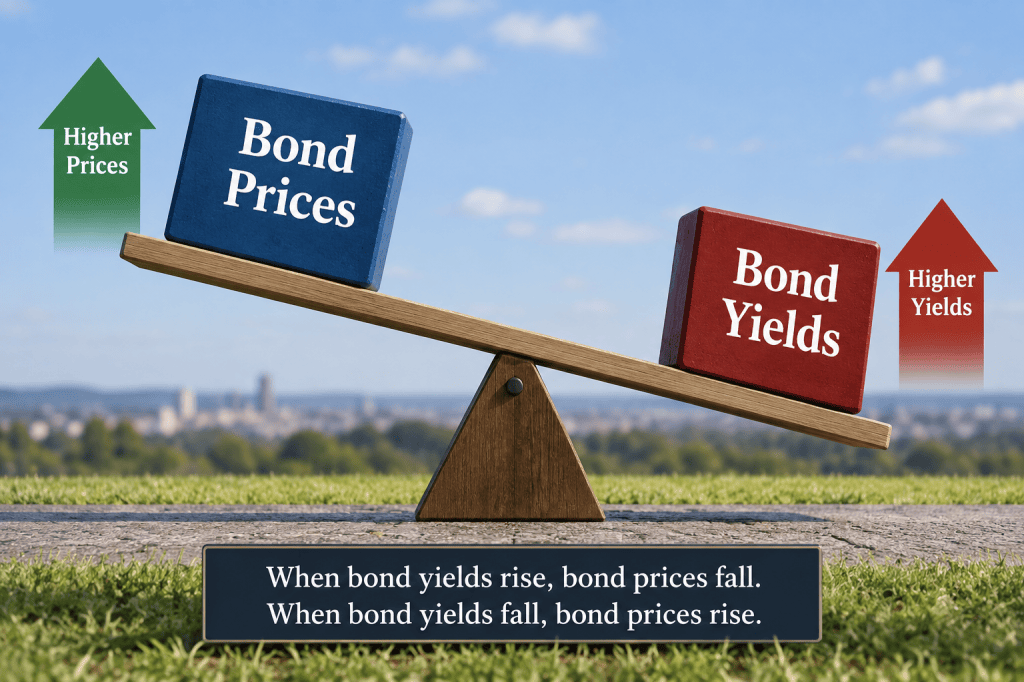
A recent article in the Wall Street Journal was titled “A Primer on Why Bond Prices Fall When Yields Rise.” A student reading the title of the article asks, “How can that be right? Investors would prefer to own bonds that have higher yields, so when the yields on bonds rise, investors should demand more of them. When the demand for something goes up, the price increases. Therefore, bond yields and bond prices should go up (or down) together.” Briefly explain the error in this student’s reasoning.

Solving the Problem
Step 1: Review the chapter material. This problem is about the relationship between bond yields and bond prices, so you may want to review Money, Banking, and the Financial System, Chapter 3 (for a complete discussion) or Microeconomics, Chapter 8, Appendix (for a brief discussion).

Step 2: Solve the problem by explaining what is wrong with the argument that if bond yields increase, so will bond prices, and if bond yields decrease, so will bond prices. In solving the problem, we should first consider the sometimes confusing number of “interest rates” on a coupon bonds. Coupon bonds pay interest in the form of coupons, which are usually quoted on an annual basis although typically paid twice per year. For example, Apple may issue a bond that pays a coupon of $47.50. The coupon rate on this bond is quoted per $1,000 of face value, or par value, which in this case would be 4.750%.

Bonds, like other financial assets such as shares of stock, are bought and sold in financial markets. A key point is that in financial markets, bonds with similar characteristics—including the same level of default risk, the same liquidity, and the same tax treatment of the bonds’ coupons—should provide investors with the same expected return. If this condition didn’t hold—for instance, if a bond issued by Apple was expected to provide a higher return than comparable bonds—then investors would increase their demand for the Apple bond, forcing up its price until its yield fell by enough to make its expected return the same as on other comparable bonds.

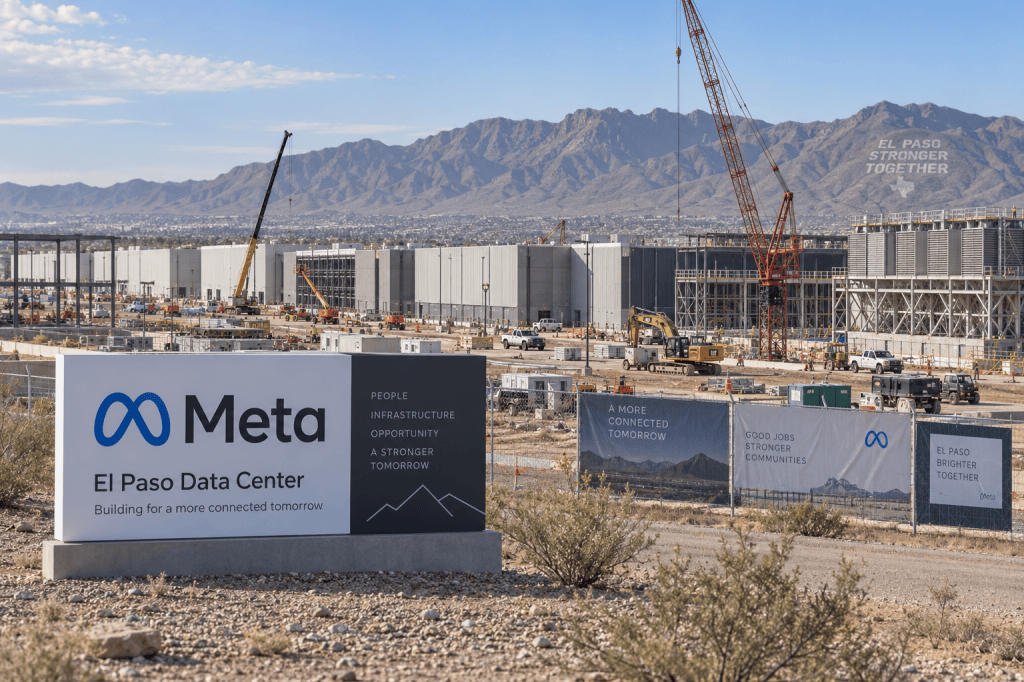
The price of a bond can fluctuate depending on how its coupon rate compares to the coupon rates on newly issued bonds, changes in investors’ expectations of future inflation, changes in investors’ expectations of the default risk of the bond, and other factors. For example, an article in the Wall Street Journal reported that, “Lenders on Monday demanded higher yields on bonds from a new data-center project in El Paso, Texas, leased by Meta compared with a similar project last year.” According to the article, the reason for the higher yields was that investors had raised their estimates of the default risk on bonds issued to fund data centers. Investors needed higher yields on bonds to compensate them for the higher default risk.

An image created by ChatGPT of Meta’s data-center complex under construction in El Paso, Texas.

What happens to the prices of existing bonds when newly issued bonds have higher coupon rates? Keeping in mind that, because the coupon rate on a bond is fixed and won’t change after the bond has been issued, the only way that the yield on a bond can change is if the price of the bond declines. By “yield” we are here referring to the yield to maturity, which is the best way of calculating the yield on a bond and which is ordinarily what economists and investors mean when they refer to the interest rate on a bond.

Formally, the yield to maturity is defined as the interest rate that makes the present value of the payments from the bond equal to the bond’s current price. In the following expression, where C is the coupon on the bond, FV is the face value of the bond, and n is the number of years until the bond matures, i is the yield to maturity.

The arithmetic of this expressions shows that if the yield to maturity increases, because, for example, the coupon rate on similar newly issued bonds are higher than the coupon rate on this bond, the price of the bond must decline. The economics of this expression is that an increase in the yield to maturity reduces the present value of a bond’s coupon payments and face value.

The reverse happens if the yield to maturity on a bond falls: The price of the bond will rise as a matter of arithmetic. As a matter of economics, a lower yield to maturity increases the present value of a bond’s coupon payments and face value.

So, although the student’s assertion seems logical, the economics of bond prices shows that the prices and yields on bonds move inversely.