Is It Fine to Bring an Iced Coffee to a Job Interview? Jadrian Wooten Provides an Economic Analysis

Image created by ChatGPT

There’s a vigorous debate on social media over whether it’s acceptable for a job candidate to bring an iced coffee to an interview. In his always interesting “Monday Morning Economist” Substack, Jadrian Wooten provides an economic analysis based on the signaling theory of Nobel laureate Michael Spence of New York University and Stanford. 
Photo of Michael Spence from gsb.stanford.edu

Signaling can be important in markets affected by the problem of asymmetric information, which occurs when one party to an economic attraction has less information than the other party. As we discuss in Microeconomics, Chapter 7, George Akerlof—who was awarded the Nobel Prize in Economics in the same year as Spence—provided a classic early analysis of asymmetric information in the used car market. The seller of a used car will know whether a failure to maintain the car by, for instance, regularly changing its oil, has caused the car’s engine to suffer damage that even an auto mechanic may have difficulty detecting.
Image created by ChatGPT

Asymmetric information in a market can lead to adverse selection in which one party to a transaction—in this case, a car seller—takes advantage of knowing more than the other party—in this case, a car buyer. For example, suppose you intend to buy a car, and you contact people who have listed cars on Facebook Marketplace or Craigslist. You have no good way of determining whether a car listed has been well maintained, a “creampuff,” or poorly maintained, a “lemon.” If you had full information on the car you would offer to pay $25,000 to buy a creampuff, but only $15,000 to buy a lemon. Because of this uncertainty, you might offer to pay $20,000 for a car of unknown quality. Your offer seems reasonable to you, given your uncertainty about the quality of the car. However, a seller who knows the quality of the car will be reluctant to accept your offer if the car is a creampuff, but happy to accept your offer if the car is a lemon. The result is that cars offered for sale are more likely to be lemons than creampuffs. Or, in other words, because of asymmetric information, the market has adversely selected the cars that will be offered for sale.

Asymmetric information also exists in the job market. When you apply for a job, you know much more about how hard you will work and how developed your relevant skills are than does the company you are applying to. Suppose that the company would pay you a salary of $60,000 per year if the company was sure that you would turn out to be a hard worker, but only $40,000 if the company believed that you would turn out be a slacker. Because of this uncertainty, the company might offer a starting salary of $50,000. That salary would be attractive to slackers but unattractive to hard workers. As a result, the company might find that most of the people applying to work for them are slackers.

Michael Spence argues that in markets in which asymmetric information is important, economic agents will have an incentive to signal that the good or service they are selling is of higher quality than buyers might otherwise think. For example, a firm selling used cars may invest in making their dealership clean and attractive or by offering warranties on the cars they sell. The firms are attempting to signal buyers that the cars they are selling are creampuffs rather than lemons.

One strong signal you can send to employers when you apply for jobs is that you have earned a college degree. There has been a long debate among economists over whether a college degree indicates to potential employers that you have accumulated knowledge and skills in college—in other words, your human capital is higher than for non-college graduates—or whether a college degree is mainly a signal to potential employers that you are likely to be a hard worker because you have completed a task as difficult as obtaining a college degree.
Image created by ChatGPT

The sheepskin effect is often raised by economists arguing that for potential employers your having college degree is more about signaling than about the human capital you have accumulated in college. If you complete three years of college but drop out in your fourth year before earning your degree, you have likely learned almost as much, and have nearly the same level of human capital, as someone who has taken the few additional classes needed to earn a degree. In the job market, though, you are likely to earn significantly less than someone who has a college degree. This result makes it seem that a college degree is primarily a signal to employers that you have the characteristics of a good employee. Note: The sheepskin effect gets its name from the fact that years ago college diplomas were often printed on material derived from animal skins.

This older blog post by Noah Smith, including the responses from Bryan Kaplan of George Mason University, covers the main points raised in the debate over whether the value of a college degree is mainly the signal it sends to potential employers.

So, what signal are you sending when you bring an iced coffee to a job interview? Jadrian Wooten’s Substack post explains.
The Southern California Wildfires and Problems in the Insurance Industry 

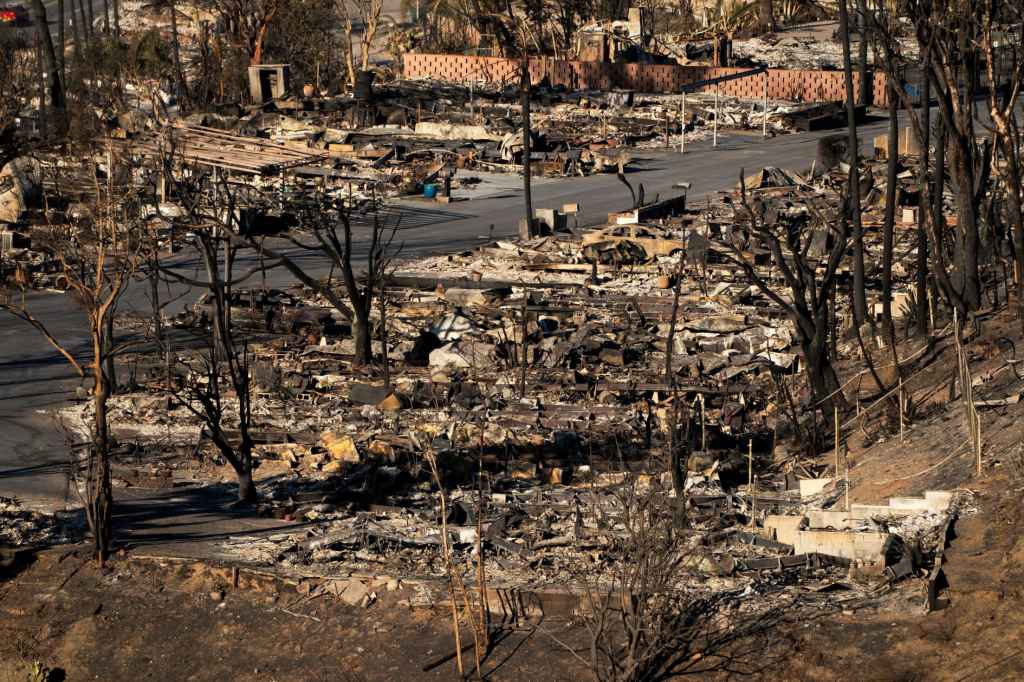
Fire damage in the Pacific Palisades. (Photo from Reuters via the Wall Street Journal)

As of January 15, the series of devastating wildfires in Southern California have killed at least 25 people and destroyed billions of dollars’ worth of homes and businesses. Adding to the tragedy is the fact that many homeowners aren’t fully insured against the damage. As a result, they lack the necessary funds to rebuild their homes. Unfortunately for these people, the market for fire insurance in California hasn’t been working well. 

In the United States, regulation of property and casualty insurance occurs at the state level with regulations differing substantially across states. In California, insurance companies face an unusually long regulatory process to receive permission to increase the premiums they charge. The delays in raising premiums have contributed to companies not renewing property insurance policies in some areas, such as those prone to wildfires. In these areas, the payouts the companies expect to make have been higher than the premiums that California regulators have allowed companies to charge policyholders.

The wildfires have ravaged the Pacific Palisades neighborhood of Los Angeles . Although housing prices in the neighborhood are among the highest in the country, an analysis by the Reuters news agency showed that: “Measured against home values, insurance costs are cheaper in the Palisades than in 97% of U.S. postal codes …” For example, the median insurance premium in the Pacific Palisades was “less than residents paid in Glencoe, Illinois, an upscale suburb of Chicago where homes are two-thirds cheaper and the risk of wildfire is minimal.”

Catastrophe modeling is a way of statistically forecasting the probability of events—such as floods or wildfires—occurring that would sharply increase claims by policyholders. Regulations had barred insurance companies from using catastrophe modeling to justify increases in premiums. (State regulators lifted the prohibition on the use of catastrophe modeling shortly before the fires.) These restrictions made it more difficult for companies to charge risk-based premiums, which are based on the probability that a policyholder will file a claim.

Insurance markets can experience adverse selection problems because the people most eager to buy insurance are those with highest probability of requiring an insurance payout. Insurance companies attempt to reduce adverse selection problems by, among other things, charging risk-based premiums. Limiting the ability of insurance companies to charge risk-based premiums increased the adverse selection problems the companies face. To cope with the problem of companies not renewing policies, regulators began requiring companies to renew policies in some Zip codes, particularly those that were in or near areas that had experienced wildfires. This policy further increased adverse selection.

By 2023, some insurers, including State Farm and Allstate—which are two of the largest property insurers in the United States—had decided that they were unlikely to be able cover their costs from offering property insurance policies in California and stopped writing policies in the state. Policyholders who are unable to obtain a policy from a private insurance company typically buy a policy offered through the Fair Access to Insurance Requirements (FAIR) Plan. The FAIR Plan is sponsored by the state government, although operated by private insurance companies. The premiums charged for a FAIR Plan policy are significantly higher than the premiums charged for a traditional policy. Despite the higher premiums, the number of FAIR Plan policies doubled between 2020 and 2025, reaching nearly 500,000. 

The FAIR Plan lacks sufficient funds to pay the claims from policyholders who had lost their homes or businesses in the Southern California wildfires. To cover the deficit, the FAIR Plan will assess private insurance companies, who, in turn, will raise premiums charged to their other policyholders. In this way, some of the costs from the wildfires will be borne by all property insurance policyholders in California, even if they live far from the areas affected by the wildfires.

We discuss moral hazard in insurance markets in Microeconomics and Economics, Chapter 7 (and in Money, Banking, and the Financial System, Chapter 11). In general, moral hazard refers to actions people take after they have entered into a transaction that make the other party to the transaction worse off. Moral hazard in insurance markets occurs when people change their behavior after becoming insured. The way that the insurance market is regulated in California and, in particular, the way that the FAIR Plan is administered increases moral hazard because people who own homes or businesses in areas with a greater risk of damage from wildfires don’t pay premiums that fully reflect that greater risk. In other words, more people live in fire prone areas in California than would do so if the premiums on their insurance policies fully reflected the probability of their making a claim.

Whether, following the wildfires, the California legislature will change the regulations governing the insurance market is unclear at this point. As an insurance agent quoted by the Wall Street Journal put it: “We are in uncharted territory.”