
Image created by ChatGPT
The Bureau of Economic Analysis (BEA) released two reports this morning (September 30). One report indicated that economic growth was higher in the second quarter of 2026 than the BEA had previously estimated. The other report indicated that inflation as measured by the percentage increase in personal consumption expenditures (PCE) price index was lower than expected.
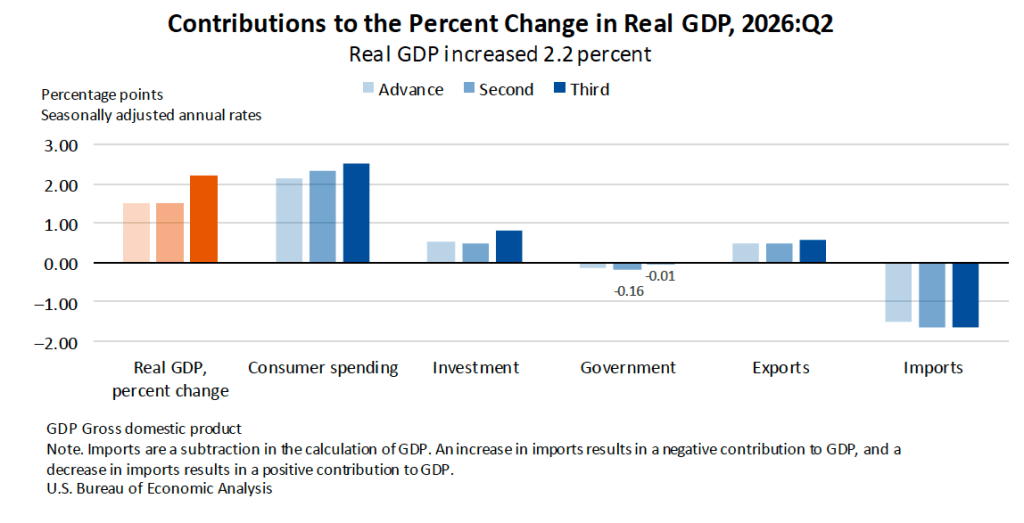
The BEA’s latest estimate is that real GDP increased at an annual rate of 2.2 percent in the second quarter (May, June, and July) of 2026. That is a sharp upward revision of the BEA’s previous estimate that real GDP had increased at an annual rate of 1.5 percent in the second quarter. The following figure from the report shows that upward revisions of investment, consumer spending, and government spending account for the upward revision of real GDP growth. The figure shows the BEA’s advance (original estimate) and two subsequent revised estimates. The BEA revises its estimates of real GDP growth as over time as it collects more complete and accurate data on growth in the components of GDP.
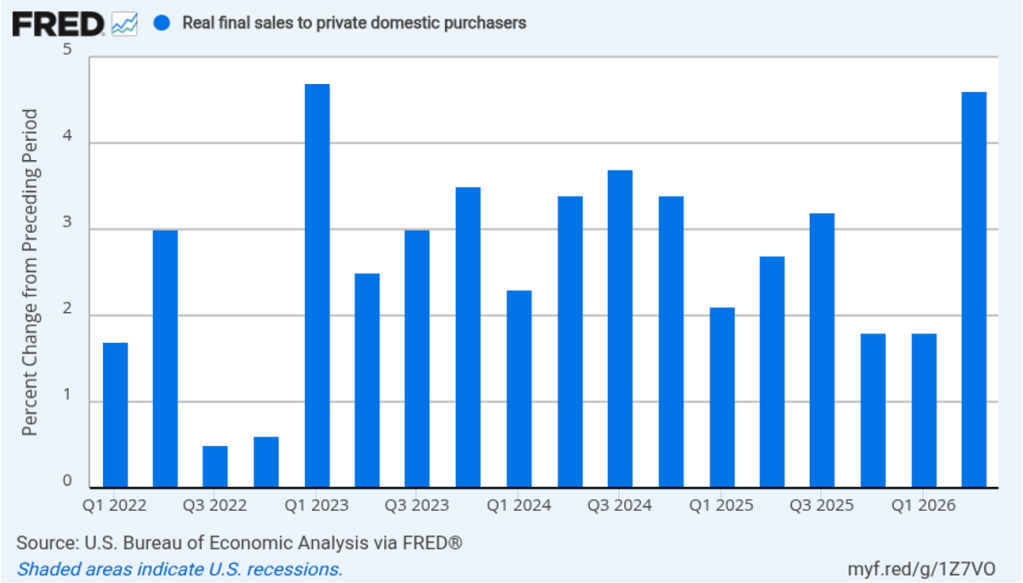
As we’ve discussed in previous blog posts, to better gauge the state of the economy, Federal Reserve policymakers often prefer to strip out the effects of imports, inventory investment, and government expenditures—which can be volatile—by looking at real final sales to private domestic purchasers, which includes only spending by U.S. households and firms on domestic production. As the following figure shows, real final sales to domestic purchasers increased at an annual rate of 4.6 percent in the second quarter, revised upward from 4.4 percent. The growth rate in real final sales to domestic purchasers was more than twice the growth rate of real GDP, as well as much higher than the U.S. economy’s expected long-run annual real growth rate of 1.8 percent. So estimated growth in real final sales to domestic purchasers indicates that the U.S. economy is expanding more rapidly than is indicated by estimated growth in real GDP. Typically, growth in real final sales to domestic purchasers is steadier than growth in real GDP and is likely a better indicator of the underlying growth rate in the economy.
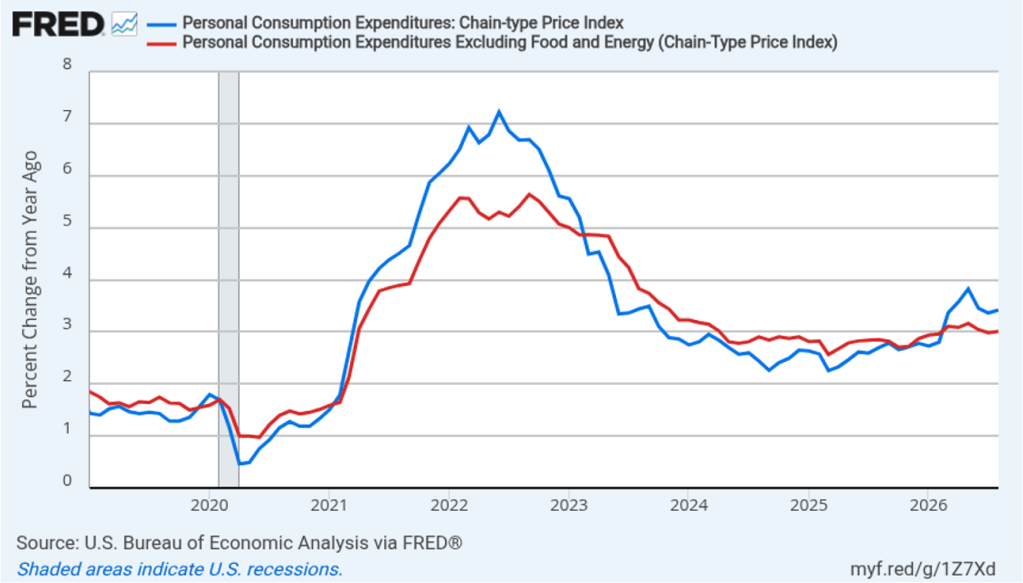
The BEA’s “Personal Income and Outlays” report this morning included monthly data on the personal consumption expenditures (PCE) price index. The Fed relies on annual changes in the PCE price index to evaluate whether it’s meeting its 2 percent annual inflation target. As we noted in an earlier blog post, Fed Chair Kevin Warsh indicated in his press conference following the July meeting of the Federal Open Market Committee (FOMC) that the committee intended to continue using the PCE price index as its gauge of inflation, although that decision would be revisited early next year. Some analysts have interpreted Warsh’s statement that the decision would be revisited next year as an indication that he favored moving to a measure that would show lower rates of inflation than those shown by the PCE.
The following figure shows headline PCE inflation (the blue line) and core PCE inflation (the red line)—which excludes energy and food prices—for the period since January 2019, with inflation measured as the percentage change in the PCE from the same month in the previous year. In August, headline PCE inflation was 3.4 percent, unchanged from July. Core PCE inflation in August was 3.0 percent, also unchanged from July. Headline and core PCE inflation were both lower than forecast by economists surveyed by FactSet. Both headline PCE inflation and core PCE inflation remain well above the Fed’s 2 percent annual inflation target.
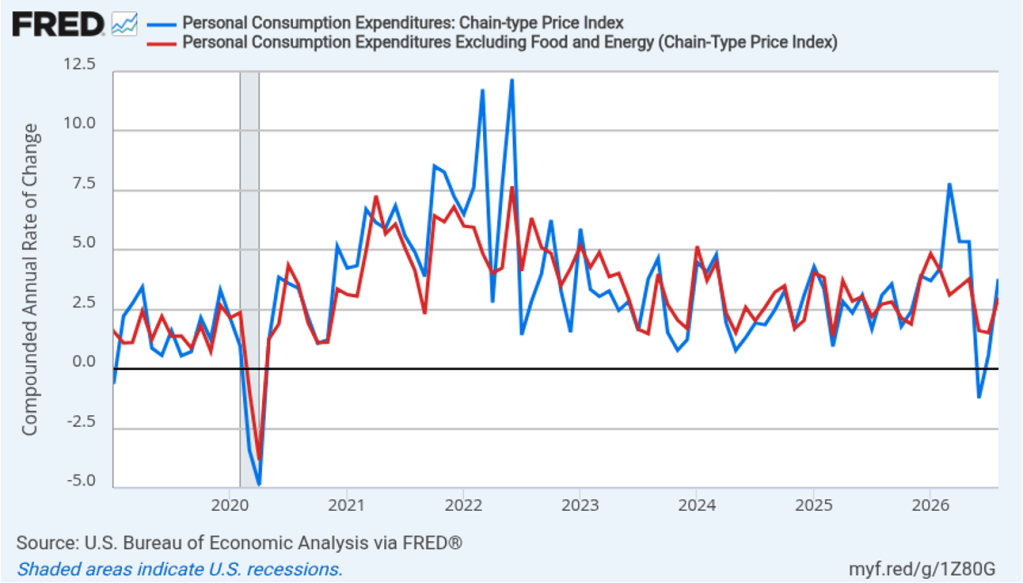
The following figure shows headline PCE inflation and core PCE inflation calculated by compounding the current month’s rate over an entire year. (Often referred to as 1-month inflation.) Measured this way, headline PCE inflation increased from 0.6 in July to 3.8 percent in August. Core PCE inflation increased from 1.5 percent in July to 3.0 percent in August. In contrast with the 12-month inflation rates, the 1-month inflation rates show noticeable acceleration in inflation during August. Of course, it’s important not to overinterpret the data from a single month.
Fed policymakers believe that inflation in non-market services can skew PCE inflation. Non-market services are services whose prices the BEA imputes rather than measures directly. For instance, the BEA assumes that prices of financial services—such as brokerage fees—vary with the prices of financial assets. So that if stock prices rise, the prices of financial services included in the PCE price index also rise. Former Fed Chair Jerome Powell has argued that these imputed prices “don’t really tell us much about … tightness in the economy. They don’t really reflect that.” The following figure shows 12-month headline inflation (the blue line) and 12-month core inflation (the red line) for market-based PCE. (The BEA explains the market-based PCE measure here.)
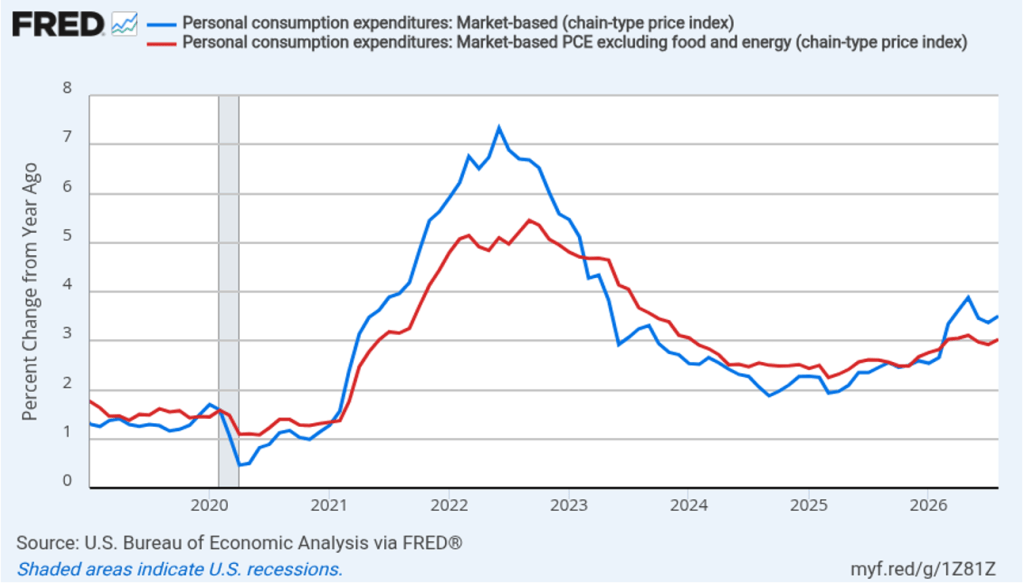
Headline market-based PCE inflation was 3.5 percent in August, up slightly from 3.4 percent July. Core market-based PCE inflation was 3.0 percent in August, up from 2.9 percent in July. So, both market-based measures show inflation in August remaining well above the Fed’s 2 percent target.
Fed Chair Kevin Warsh argued in testimony at his confirmation hearing before the Senate that the Fed should stop relying on headline PCE inflation: “The measures [of inflation] I prefer are looking at things that are called trimmed averages. We take out all of the tail-risks, all of the one-off items, and we ask ourselves whether the generalized change in prices is having second-order effects on the economy.”
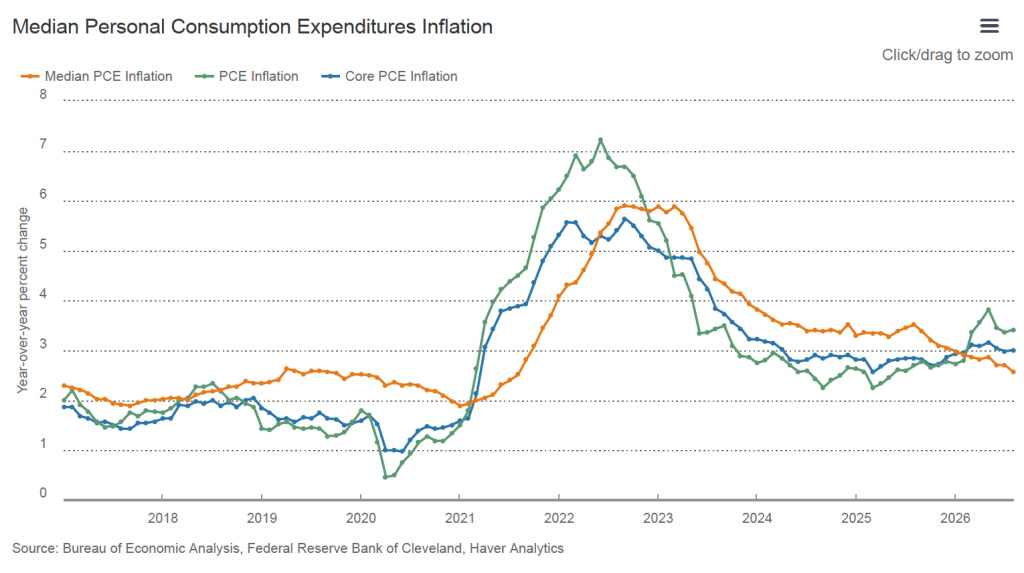
Trimmed-mean PCE inflation drops the 31 percent of goods and services with the highest inflation rates and the 24 percent of goods and services with the lowest inflation rates. A closely related measure, median PCE inflation, is calculated by listing the inflation rate in each individual good or service included in the PCE and identifying the inflation rate of the good or service that is in the middle of the list—that is, the inflation rate in the price of the good or service that has an equal number of higher and lower inflation rates.
The following figure shows 12-month headline PCE inflation the (blue line), core PCE inflation (the red line) and trimmed-mean PCE inflation (the green line). Trimmed-mean PCE inflation in August was 2.2 percent, well below both headline and core PCE inflation.

The following figure from the website of the Federal Reserve Bank of Cleveland shows headline PCE inflation (the green line), core PCE inflation (the blue line), and median PCE inflation (the brown line). In August, median PCE inflation was 2.6 percent, which was down from 2.7 percent in July. So Warsh has a point that these two measures of inflation, which are less affected by particularly high or low rates of inflation in some goods and services, indicate that inflation has been running below the Fed’s currently preferred measure. But these measures also show inflation still running well above the Fed’s 2 percent annual inflation target.
Today’s macro data releases appear to have caused of investors who buy and sell federal funds futures contracts to believe that the Federal Open Market Committee (FOMC) is now less likely to raise its target for the federal funds rate at the committee’s next meeting on October 27–28. Trading on the federal funds futures market this afternoon implies that the probability of a target rate increase at that meeting is 39.3 percent, down from a probability of 50.9 percent yesterday.

