
Image created by ChatGPT
This morning (October 2), the Bureau of Labor Statistics (BLS) released its “Employment Situation” report (often called the “jobs report”) for September. The August jobs report had showed an unexpectedly large increase in employment, while the September report shows an unexpectedly small increase in employment.
The jobs report has two estimates of the change in employment during the month: one estimate from the establishment survey, often referred to as the payroll survey, and one from the household survey. As we discuss in Macroeconomics, Chapter 9, Section 9.1 (Economics, Chapter 19, Section 19.1), many economists and Federal Reserve policymakers believe that employment data from the establishment survey provide a more accurate indicator of the state of the labor market than do the household survey’s employment and unemployment data. (The groups included in the employment estimates from the two surveys are somewhat different, as we discuss in this post.)
The BLS is housed in the Suitland Federal Center in Maryland. (Image created by ChatGPT)
According to the establishment survey, there was a net increase of only 29,000 nonfarm jobs during September. Economists surveyed by the Wall Street Journal had forecast an increase of 90,000 jobs. Economists surveyed by FactSet had forecast a net increase of 95,000 jobs. The BLS revised downward its previous estimates of employment in July and August by a combined 60,000 jobs. The estimate of the net employment change in July was revised from an increase of 21,000 to a decrease of 10,000. (The BLS notes that: “Monthly revisions result from additional reports received from businesses and government agencies since the last published estimates and from the recalculation of seasonal factors.”)
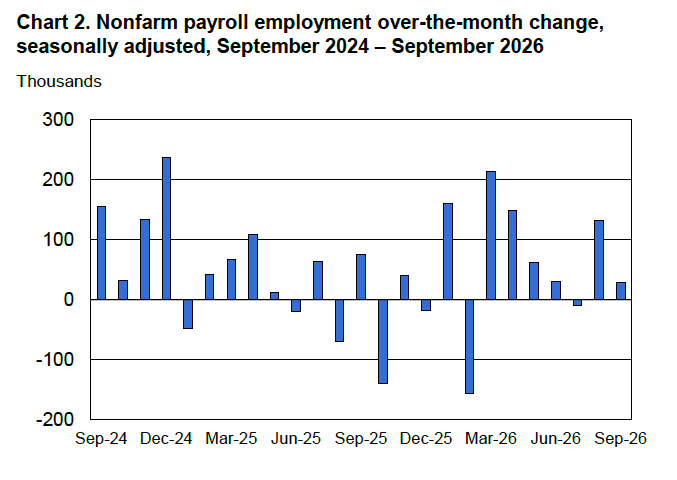
The following figure from the jobs report shows the net change in nonfarm payroll employment for each month in the last two years. The figure shows that since peaking in March with a net increase of 214,000 jobs, job growth slowed markedly over the following four months, then strongly rebounding in August, before returning to slower growth in September. In 2026, monthly net employment growth has averaged 68,000. That is much higher than the 2025 average monthly employment growth of only 10,000, but well below the 2024 average monthly employment growth of 122,000.
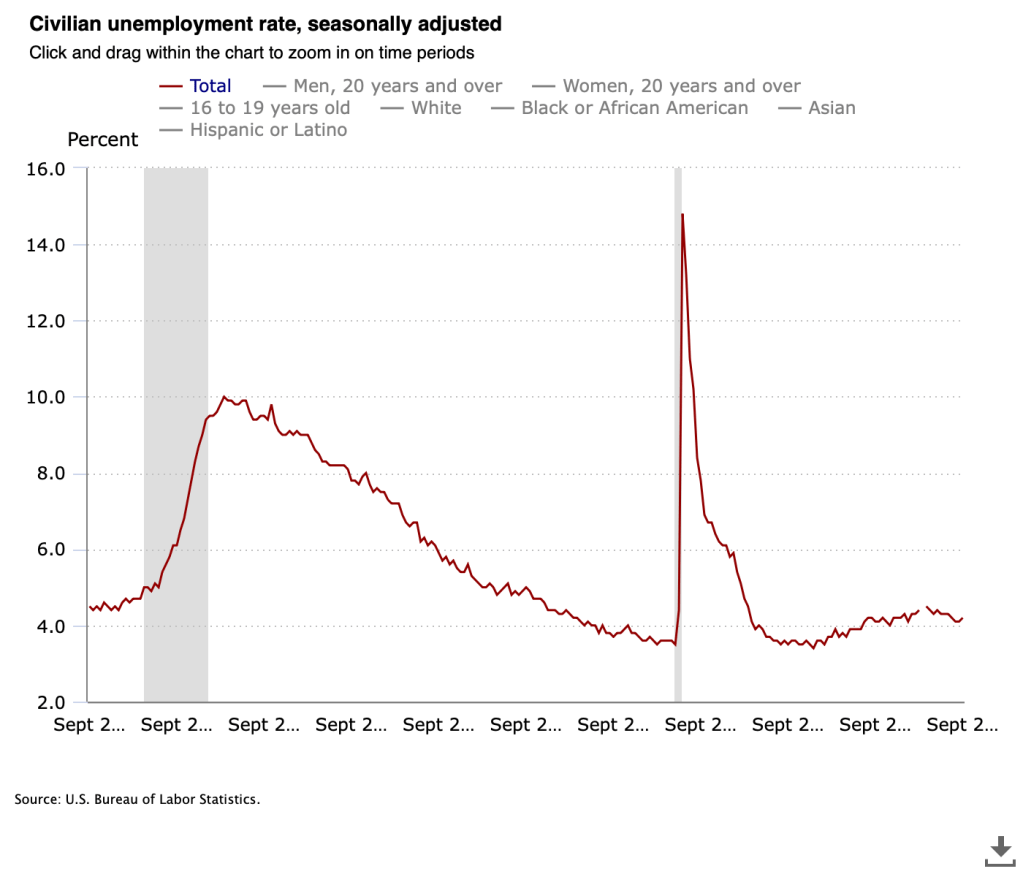
The unemployment rate, which is calculated from data in the household survey, was 4.2 percent in September, up slightly from 4.1 percent in August. The estimated size of the labor force, the number of workers employed, and the number of workers unemployed all increased in September. The following figure shows that the unemployment rate has been remarkably stable over the past year and a half, staying between 4.0 percent and 4.4 percent in each month since June 2024. The Federal Open Market Committee’s most recent estimate of the natural rate of unemployment—the normal rate of unemployment over the long run—is 4.2 percent. So, currently the unemployment rate is equal to that estimate of the natural rate. (We discuss the natural rate of unemployment in Macroeconomics, Chapter 9 and Economics, Chapter 19.)
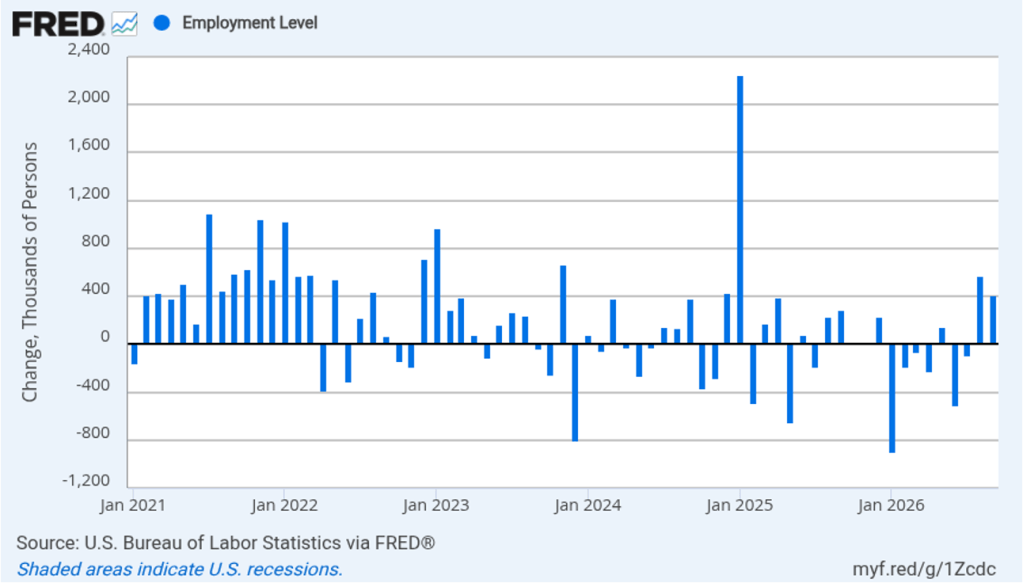
As the following figure shows, the monthly net change in jobs from the household survey moves much more erratically than does the net change in jobs from the establishment survey. As measured by the household survey, there was a net increase of 406,000 jobs in August, far larger than the net increase in employment shown in the establishment survey. Since January, the household survey has shown a net increase in jobs in only three months, with a total net decrease of 840,000 jobs over the period. In contrast, the establishment survey has shown a net increase of 612,000 jobs over the same period. (Note that because of last year’s shutdown of the federal government, there are no data for October or November.)
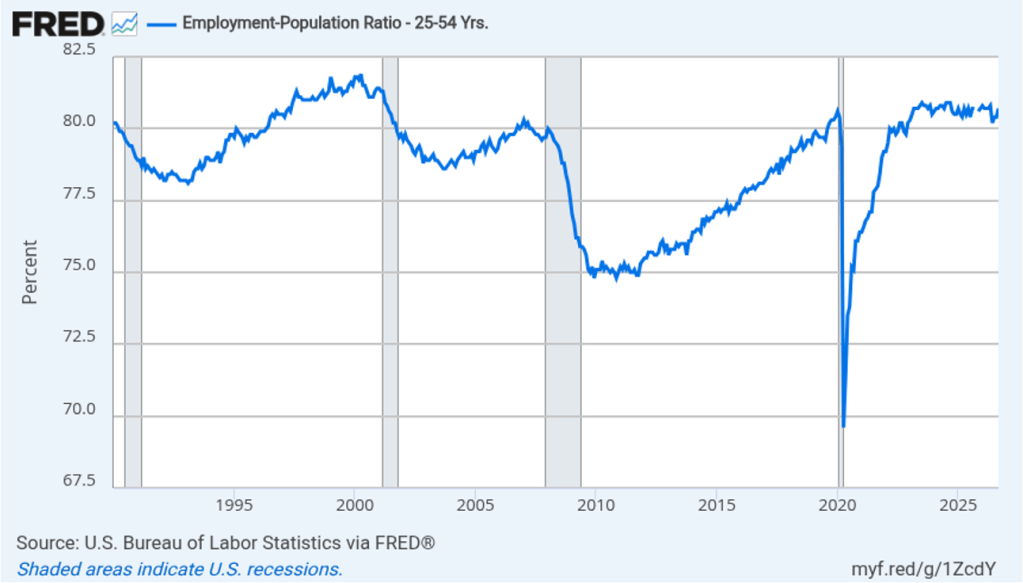
The household survey has another important labor market indicator: the employment-population ratio for prime age workers—those workers aged 25 to 54. In September, the ratio was 80.7 percent, up from 80.4 in August. The prime-age population ratio can show volatility from month to month but has remained above 80 percent every month since December 2022.
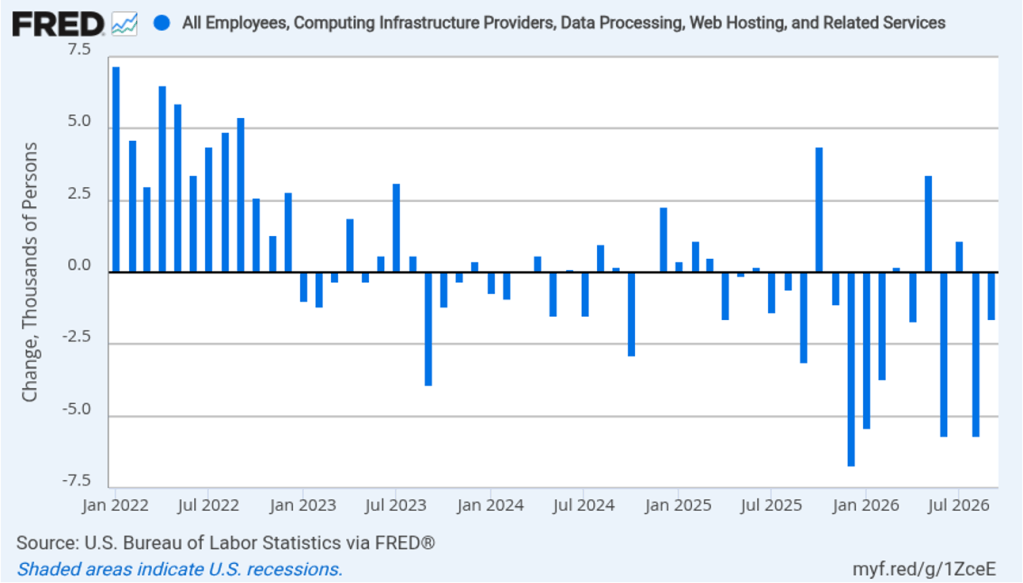
The rapid adoption of artificial intelligence (AI) by many firms has led to forecasts of substantial layoffs of workers in information systems. The following figure shows net employment changes in the BLS employment category of “computing infrastructure providers, data processing, web hosting, and related services.” Employment in this sector has been declining during most months since the beginning of 2023. In September, there was a net decrease of 1,600 jobs.
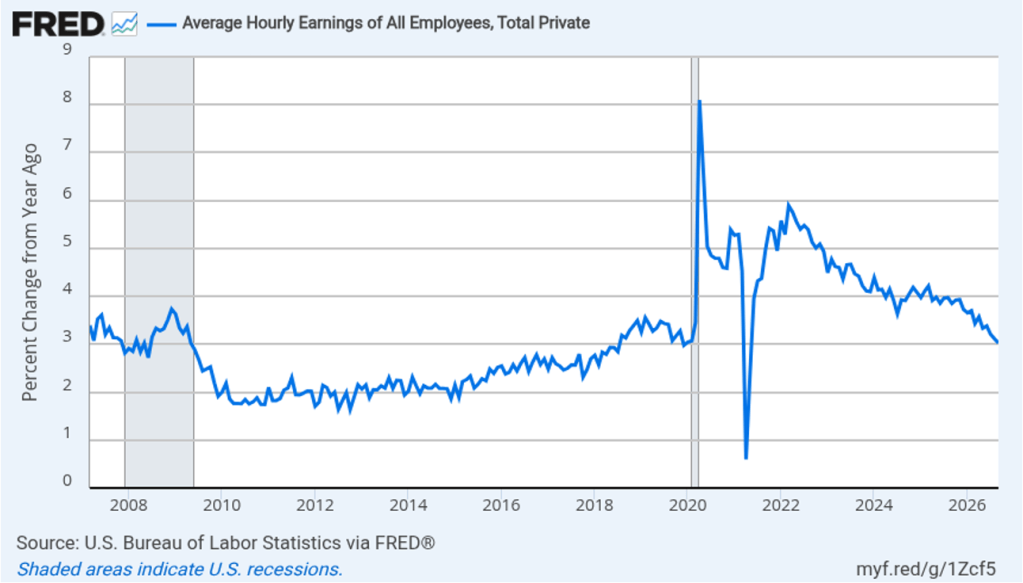
The establishment survey also includes data on average hourly earnings (AHE). As we noted in earlier posts, many economists and policymakers believe the employment cost index (ECI) is a better measure of wage pressures in the economy than is AHE. AHE does have the important advantage of being available monthly, whereas the ECI is only available quarterly. The following figure shows the percentage change in AHE from the same month in the previous year. AHE increased 3.0 percent in September, down from 3.1 percent in August. That was the smallest increase since May 2021. The rate of increase in AHE has been below 4.0 percent each month since August 2025, indicating that cost pressure from wage increases has not been a significant source of price inflation during the past year. Over this same period, wage increases have struggled to keep up with price increases, resulting in a decline in real wages.
With inflation having been above the Federal Reserve’s 2 percent annual target every month since March 2021, the Fed’s policymaking Federal Open Market Committee (FOMC) raised its target range for the federal funds rate at its September meeting. At that time, many analysts expected that the committee would raise its target again at its next meeting on October 27–28.
Trading in the federal funds futures market this morning indicates that investors no longer believe that the committee will increase its federal funds target at its October meeting. A week ago, trading in the federal funds futures market indicated that investors assigned a 64.2 percent to a rate increase at that meeting, while this morning the probability had declined to 21.6 percent. Investors still expect that the committee will increase its target for the federal funds rate at its meeting on December 8–9, although the probability has declined from 92.6 percent a week ago to 85.1 percent today.

